Starting a Systematic Investment Plan (SIP) is often considered a disciplined way to invest regularly, but deciding how much to invest every month is only one part of financial planning. According to experts from Optima Money and Roongta Securities in a conversation on Zee Business, investors need to look beyond their monthly SIP contribution to ensure their investment strategy aligns with broader financial goals and risk management. The focus should be on creating a comprehensive financial plan that integrates multiple factors rather than treating SIP as an isolated investment vehicle. As explained by Optima Money MD Pankaj Mathpal, the objective should not simply be to have an SIP running every month, but to ensure that the investment strategy remains suitable for the investor's goals and continues to keep the overall financial plan on track.
The first consideration should be understanding what goal the SIP is meant to achieve and when the money will be required. As explained by Optima Money MD Pankaj Mathpal, an SIP is not a product or a scheme but a 'mode of investment' that can be used across different types of mutual funds including equity, debt, gold/silver and hybrid funds. For short-term goals, investors can consider debt funds, while hybrid funds may be suitable for medium-term goals and equity funds for long-term goals. Mathpal illustrated how an investor could potentially target a ₹4 crore corpus over 25 years by investing ₹25,000 a month at an assumed 12% return, or starting with around ₹11,000 a month and increasing the SIP by 10% every year. Within equity funds, investors need to make choices based on their goals, including whether mid-cap or small-cap exposure is appropriate. The fund selection should be according to the investor's goal and time horizon, with the more important question being whether the portfolio remains on track to achieve the goal rather than focusing only on fund performance.
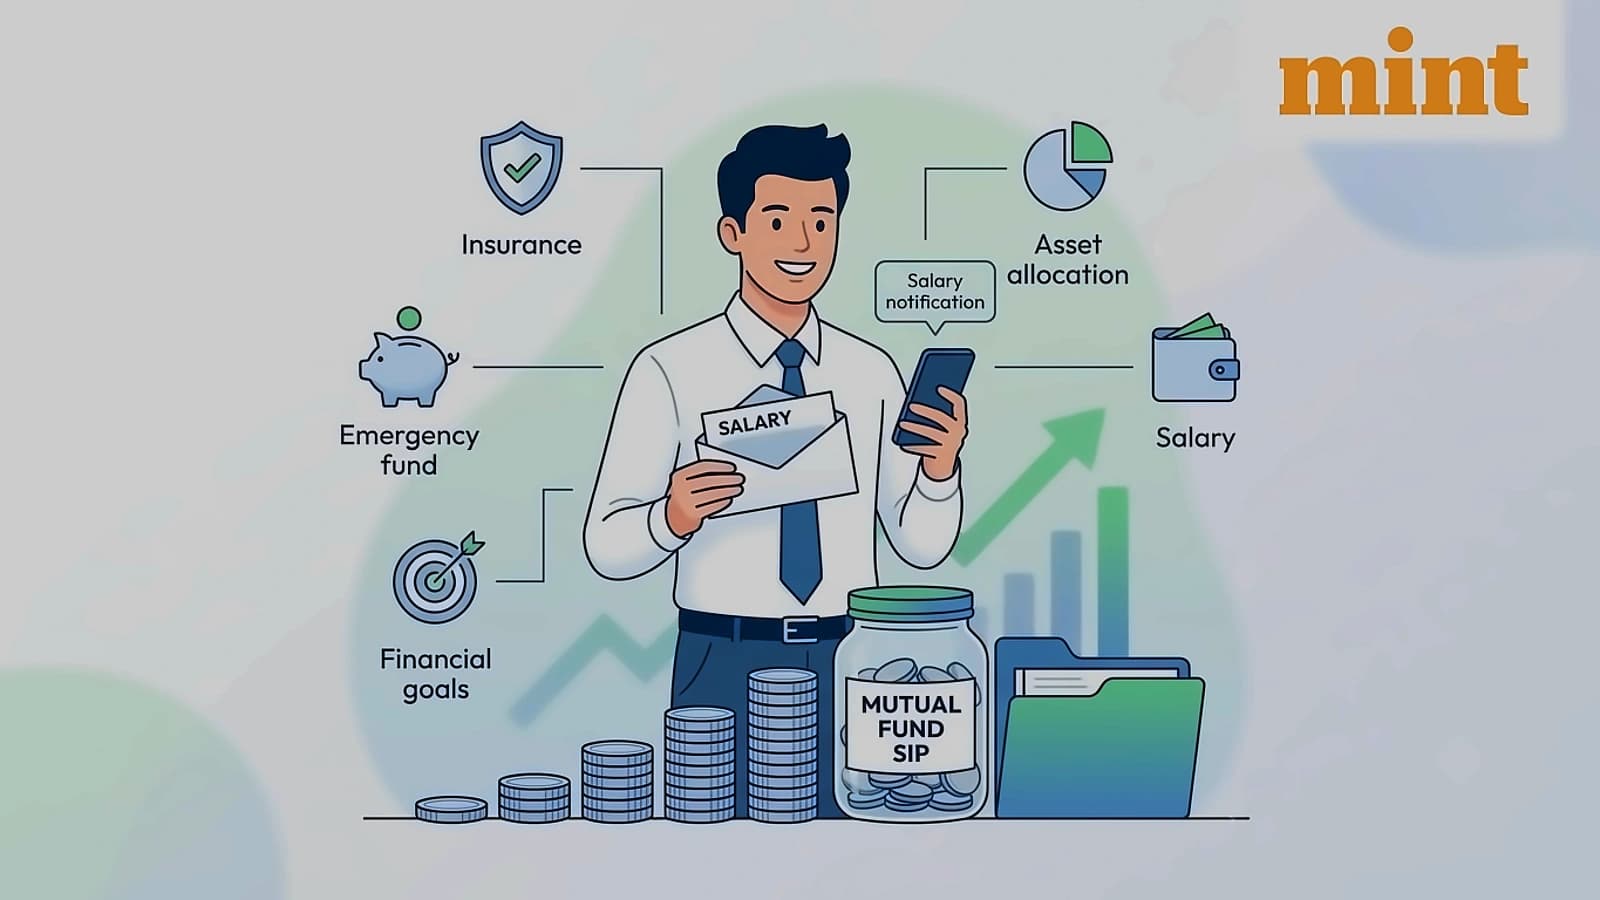
Before committing to SIP investments, investors must ensure adequate emergency preparedness and insurance coverage. According to Roongta Securities CEO Harshvardhan Roongta, 'Insurance and an emergency fund are the first step of financial planning'. He emphasized the importance of health insurance for family members, even if an employer already provides health coverage, disability insurance, and life insurance for earning members. Roongta pointed to situations such as job loss, illness, pay cuts and other unexpected events that can disrupt a household's finances. An emergency fund can provide a financial cushion when such situations arise, as without adequate liquidity, an investor may have to disturb long-term investments to meet immediate expenses. The expert distinguished protection-oriented insurance from investment-oriented products, noting that insurance is particularly important because an unexpected medical emergency or the loss of an earning member can significantly affect a family's finances and potentially derail long-term investment goals. He stressed the need to regularly review insurance requirements as income, expenses and responsibilities change over time.
Before increasing SIP contributions, investors should examine their borrowing needs and existing financial obligations. Mathpal from Optima Money advised that the first question before taking a loan should be whether the loan is actually necessary, noting that loans can have legitimate purposes including buying a house, funding education or supporting a business. He recommended comparing interest rates, conditions and foreclosure charges across different banks and lenders before borrowing. The cost and necessity of debt should be considered alongside investment returns when deciding how much money can comfortably be committed to long-term investments. Mathpal also highlighted the importance of increasing investments as income rises, as a growing income can provide an opportunity to increase the SIP contribution over time rather than keeping the investment amount unchanged throughout the investment journey.
Retirement planning represents another major factor in SIP strategy determination. Roongta highlighted that a person could spend around 20-30 years in the workforce and potentially another 25-30 years after retirement, making it crucial to determine how expenses will be funded once regular income stops. He noted that inflation is important, but rising standard of living also affects retirement requirements as expenses may not remain constant throughout one's working life. As income and lifestyle change, retirement requirements can also increase. Roongta advised investors to review their calculations periodically, including at least once every two years, and reassess whether their investments remain adequate for future requirements. Mathpal also noted that if an investor has a goal of ₹1 crore today, the amount required after 25 years could be more than ₹4 crore if inflation averages 6 per cent, highlighting the need to factor inflation into financial calculations.