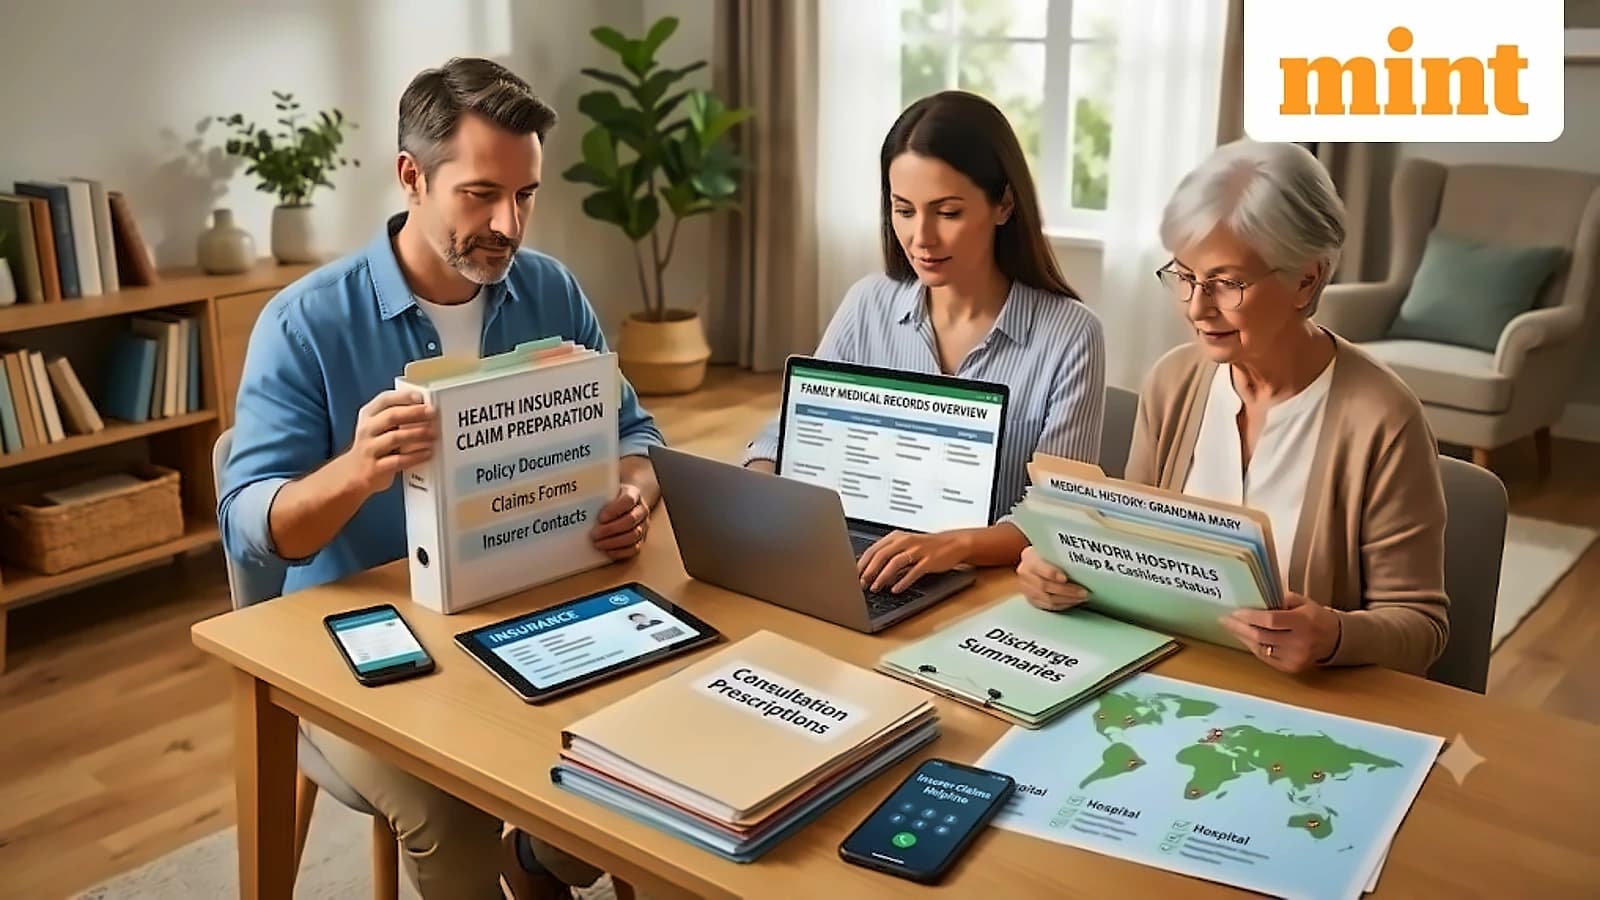
According to reports from Mint, families should ensure health insurance policies are not restricted to the policyholder's mobile device or email inbox. Immediate family members including parents, brothers, and sisters should know where to find complete policy documents, insurance card details, policy numbers, and insurer contact information. The article recommends maintaining both digital and printed copies of policies, with key policy terms, sum insured details, and essential conditions clearly known to all family members. This preparation becomes crucial when the policyholder requires hospitalisation and cannot effectively manage paperwork. Some insurers may also require recent passport-size photographs of the policyholder and family members included in the policy, though the exact document list can differ between insurers, so families should find out what they require beforehand to avoid delays.
As reported by Mint, families should carefully review policy documents to identify hospitals near homes and workplaces that are part of their insurer's network. The article emphasizes that network hospitals may offer cashless treatment subject to policy terms and insurer authorization. If parents live in different cities, network hospitals should also be checked in that area. Network lists can change, so families should verify hospital status through insurer websites or helplines before admission. This advance preparation can save valuable time during medical emergencies.
According to Mint, families should maintain one-page medical histories for each insured member covering previous surgeries, hospitalisations, ongoing medicines, treatments, diagnoses, and resistance to particular medicines. The article recommends keeping prescriptions, consultation records, and discharge summaries in the same folder for quick reference. Accurate, timely sharing of medical information can help doctors understand patient medical history and support seamless treatment. This preparation helps with documentation requirements during claims processing and ensures consistent disclosure of medical information.
As reported by Mint, policyholders should review policy documentation beyond just paying premiums. Key areas to check include sum insured and bonus details, room-rent limits, co-payment and sub-limits, exclusions, waiting periods, and restoration benefits. The article emphasizes that understanding policy terms can help families anticipate potential out-of-pocket expenses. Actual amounts payable by insurers depend on policy terms, admissible expenses, and applicable authorization requirements. Thorough review of policy terms can help families manage claims more effectively during medical emergencies.
According to Mint, families should create a dedicated health insurance claims folder containing all essential policy documents, insurance cards, identification documentation, medical history, current prescriptions, and previous discharge summaries. The article recommends preserving discharge summaries, investigation reports, prescriptions, itemized bill details, and payment receipts after hospital stays. It is prudent to save insurer helpline numbers, customer support numbers, and insurance advisor contact details. When hospitalisation is planned, families should inform the insurer beforehand and share treatment details to begin the claim process. At the hospital, visit the insurance desk and fill out the pre-authorisation form with policy and treatment details, then submit policy papers and medical details to the hospital for claim processing. The hospital sends the form and medical reports to the insurer for review and approval, after which the insurer checks treatment details and pays directly to the hospital. Families should collect all receipts and treatment documents, get the claim form from the insurer, fill it out, and send completed forms and supporting documents within the required timeframe.