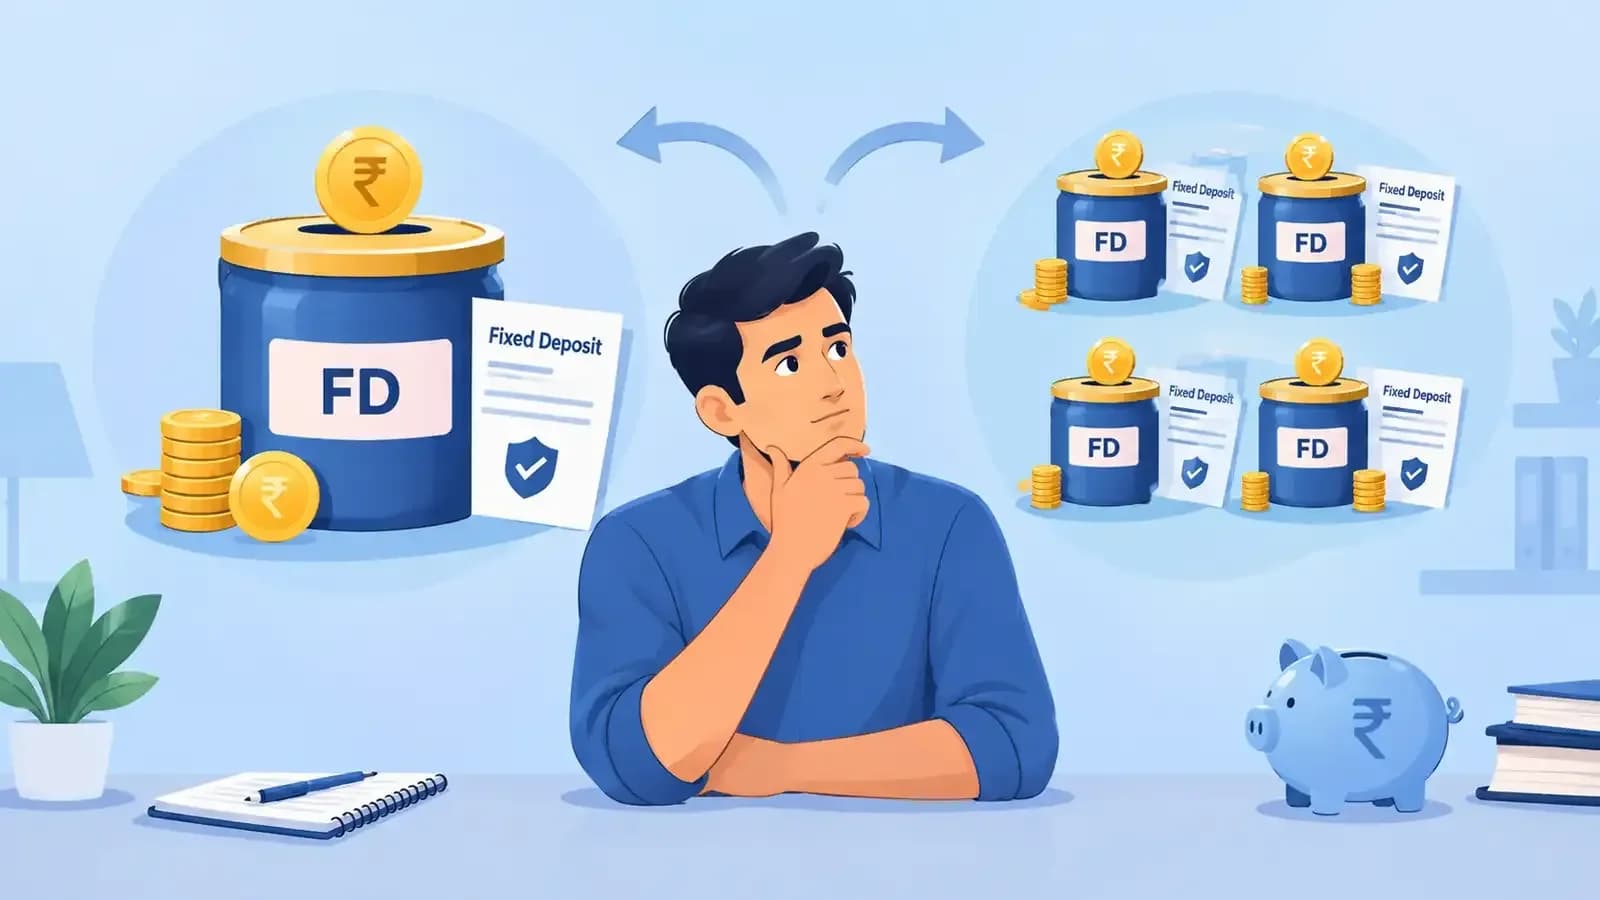
When investing ₹20 lakh in fixed deposits, the primary consideration should be flexibility over maximizing returns. According to financial analysis, there is no major difference in overall returns whether the amount is kept in one large FD or divided into smaller deposits. The key advantage of splitting comes when early withdrawal needs arise, as it provides the flexibility to close only specific deposits while keeping others invested. This approach becomes particularly valuable when premature closure becomes necessary, as it allows investors to avoid penalties on the entire investment.
The interest rate differential between banks becomes significant over longer investment periods. As reported by financial analysis, ₹20 lakh at 6.50% grows to approximately ₹37.54 lakh over 10 years, compared to ₹36.67 lakh at 6.05%. This represents a difference of roughly ₹87,000 before tax. The comparison shows that SBI offers 6.05% for 5-year and 10-year tenures, while HDFC Bank provides 6.40% for 5-year deposits and ICICI Bank offers 6.50% for both 5-year and 10-year tenures. The rate variations across banks and tenures significantly impact long-term returns.
FD laddering emerges as an alternative approach for investors seeking different maturity dates. According to financial experts, this strategy involves spreading deposits across one-year, two-year, three-year and four-year FDs with amounts of ₹5 lakh each. When one deposit matures, investors can decide whether to use the money or reinvest at prevailing rates. This approach provides flexibility without tying the entire ₹20 lakh to a single maturity date, making it particularly useful for investors with varying cash flow requirements over time.
Cross-bank diversification can create additional complexity in FD strategies. When ₹5 lakh each is invested in SBI, HDFC Bank, ICICI Bank and another bank, the total maturity amount could be higher or lower than keeping the entire ₹20 lakh in one bank. This approach works best when banks offer different rates for the same tenure, as each deposit grows at varying rates. However, investors must consider premature withdrawal rules, taxation implications, and compounding frequency across different banks before implementing this strategy.