Indian equity markets have shown signs of recovery after a period of weakness as foreign institutional investors (FIIs) were net buyers of ₹6,688.37 crore in the cash segment on September 2, while domestic institutional investors (DIIs) also remained buyers with net purchases of ₹2,812.98 crore. However, closer analysis reveals that the FII buying figure includes a large ₹12,061 crore block transaction involving Altius Telecom Infrastructure Trust, making the underlying FII cash flow approximately ₹5,373 crore of net selling when excluding this transaction. The market's price action indicates that volatility has not disappeared, with the Nifty 50 closing at 23,914.45 on September 2, down 0.6%, marking its third consecutive losing session and taking the index below the 24,000 level.
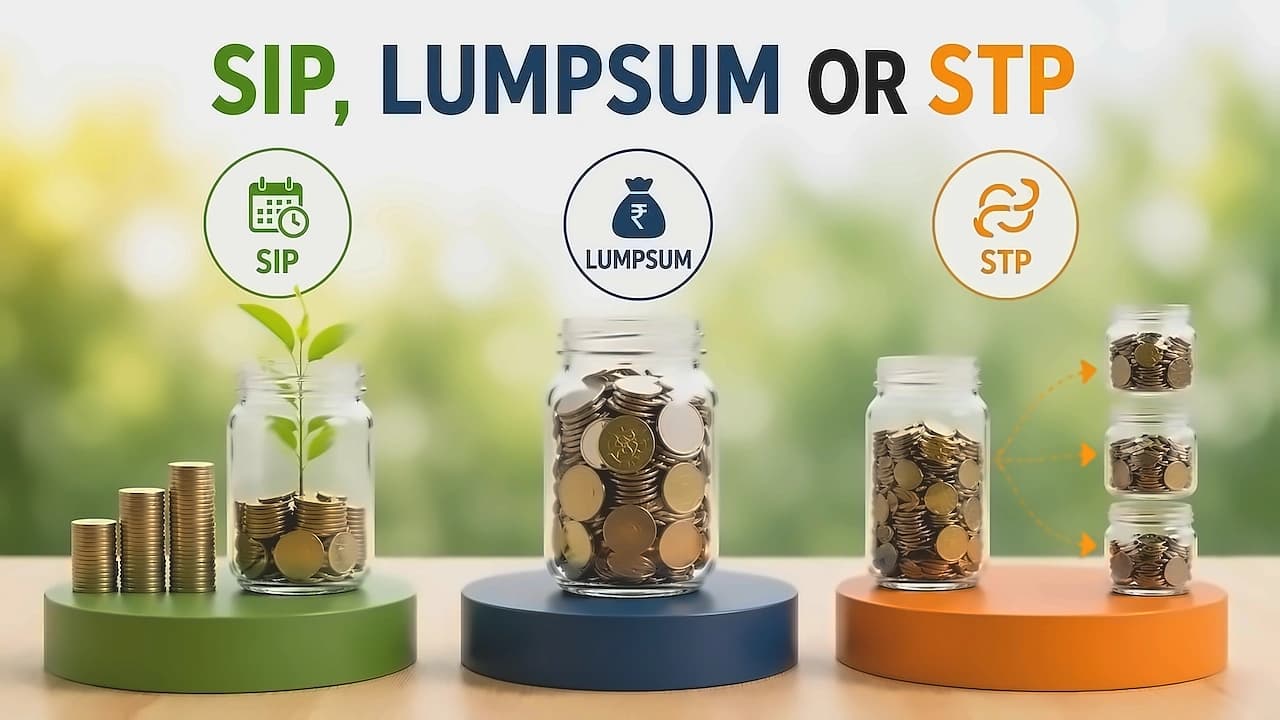
With ₹10 lakh ready for investment, investors face a critical decision between three primary strategies: lumpsum investment, systematic investment plans (SIPs), and systematic transfer plans (STPs). According to reports from NDTV Profit, the optimal choice depends on individual risk tolerance, investment horizon, and comfort level with market volatility. Recent market data from WhiteOak Capital Mutual Fund study shows that investors who entered equities near the 2024 market highs have now spent nearly 2 years dealing with flat-to-negative returns, highlighting the timing risks associated with lumpsum investments. For investors with a long-term horizon, waiting indefinitely for the "perfect" entry point may not be practical, but deploying the entire amount immediately after a market rebound can expose investors to timing risk if markets correct again.
A lumpsum investment involves committing the entire ₹10 lakh to mutual funds at once rather than spreading capital across multiple instalments. As reported by NDTV Profit, this approach immediately exposes the complete investment to market movements, with gains accruing across the full amount during market rallies and losses occurring during downturns. Recent market data from WhiteOak Capital Mutual Fund study shows that investors who entered equities near the 2024 market highs have faced significant challenges, with the Sensex going nearly 700 days without making a new record high - its longest such stretch since 2012. However, historical analysis demonstrates that difficult entry points don't necessarily mean poor long-term outcomes, with SIPs delivering strong returns during crisis periods including 15% XIRR during the 2008-2009 crisis and 16.3% XIRR during the 2018-2020 stall.
Systematic Investment Plans typically involve regular contributions of a fixed amount into mutual funds at predetermined intervals. According to NDTV Profit, investors cannot simply convert their ₹10 lakh savings into an SIP by depositing the entire amount at once. The strategy requires splitting the corpus into smaller portions and deploying them over a series of instalments. SIPs offer the advantage of rupee cost averaging and provide a smoother psychological experience for investors, though they may not be suitable for investors seeking immediate market exposure. The WhiteOak Capital Mutual Fund study highlights that SIPs delivered 15% XIRR during the 2008-2009 crisis, 10.2% XIRR during the 2011-2012 period, and 16.3% XIRR during the 2018-2020 stall. With a fixed SIP amount, a lower fund unit price buys more units, while a higher unit price buys fewer units.
Systematic Transfer Plans involve investing the initial ₹10 lakh in a source scheme, typically a debt- or liquid-oriented mutual fund, before transferring predetermined amounts to equity funds at regular intervals. As reported by NDTV Profit, if an investor opts to transfer ₹1 lakh monthly to equity funds, the entire corpus would transition to the target fund over 10 months. This approach combines elements of both SIPs and lumpsum investments, with the capital earning returns in the source fund before each transfer while providing gradual market entry. The WhiteOak Capital Mutual Fund study confirms that "systematic deployment" through SIPs for regular investments and STPs for staggering lump sums is generally better than investing a lump sum at once. STPs offer a middle ground for investors concerned about current market valuations or market volatility, allowing investors to participate if the recovery continues while retaining funds to invest at lower levels if markets fall again.
Ultimately, the decision on when to deploy a lumpsum investment should depend on the investor's time horizon, risk appetite, and financial goals. A short-term rebound does not necessarily mean that volatility has ended, and investors should remember that daily FII flows alone do not determine the market's direction. Global interest rates, crude oil prices, corporate earnings, geopolitical developments, valuations and subsequent foreign fund flows can all influence equities. One approach is to invest the lumpsum in tranches over several weeks or months, or consider investing a portion of the available money now while keeping the remaining amount aside. The study emphasizes that "conviction should build through a stretch like this, not fade," suggesting that prolonged periods of weak returns can eventually create conditions for stronger returns when markets catch up with underlying fundamentals.