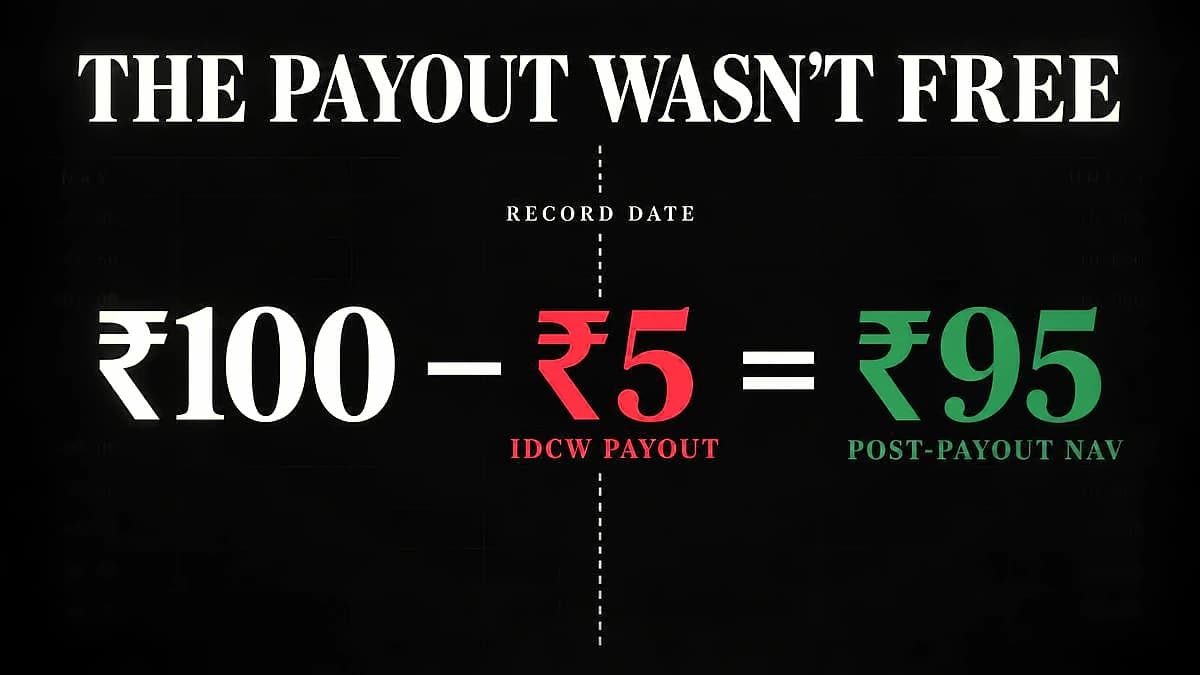
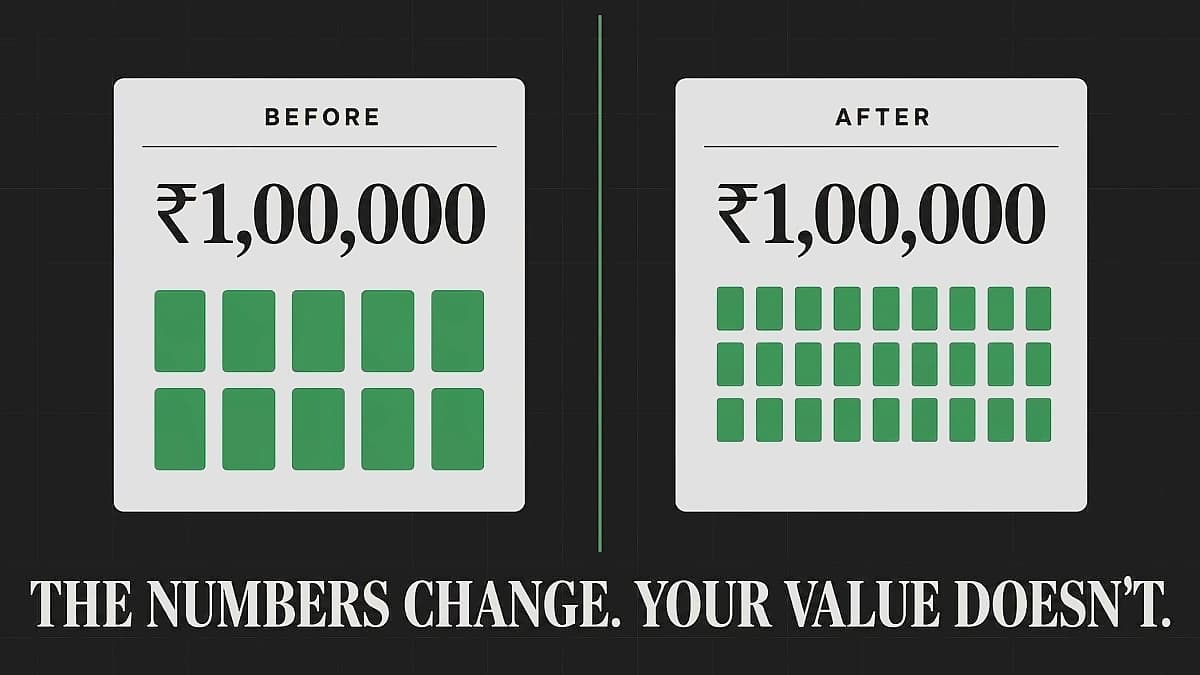
When investors purchase mutual funds before the record date, they receive shares at the previous day's NAV (Net Asset Value) rather than the current day's NAV. According to reports from the source, this timing difference creates a temporary discount for early buyers, as they effectively purchase shares at a lower price than the current market rate. However, this advantage is typically short-lived, as the fund's NAV adjusts to reflect the new share count after the record date.
Purchasing mutual funds before the record date triggers capital gains tax obligations for investors. As reported by the source, the tax liability arises when investors sell their shares, regardless of whether they purchased before or after the record date. Section 94(7) previously provided relief by allowing investors to defer capital gains tax on purchases made before the record date. However, Section 94(7) mostly no longer applies to current mutual fund transactions, eliminating this tax advantage for early buyers.
The decision to purchase mutual funds before the record date requires careful consideration of market timing and tax implications. According to the source, investors must weigh the temporary NAV discount against the immediate capital gains tax liability and the elimination of Section 94(7) benefits. The strategy becomes particularly relevant when funds are trading near their ex-dividend dates, as early purchases can provide additional benefits beyond the record date timing.