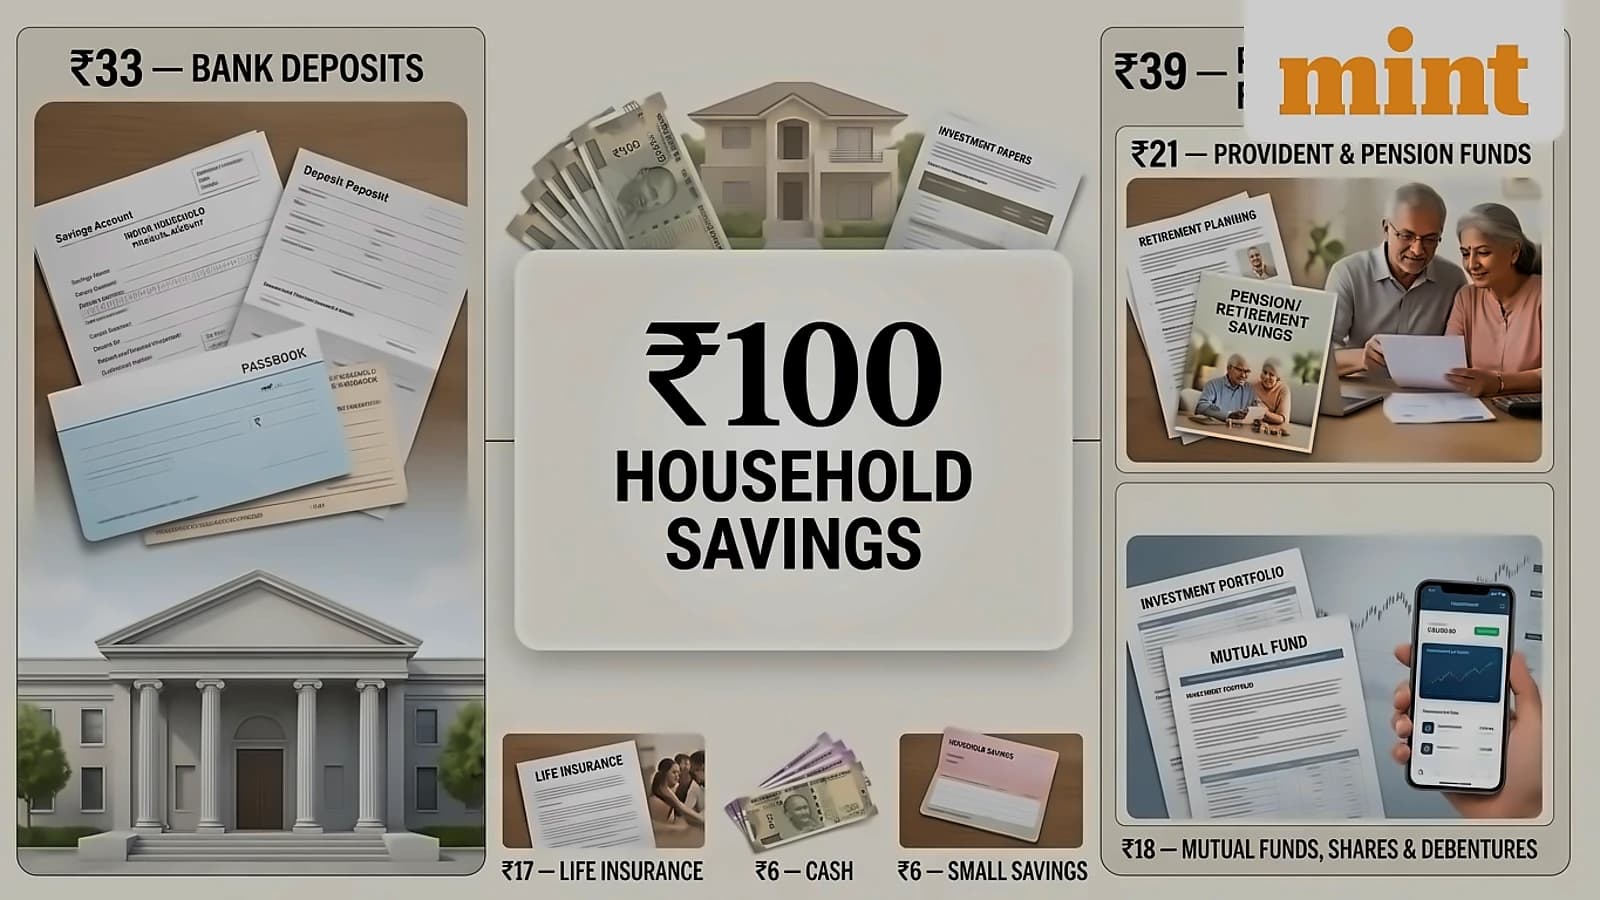
Indian households are experiencing a significant structural shift in their investment preferences, with mutual funds and equities nearly doubling their share of domestic financial savings in a single year. According to Bajaj Mutual Fund's latest market symposium, mutual funds and equities accounted for 15% of household financial savings in FY25, up from 9% in FY24 and 8% in FY19. This represents a dramatic increase in household participation in capital markets, marking a fundamental change in India's investment landscape. As per Franklin Templeton India Mutual Fund's report titled "Financialization of Savings in India – From Safety to Scale," market-linked instruments now account for 18% of household financial savings in FY25, rising from 4% in FY21 and 11% in FY24. This market-linked category has overtaken life insurance at 17% and continues to grow rapidly.
The shift has coincided with a corresponding decline in traditional banking deposits, as reported by Bajaj Mutual Fund. Currency and bank deposits fell to 33% of household financial savings in FY25 from 43% in FY24 and 48% in FY19. According to Franklin Templeton's analysis, bank deposits' share of gross financial savings dropped from 52% during FY71-80 to 33% in FY25. This trend reflects the growing preference among Indian households for diversified investment options beyond traditional savings accounts and fixed deposits, indicating a broader move toward capital market participation. Between March 2020 and March 2025, managed investments grew at a CAGR of about 17.5%, compared with 11.7% for bank deposits, with the difference narrowing from nearly ₹32 lakh crore to ₹7 lakh crore.
The mutual fund sector has demonstrated remarkable growth in its relative importance to the overall financial system. As reported by Bajaj Mutual Fund, mutual fund assets as a proportion of bank deposits rose from 16% in 2020 to 31% in 2025. According to Franklin Templeton's data, mutual fund AUM rose from ₹35.32 lakh crore in July 2021 to ₹85.76 lakh crore in July 2026, achieving a CAGR of about 19%. This significant increase in mutual fund penetration suggests that capital market instruments are becoming increasingly mainstream for Indian households, with mutual funds now representing a substantial portion of total household financial assets. Despite strong growth, India remains under-penetrated by global standards, with the mutual fund industry's AUM-to-GDP ratio at 19.9% in FY26, remaining far behind developed markets and even slightly ahead of China.
Despite the growing allocation to mutual funds, investor returns have lagged significantly behind fund performance, according to Morningstar data cited by Bajaj Mutual Fund. Over three years, funds returned 10.47% against investors' 7.79%, while over five years, funds delivered 8.79% versus investors' 6.25%. The performance gap widened substantially over a decade, with funds achieving 12.33% returns compared to investors' 6.54%, suggesting that longer investment horizons have not eliminated poor timing effects. As per Franklin Templeton's report, this divergence highlights the challenges Indian investors face in achieving optimal market timing and sectoral allocation, even as they increase their mutual fund exposure.
India's under-penetration in mutual funds presents significant opportunities for economic growth and market stability. With over 1.4 billion people and a growing middle class, mutual fund investments remain less than one-fifth of the country's GDP despite rising incomes and a young population entering prime earning years. SIPs have transformed investing from occasional activities to regular monthly habits, while digital platforms and mobile apps have made investing accessible to smaller cities. As more people gain formal jobs and access to banking services, first-time savers are likely to move beyond bank deposits toward long-term investment products. A deeper mutual fund industry could help increase capital formation, improve market stability, and strengthen the financial security of Indian households, potentially supporting double-digit growth rates for many years.