A well-managed equity fund that loses 18% while the index drops 24% has actually performed well, according to market analysis. As reported by Value Research, this fund manager successfully managed to fall less than the market during a sharp decline. The fund needs to rise approximately 22% to return to its starting point, while the index requires about 32% recovery. However, investors often focus on absolute returns rather than benchmark-relative performance, leading to emotional selling decisions based on timing rather than fund quality. The difficulty lies in comparing two different yardsticks - benchmark-relative returns versus absolute returns that depend on when investors entered the market cycle.
The same fund can appear completely different to investors with varying entry points. According to Value Research analysis, a fund that delivered 8% last year but has five-year annualized returns of 18% may seem disappointing to recent investors, while long-term holders see it as part of normal equity fund volatility. This variation is routine in equity funds, which build track records through uneven years of performance including some great, good, bad, and poor periods. Recent developments show this principle in action, with funds like SCHD and HDV demonstrating vastly different performance depending on the measurement period. An investor who has stayed invested for a few years sees one dull year among many good ones, while someone who arrives after a boom feels tricked into buying a fund that used to be good but has suddenly turned ordinary.
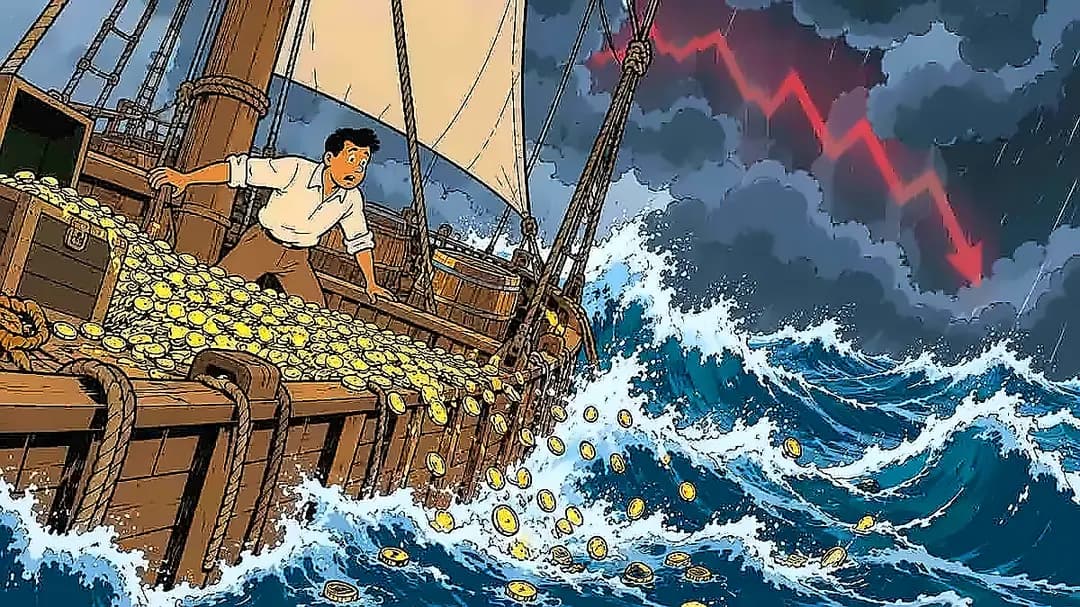
The psychological effect of red numbers on portfolio trackers can override rational investment decisions. As reported by Value Research, equity investing typically rewards patience and consistency over time, with SIPs particularly vulnerable to stop-start investing patterns. The color of numbers on screens reflects timing rather than fund quality, making it crucial for investors to separate emotional reactions from objective analysis. Recent market examples demonstrate this clearly, with investors often making decisions based on short-term performance rather than long-term fundamentals. A red number on your portfolio tracker is just a paper loss until you talk yourself into selling, at which point it becomes real.
Value Research recommends evaluating fund performance over one year or more to eliminate random market variations. Funds that consistently perform near the bottom for more than a year require closer examination, while exceptional short-term performance can naturally slip to middle positions in performance tables. The analysis suggests using five- and seven-year returns to provide longer-term context and determine whether funds still deserve patience despite recent challenges. The same tests also protect investors in the opposite situation - funds that are going bad but showing green numbers due to timing of investments. Recent performance data supports this approach, showing how different funds can dominate in different time periods, making it essential to consider multiple measurement windows before making investment decisions.