Gujarat-based LCC Projects, an engineering, procurement and construction (EPC) company operating in irrigation and water supply segments, officially launched its maiden public issue today (September 9, 2026) with strong market response. The ₹427.14 crore IPO has been priced in the range of ₹139-146 per share, giving the company a valuation of ₹4,229.2 crore at the upper end of the price band. According to Business Standard, the Grey Market Premium (GMP) stands at ₹180, indicating an estimated listing gain of around 23% over the issue price. The issue comprises a fresh issue of 1.77 crore shares worth ₹258 crore and an offer-for-sale (OFS) of 1.16 crore shares worth ₹169.14 crore. The anchor book for institutional investors opened on September 8, 2026, with the issue remaining open until September 11, 2026. Share allotment is expected to be finalized by September 15, 2026, with trading expected to commence on both BSE and NSE from September 17, 2026. The lot size for an application is 102 shares, with the minimum investment requirement being ₹14,892 for retail investors based on the upper price band.
As reported by The Hindu BusinessLine, ET Now, and CNBC TV18, LCC Projects is looking to raise up to ₹258 crore through a fresh issue of equity shares, while promoters Arjan Suja Rabari and Laljibhai Arjanbhai Ahir will offload 1.15 crore shares worth ₹169.14 crore through an offer-for-sale (OFS). The company intends to utilize ₹14.6 crore of the net fresh issue proceeds for purchasing equipment, ₹180 crore for repayment of certain borrowings, and the remaining funds for general corporate purposes. As of July 2026, the company had total consolidated borrowings of ₹1,817.7 crore on a consolidated basis. SBI Securities notes that the company plans to utilize ₹180 crore from the fresh issue to repay borrowings, which is expected to reduce the debt-to-equity ratio to 0.6x from 1.0x in FY26 and improve profitability through lower interest costs. Anand Rathi also highlights that the debt-to-equity ratio is expected to decline to 0.6x post repayment from 1x in FY26.
According to reports from Moneycontrol, ET Now, and CNBC TV18, LCC Projects has demonstrated healthy financial performance in recent years. Profit for the fiscal year ended March 2026 grew 28.1 percent to ₹286.4 crore, while revenue increased 23.4 percent to ₹3,600.3 crore compared with the previous year. The company maintains a robust order book of ₹7,953.1 crore as of March 2026, with irrigation and water supply projects accounting for the largest share at 83 percent. SBI Securities notes that the company's revenue, EBITDA and adjusted PAT recorded CAGRs of 21.5 percent, 34.6 percent and 39 percent respectively during FY24-FY26. Anand Rathi reports that revenue from operations grew at a CAGR of 21.5 percent, while PAT grew at a CAGR of 53.2 percent between FY24 and FY26. At the upper price band, the company is valued at 14.9x FY26 P/E based on post-issue capital, which SBI Securities considers reasonable. The brokerage notes that LCC Projects' profitability metrics are superior within the EPC segment.
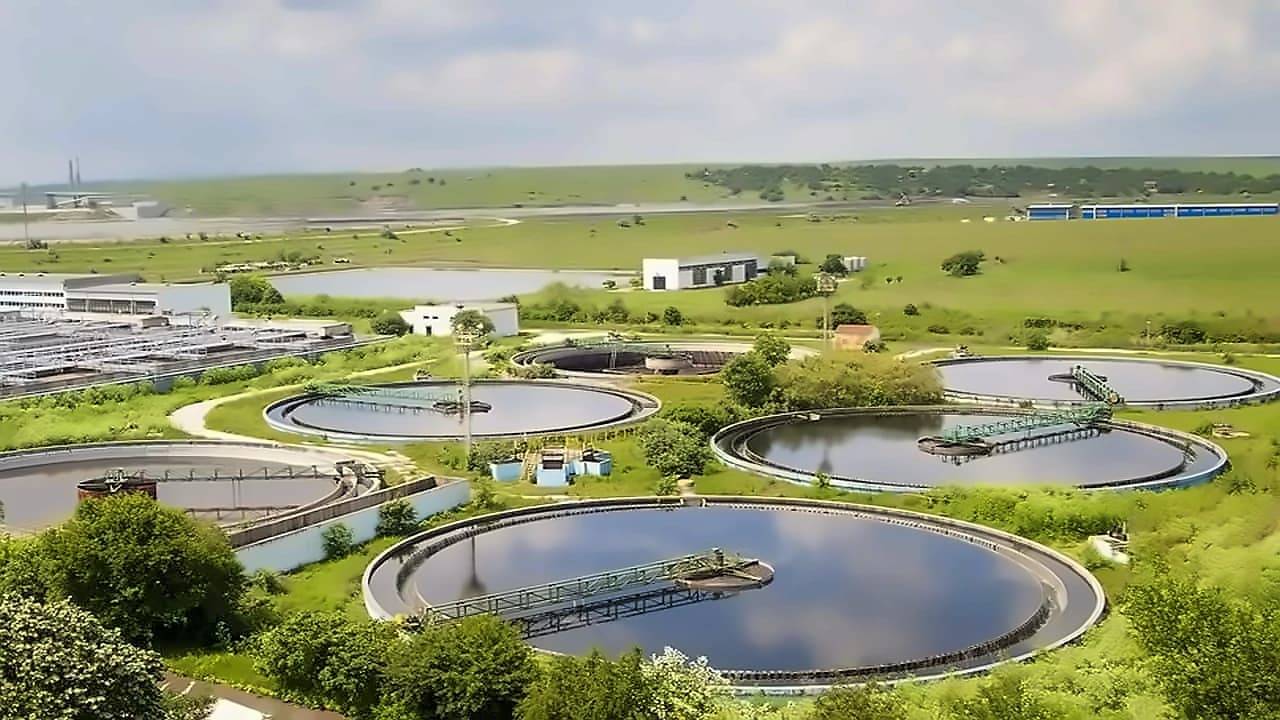
As reported by The Hindu BusinessLine, ET Now, and CNBC TV18, LCC Projects is a multidisciplinary engineering, procurement and construction (EPC) company that has executed projects over two decades in the irrigation and water supply segment. The company specializes in constructing dams, barrages, weirs, hydraulic structures, canals, pipe distribution networks, lift irrigation works, water supply schemes and other EPC projects. The company has expanded its presence across 12 states and serves various central and state government agencies. The company has recently established a precast concrete manufacturing facility in Jaspur, Gujarat. The IPO is being managed by Motilal Oswal Investment Advisors as the sole merchant banker, with KFin Technologies serving as the registrar. SBI Securities recommends subscribing to the IPO for the long term, citing the company's strong order book, in-house project designing capabilities and established presence in the irrigation and water supply segment. The company competes with listed players such as Vishnu Prakash R Punglia and Enviro Infra Engineers.
Multiple brokerages have issued positive recommendations for LCC Projects IPO, with four out of six brokerages giving a 'buy' call on the issue. According to Essential Business Intelligence, brokerages including Anand Rathi Shares & Stock Brokers, Arihant Capital Markets, and Swastika Investmart have recommended subscribing to the issue. Arihant Capital notes that the company has strong positioning in irrigation & water infrastructure, robust order-book visibility, healthy financial growth, and healthy financial growth. Swastika Investmart highlighted that LCC Projects as a stable infrastructure growth play, with its combination of modest valuation (~14x FY26 P/E), high return metrics, strong order book, and immediate debt reduction via IPO proceeds making it suitable for long-term investors. Anand Rathi and Ventura have also issued 'subscribe' ratings on the IPO. SBI Securities recommends subscribing to the issue for long-term at the cut-off price, citing the company's superior profitability metrics in the EPC segment and significant de-leveraging potential. The positive brokerage sentiment reflects confidence in the company's strong order book, healthy execution capabilities in the irrigation and water infrastructure segment, robust profitability, and expected debt reduction through IPO proceeds.