According to reports from The Hindu BusinessLine, brokerage firm has initiated coverage on TajGVK Hotels & Resorts (renamed as Krishna GVK) with a BUY rating and a target price of ₹475. The current market price stands at ₹319.55 as of October 6, 2026, indicating a potential upside of approximately 49% from current levels. As per Monarch Network Capital (MNCL) Research, the brokerage's investment case rests on a combination of strong occupancy at the company's existing hotels, scope for higher room rates, the consolidation of Taj Santacruz in Mumbai and the upcoming Taj Yelahanka property in Bengaluru. However, the stock has declined 26% over the past year, trading in a narrow range of ₹281.35 to ₹438.25 with a market capitalisation of ₹1,975 crore. The company was incorporated on February 2, 1995 in Andhra Pradesh and operates as a joint venture between Indian Hotels Company Limited (IHCL) and the Hyderabad-based GVK Group.
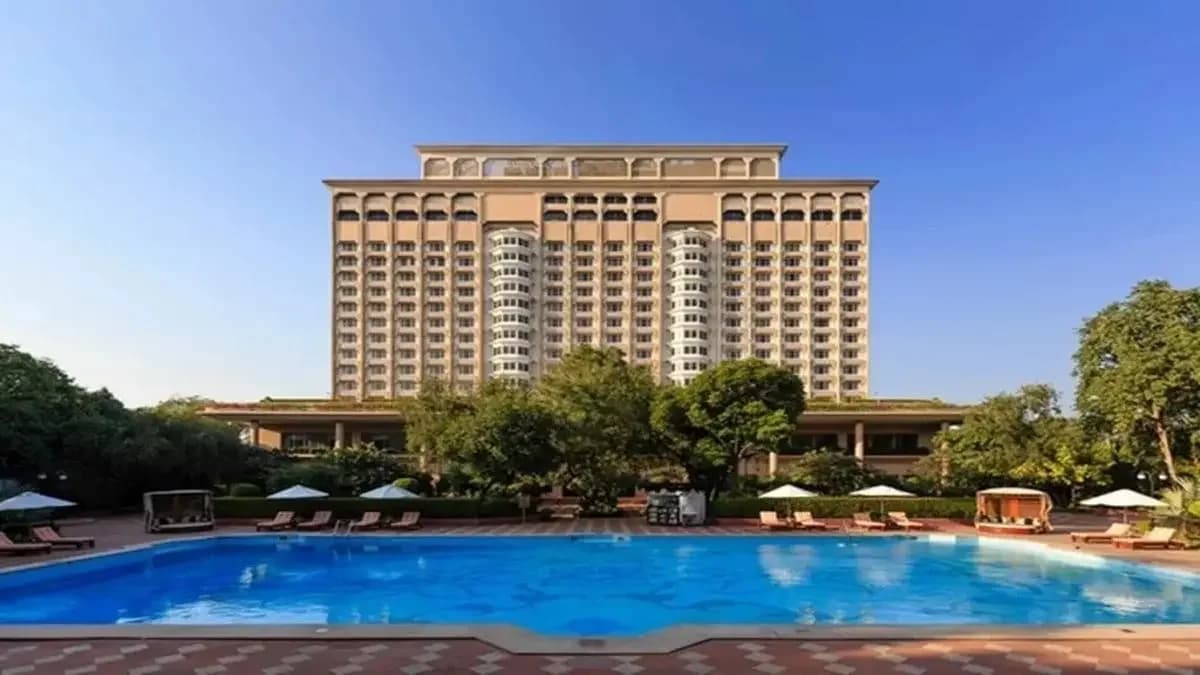
As reported by The Hindu BusinessLine, the company is entering a structurally stronger phase of growth after a prolonged period of limited owned-asset additions. The growth strategy is supported by the upcoming Bengaluru hotel in H2FY27e, consolidation of Taj Santacruz, Mumbai, and a pipeline of further organic and inorganic opportunities. According to Monarch Research, the company was moving from a period of limited owned-asset additions into a fresh growth cycle, with its existing portfolio providing a strong base for earnings growth. The brokerage forecasts revenue to grow at 26.4% CAGR from approximately ₹517 crore to ₹1,044 crore by FY29, while EPS is expected to grow at 15.4% CAGR over FY26-FY29E. The combination of improving pricing, incremental room capacity and operating leverage is expected to drive superior earnings during this period. The company could expand its portfolio to around 4,000 keys over the next four to five years through organic and inorganic growth.
According to the brokerage analysis reported by The Hindu BusinessLine, revenue and EBITDA are expected to grow at about 26.4% and around 26.6% CAGR, respectively over FY26-29E. As per Monarch Research, the company's earnings profile is forecast to grow at 26.4% CAGR for revenue and 15.4% CAGR for EPS over FY26-FY29E. The valuation is based on 8 times FY29E earnings, which implies the target price of ₹470. However, the stock appears inexpensive at a trailing P/E of about 5 on one data provider, though this figure is flattered by large other income, with other sources showing a P/E between 14 and 23. The forecast needs revenue to double from current levels, which is only possible with new capacity additions, and EPS growing slower than revenue suggests margin pressure or dilution. The company's zero-debt balance sheet and healthy cash generation provide flexibility for expansion.
As reported by The Hindu BusinessLine, the company is positioned well for India's evolving luxury hospitality opportunity through a combination of premium hotel assets, Taj's operating expertise and a renewed expansion cycle. According to Monarch Research, TAJGVK offers a differentiated combination of ownership of scarce luxury hotel assets and access to the Taj operating platform. The company's existing portfolio operates at high occupancy, particularly in Hyderabad, with the three luxury hotels in the city accounting for around 42% of Hyderabad's luxury hotel inventory. Strong occupancy across its existing portfolio, particularly in Hyderabad, provides a solid base for ARR-led growth and refurbishment-led premiumisation. As of October 6, 2026, the company has a market capitalisation of ₹1,975 crore and operates with a P/E ratio of 4.89 and P/B ratio of 1.90. The stock offers a dividend yield of 0.63% per annum and is classified as a smallcap stock in the hospitality sector.
According to latest market data from Business Standard, TajGVK Hotels & Resorts shares are trading at ₹319.55 as of October 6, 2026, with a 52-week high of ₹438.85 and 52-week low of ₹281.75. The stock has shown mixed performance with 1.09% gains in one week, but declined 2.71% over the past month and 6.71% over three months. Over longer periods, the stock has delivered -25.58% returns over one year, but has gained 9.62% over three years and 17.87% over five years. The company offers a dividend yield of 0.63% per annum and is classified as a smallcap stock in the hospitality sector. Monarch Research argues that the sell-off has gone too far, with the upside call resting on growth that has not yet appeared, and investors should check the earnings quality and Q2 results before making investment decisions. The key near-term trigger is the planned opening of its 256-key hotel in north Bengaluru in the second half of FY27, which is expected to contribute meaningfully to revenue and EBITDA from FY28.