Systematix has maintained its Buy rating on Dodla Dairy Ltd. with an unchanged target price of ₹1,295, implying a potential upside of 23% from the current market price of ₹1,045. According to the brokerage's latest report, the valuation is based on a P/E multiple of 24 times, which is broadly in-line with the company's current one-year forward multiple. The brokerage has kept its FY27E-FY29E estimates unchanged, building a revenue/profit after tax compound annual growth rate of 13%/24% for the FY26-FY29E period.
As of September 24, 2026, Dodla Dairy shares are trading at ₹1,045, showing a 6.44% increase over the last six months despite being down 24.33% on a year-on-year basis. The stock opened at ₹1,049.50 compared to its previous close of ₹1,048.60, with intraday trading ranging between ₹1,045.00 to ₹1,058.00 and an average price of ₹1,051.50 for the day. Looking at its 52-week performance, the stock has touched a low of ₹964.10 and a high of ₹1,405.00.
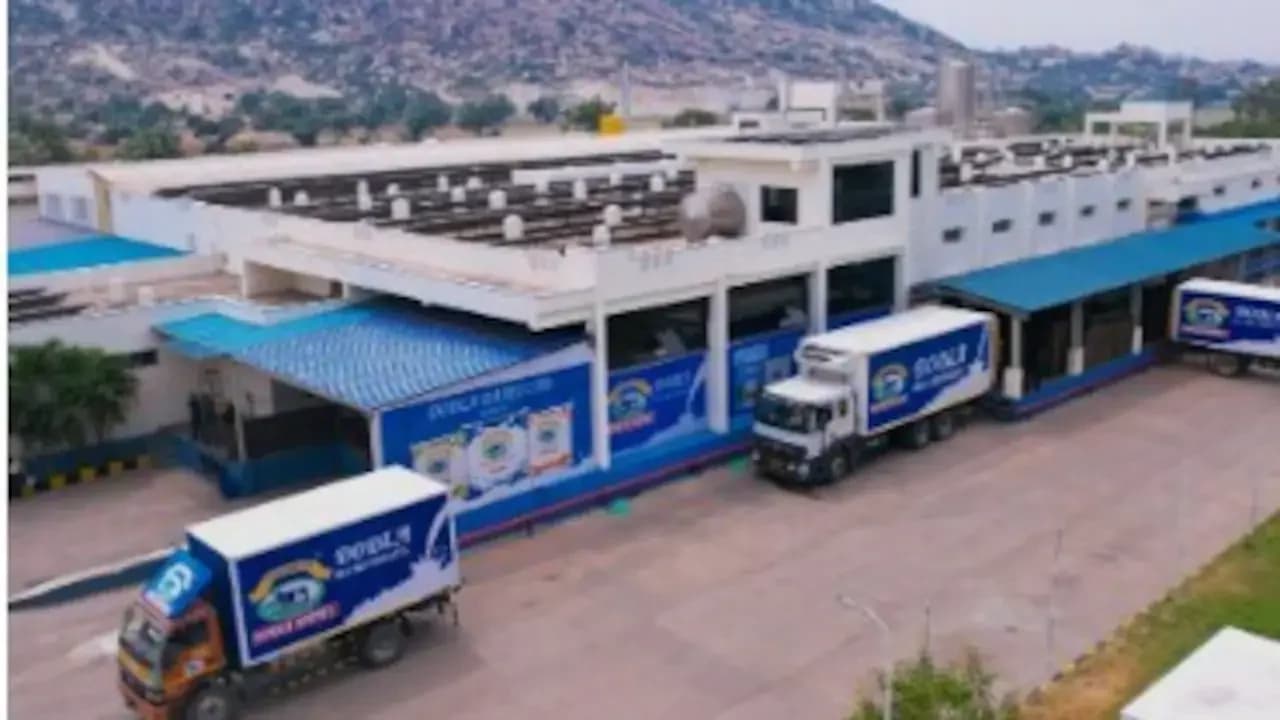
Management issued an upbeat business outlook at their recent non-deal roadshow in Singapore, reaffirming revenue growth guidance of 15% over the medium term. The company expects sales' salience of value-added products (VAP) to increase to 40% from the current 30%, translating into incremental revenue/volume accretion of ₹2,800 crore/15 LLPD in the next 2-3 years. This growth will be driven by processing volume additions at the Maharashtra greenfield plant of 10 LLPD, Bihar and Jharkhand (Osam) of 3 LLPD, and Uganda greenfield plant of 1.5-2 LLPD. The Maharashtra plant will sell 1-2 LLPD locally while serving north Karnataka and Telangana, while the Uganda facility enables expansion in fresh milk beyond the legacy presence in long-life milk and yogurt.
According to Systematix, persistent sharp milk inflation has resulted in operating profit margins getting re-set to materially lower levels over the past two quarters. However, the QoQ margin uptick of 40bps in Q1 FY27 and the further uptick guided for Q2 FY27 support the brokerage's view that operating profit margins troughed in Q4 FY26 and should pick up gradually over FY27 as price hikes land and mix improves with increasing salience of VAP/Africa. The brokerage builds a slim OPM decline in FY27E followed by accretion in subsequent periods.
As reported by Systematix, while milk supply could be constrained and volatile, and procurement costs could remain elevated near-term, the company has the requisite playbook of pricing, inventory management, procurement network and supply chain capabilities to navigate this phase. The brokerage expects the company to benefit from incremental sales from capacity expansions and addition of Osam, supporting its positive outlook despite current market challenges in the dairy sector. With the Maharashtra plant and Uganda expansion, Dodla plans to maintain stable India growth of c.12% and robust Africa growth of c.22% (FY26-FY29E sales CAGR), supported by sustained high VAP growth of c.20%.