Siddharth Vora, Head of Quantitative Investment Strategies at PL Asset Management, maintains a metals-heavy portfolio with nearly 25% allocation in ferrous and non-ferrous companies. According to reports from The Economic Times and ET Now, his fund holds significant positions in Hindalco, Nalco, JSW Steel, Tata Steel, Hindustan Copper, and SAIL. Vora expressed confidence in metals as a conviction call, citing Q4 earnings as validation for the sector's performance. He sees no urgent reason to trim these positions despite the substantial allocation, with metals remaining the standout performer among industrials and auto sectors that have also delivered strong results.
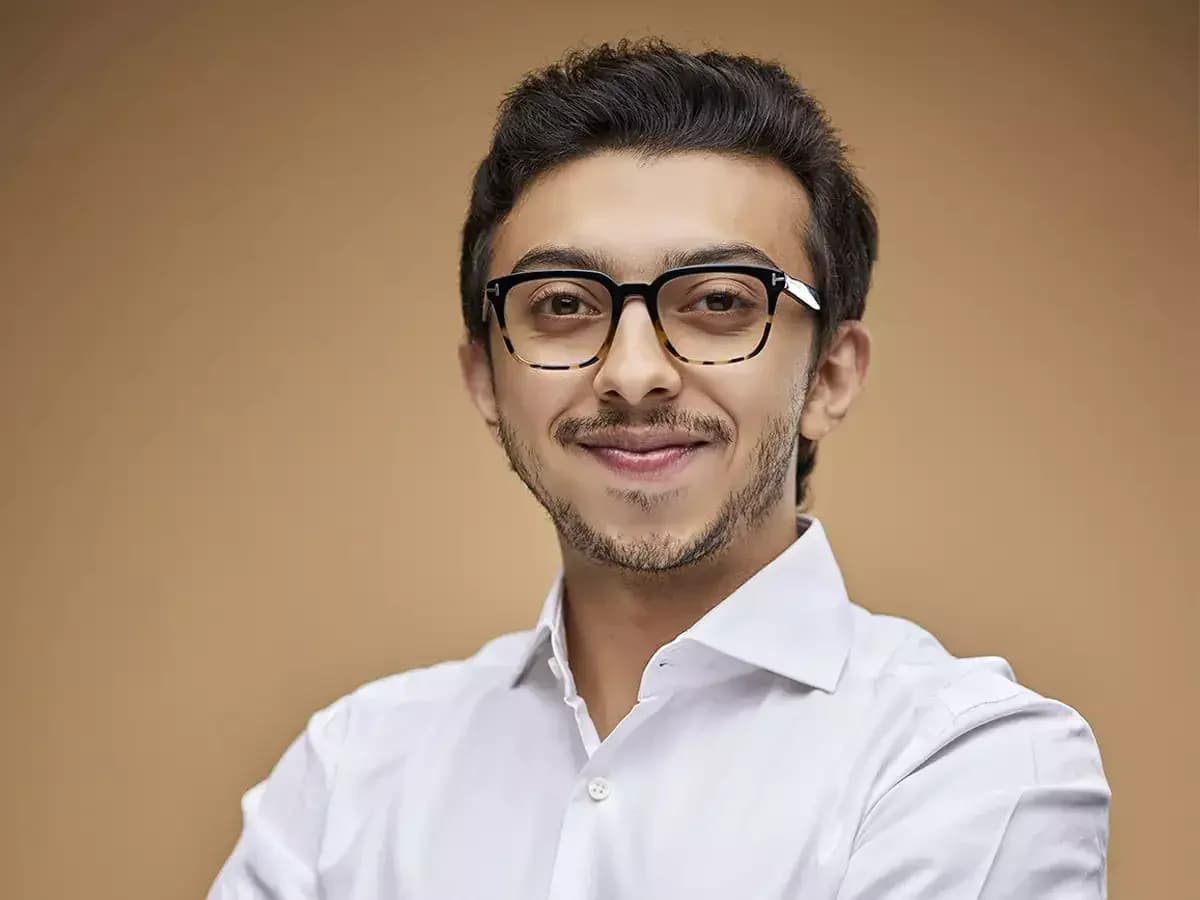
Vora believes the crude oil thesis driving his next repositioning may be reversing after over a year of outperformance. As reported by The Economic Times and ET Now, he now expects a potential shift in market trends as key macro indicators like crude oil and bond yields may have peaked. This could lead to a rotation into consumer-facing companies, energy-intensive businesses, and select cyclicals if crude oil meaningfully cools. The fund manager is actively hunting for names in this basket as part of his strategic rotation strategy, moving away from stocks that have benefited from elevated crude prices. Recent developments show petrol prices in Delhi have now crossed ₹100 per litre following the fourth increase in less than two weeks, with fuel prices rising across India due to global supply issues from the Iran-US conflict.
Vora's preference lies with PSU banks over private sector lenders in the banking space. According to The Economic Times and ET Now, his management approach involves active weight adjustments, periodic profit booking, and maintaining fund-level volatility within acceptable limits. Notable PSU bank positions include Bank of Baroda and Canara Bank, though position sizes are regularly adjusted based on market conditions. The management style emphasizes active weight adjustments with profits booked periodically to keep fund-level volatility in check.
The fund maintains a structural rather than fundamental approach to quick commerce investments. As reported by The Economic Times and ET Now, Vora's quantitative models cannot yet translate the financial profiles of these platforms into buy signals. Until the data aligns with the model's parameters, these names remain on the watchlist, appreciated but unowned. This represents a deliberate investment strategy rather than a fundamental assessment of the sector's prospects, with the problem being structural rather than fundamental in nature.
For FY27, Vora expects broader earnings visibility to remain hostage to geopolitical and commodity outcomes. According to The Economic Times and ET Now, his base case anticipates a recovery that could arrive faster than markets currently expect. Recent economic developments show retail inflation may reach 5 percent by June due to fuel price increases and higher gold and silver import duties. Economists believe the Reserve Bank of India will observe the impact of these hikes before considering interest rate changes in the latter half of the fiscal year. The fund manager's confidence stems from his conviction that the current market trends may be shifting toward more traditional sectors.