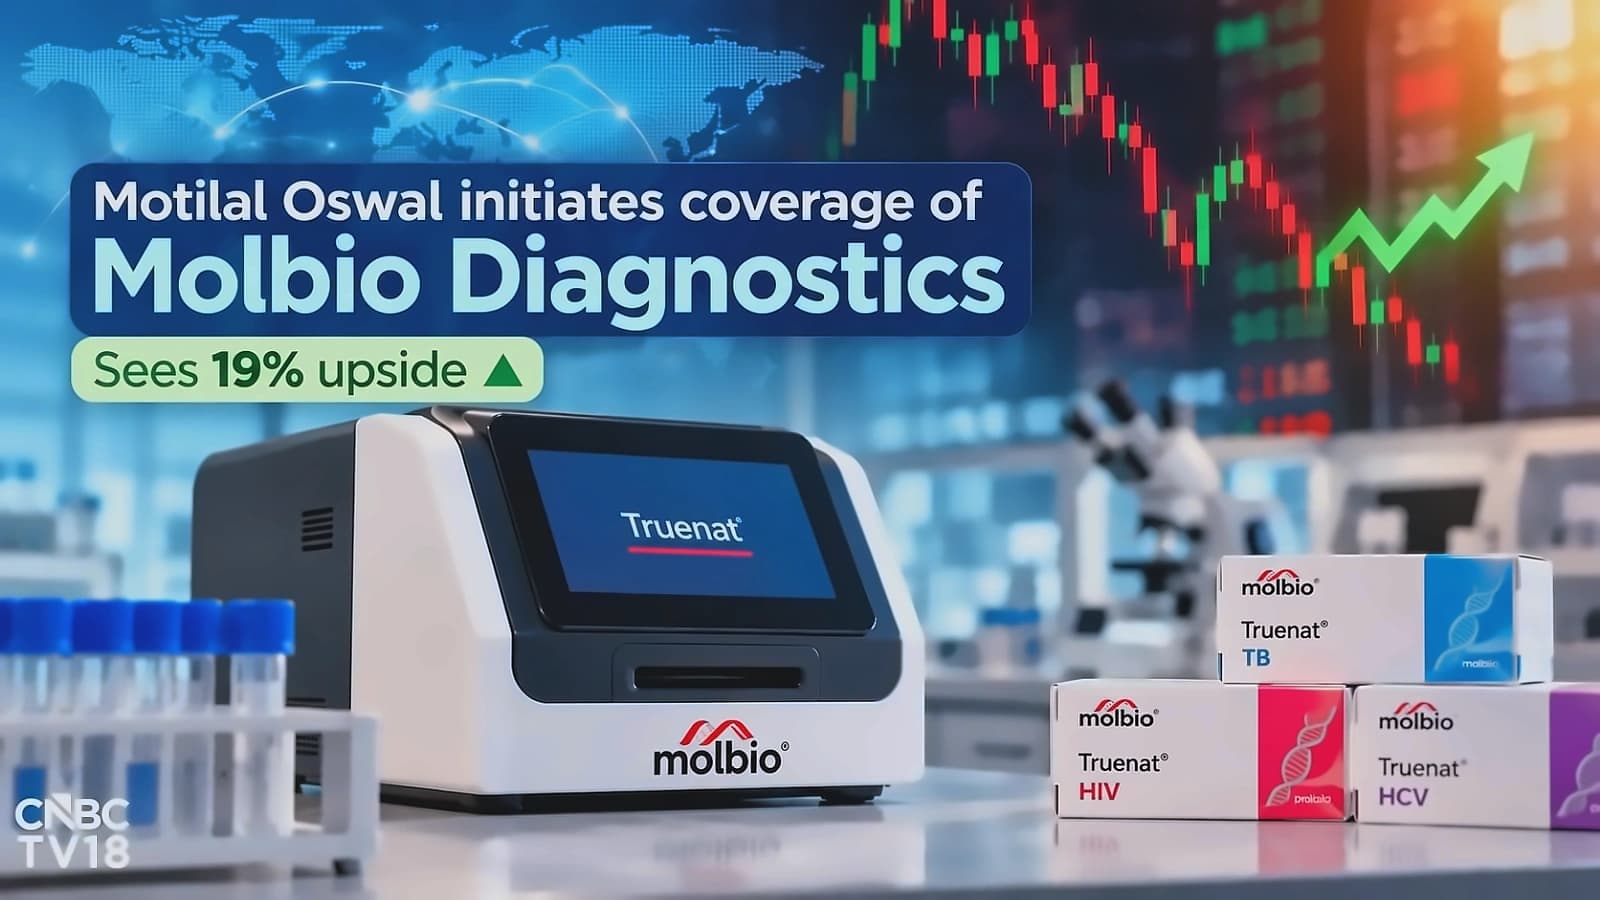
Despite Molbio Diagnostics shares surging 83% from its IPO price of ₹807 in less than two months, Motilal Oswal Financial Services has maintained its 'Buy' rating with a target price of ₹1,800, implying a 20% upside from the stock's ₹1,543.75 current market price. The brokerage's bull-case scenario presents significantly higher potential with a target of ₹2,575, suggesting an upside of about 70% from Friday's close. According to reports from CNBC TV18, this bull-case scenario assumes faster sales growth, sharper margin expansion, and a higher valuation multiple than the base case. The brokerage models a 23% revenue CAGR, 910 basis point margin expansion, and 50% PAT CAGR over FY26-29E, with Nirmal Bang assigning a 45 times 12-month forward earnings multiple to arrive at the target price. In the bull-case scenario, Motilal Oswal applies a 50-times 12-month forward price-to-earnings multiple, representing a 20% premium to the sector multiple of 36 times, citing the company's differentiated research-and-development-led business model and earnings growth potential.
Molbio Diagnostics made its stock market debut on August 17, listing at ₹980 on both NSE and BSE, representing a 21.44% premium to the IPO price of ₹807. The issue comprised a ₹200-crore fresh issue and an offer for sale of 91.66 lakh shares. As reported by CNBC TV18, the stock reached a post-listing high of ₹1,686, already doubling from its issue price within 21 days of listing. The stock has demonstrated strong momentum with 27% gains over the last month, 13% rise in October after an almost 21% increase in September. However, shares declined more than 2% in intraday trade on Tuesday, 6 October, looking set to extend losses for the second consecutive session. According to latest reports, the stock had gained three days in a row ahead of Monday's session, having gained 24% during this stretch, with shares recovering from the day's low to gain as much as 3% to make an intraday high of ₹1,558.3, before giving up all gains to trade 0.7% lower at ₹1,503.
TrueNat remains central to the Molbio thesis, contributing around 90% of FY26 revenue and expected to grow at around 16% CAGR over FY26-29, supported by further device placements and higher utilisation of the existing installed base through additional indications. As reported by CNBC TV18, the brokerage also expects the company's shift towards recurring test-kit sales to support growth, with Truenat test kits accounting for around 72% of consolidated revenue in FY26 and the segment having grown at a 39% CAGR during FY24-26. Beyond tuberculosis (TB), Motilal Oswal sees HPV testing as an important opportunity to increase utilisation of the TrueNat installed base. The expanding installed base, widening assay menu and global scale-up are key levers for sustainable growth, while increasing utilisation should drive operating leverage. The business model is increasingly weighted towards test kits rather than equipment, with Truenat device sales growing at an 18% CAGR between FY23 and FY26, while test-kit sales surged at 84% CAGR during the same period. According to The Economic Times, the platform has more than 12,500 devices across over 90 countries and offers 43 assays covering 30 diseases, with the same Truenat machine supporting multiple diseases as consumables change according to the test.
The growth story is expanding beyond Truenat with significant opportunities in digital imaging and digital pathology. Through Prognosys, Molbio has entered digital imaging, including ultra-portable X-ray systems, with Motilal Oswal expecting Prognosys revenue to grow at around 36% CAGR over FY26-29. The brokerage sees a strategic fit between Prognosys and Truenat, with X-rays helping screen patients for TB and Truenat providing molecular confirmation. Molbio's expansion into digital pathology through OptraSCAN provides another growth opportunity, though the business remains at an early stage and profitability is not expected in FY27. According to The Economic Times, the company has another 34 assays in its pipeline, with lower utilisation of devices and test kits leaving room for growth without proportional additions to hardware. Motilal Oswal expects Molbio's revenue to grow at a 23% compounded annual growth rate (CAGR) over FY26-29, driven by higher utilisation of its TrueNat platform, expansion of its assay menu, and growth in digital pathology and imaging businesses.
All three analysts covering the stock maintain a 'buy' rating, with Motilal Oswal's target being the highest among brokerages at ₹2,575, compared to Jefferies at ₹1,600 and IIFL at ₹1,550. According to CNBC TV18, the brokerage expects Molbio's expansion into digital pathology through OptraSCAN and imaging through Prognosys to broaden its addressable market, with OptraSCAN's US commercialisation being a key opportunity, although the business is still at an early stage of commercialisation. However, Motilal Oswal has identified dependence on government orders and elevated working capital as key risks to its thesis, along with customer concentration, high revenue contribution of TB testing, delays in regulatory approvals and slower-than-expected adoption of Truenat as additional concerns. The growth opportunity comes with concentration risks, as TB test kits accounted for about 70.2% of FY26 revenue and 96% of test-kit volumes, with the top 10 customers accounting for about 83% of FY26 revenue. Other identified risks include slower-than-expected adoption of Truenat instruments, manufacturing issues, and delays in product registrations or manufacturing licenses.