According to reports from The Economic Times, InterGlobe Aviation shares have declined around 8% in a month as fresh escalations in the Middle East conflict pushed oil prices beyond $100 per barrel. The stock has overall fallen a little over 1% in a week and nearly 8% in one month. In the longer term, IndiGo shares have delivered 99% returns over three years and 158% in five years. The company currently has a market capitalisation of nearly ₹1.91 lakh crore. As per latest reports, the stock has fallen nearly 4% in 2026 so far and more than 12% in one year. According to CNBC TV18, rising crude oil prices and a sharp jump in US bond yields are clouding India's market outlook, with market experts recommending staying invested in companies with strong earnings.
As reported by The Economic Times, IndiGo gained three points in domestic and international market share since June 2025, backed by an order book of over 900 aircraft in a supply-constrained environment at Boeing and Airbus. The brokerage noted that India's aviation landscape showed divergent trends, with IndiGo leading while other incumbents lagged. Air India posted its largest-ever net loss of over ₹22,000 crore in FY26, forcing capacity cuts of 22-27%, while SpiceJet's fleet contracted to 21-25 aircraft given persistent liquidity constraints. Ambit Institutional Equities believes that IndiGo will gain as others lose ground, citing tight aircraft supply and competitor transformation as key drivers.
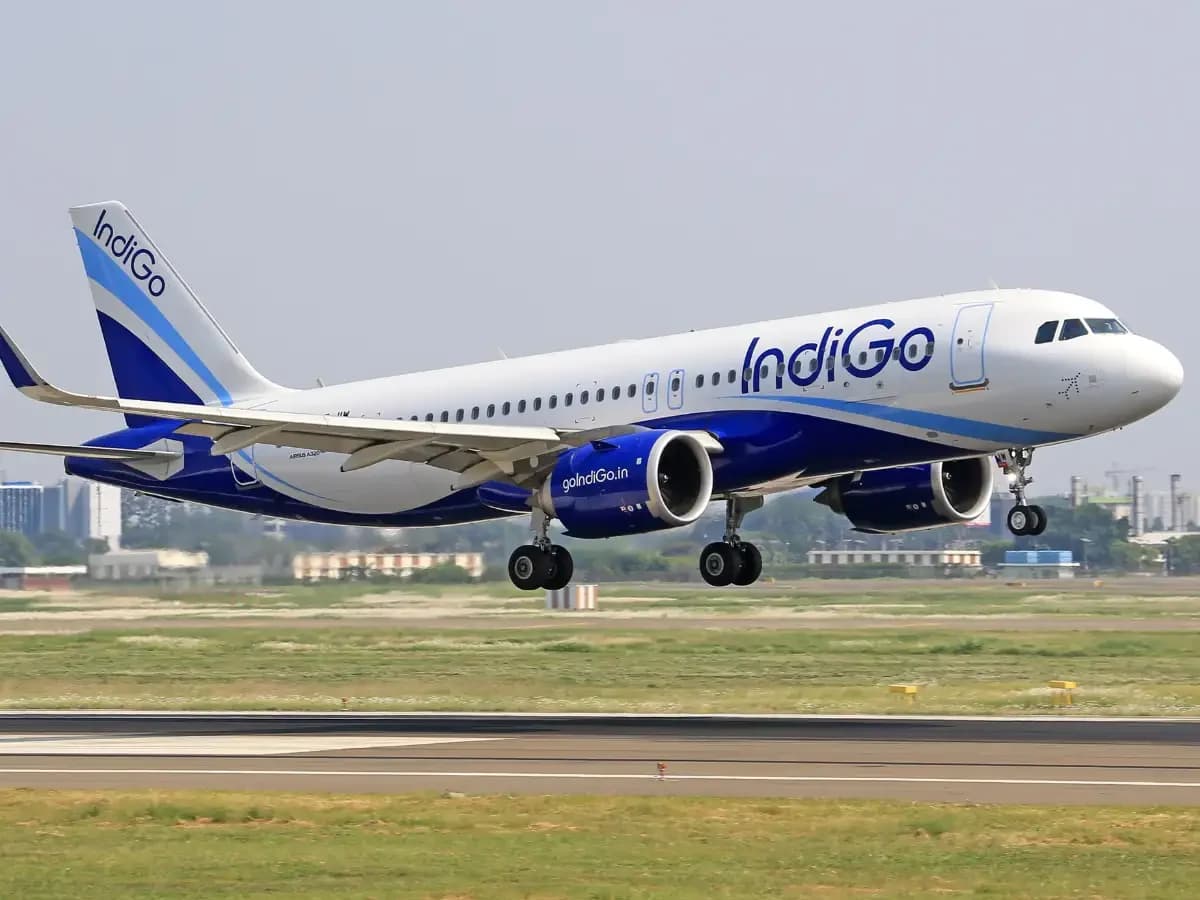
According to The Economic Times, Ambit Institutional Equities expects traffic to remain soft in the near term (domestic and international declined in August 2026), but is expecting 14% and 37% revenue and EBITDA CAGR respectively in FY26-29. The brokerage believes that tight aircraft supply, competitor transformation and rising domestic market share create a strong long-term growth outlook for the airline, despite short-term fuel and forex-driven losses. It maintains its 'Buy' call on the stock with a target price of ₹5,300 apiece, implying 6.5% upside potential from the stock's previous closing price of ₹4,975 apiece.
As reported by The Economic Times, Ambit Institutional Equities listed out key risks to its bullish view on IndiGo. These include prolonged elevated air turbine fuel or further rupee depreciation impacting earnings, an extended Middle East conflict continuing to disrupt West Asia routings and cost structures industry-wide, and a faster-than-expected Air India stabilisation. Other risks include possible Airbus delivery delays constraining IndiGo's own fleet growth, Air India's new CEO Tewolde Gebremariam's long-haul network-building track record from Ethiopian Airlines which could impact market share, and a well-capitalised new entrant entering the airline sector with explicit government encouragement to break the IndiGo–Air India duopoly following IndiGo's own operational crisis last year.