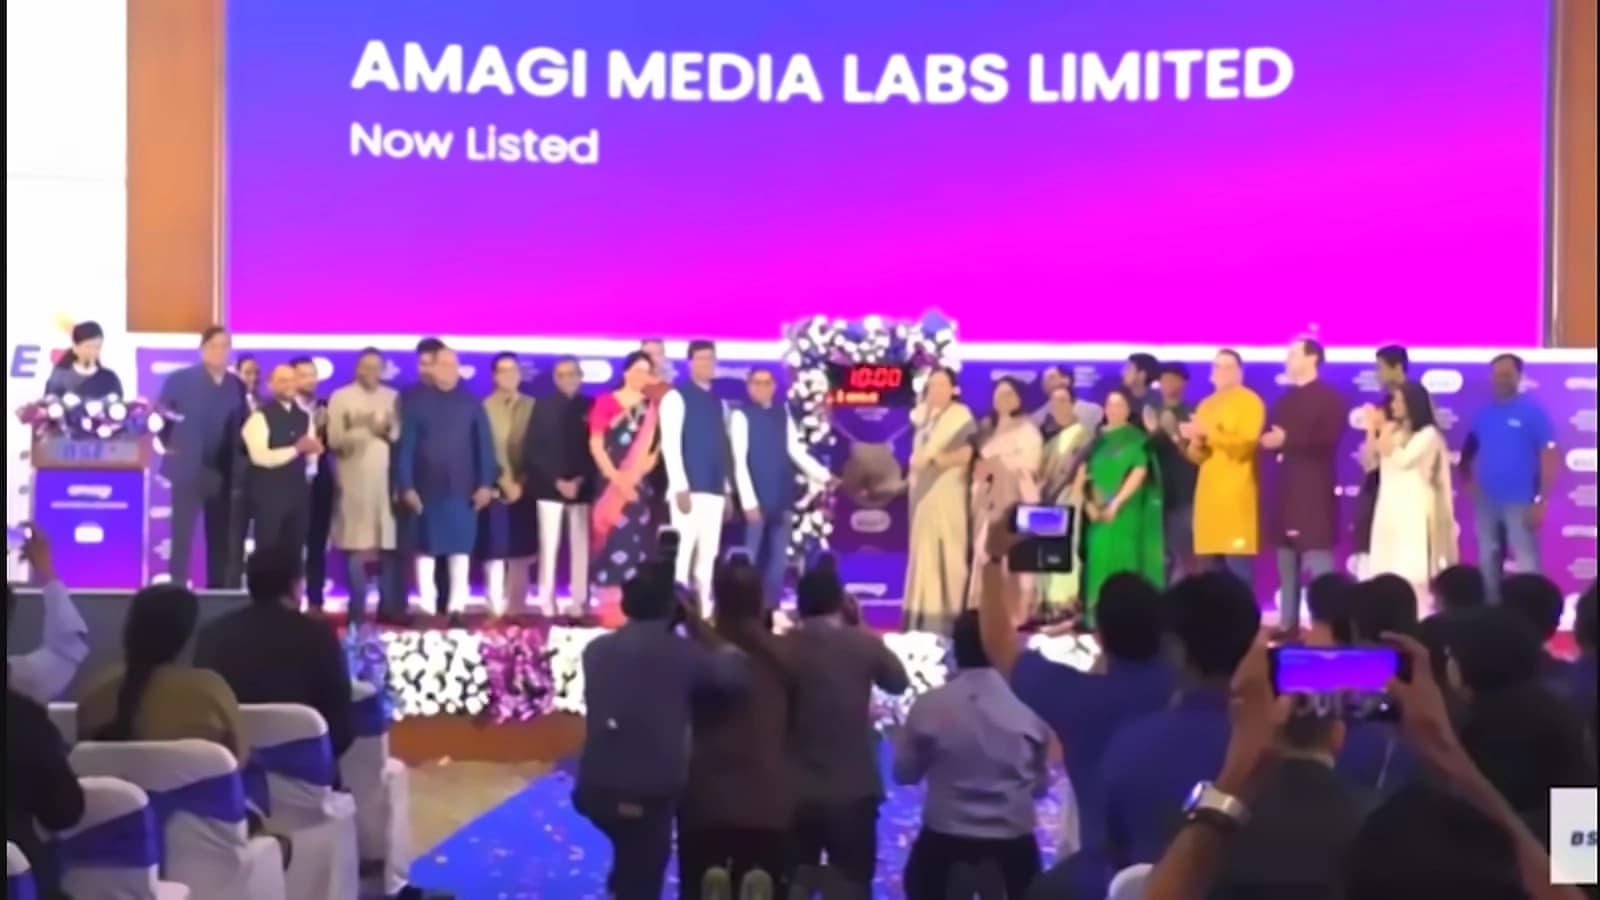
ICICI Securities has issued a buy rating on Amagi Media Labs with a target price of ₹700 in its research report dated September 06, 2026. According to the brokerage's analysis, the company is positioned as a tech enabler for the media and entertainment industry, which is now embracing technology adoption after lagging behind the curve.
Amagi's core solutions provide significant cost savings for clients, with 30-50% cost reduction achieved through cloud migration versus traditional on-premise infrastructure. As reported by ICICI Securities, the company's AI-enabled products are gaining traction and offer material savings potential through ad optimization and improved efficiency of content curation and re-framing processes.
The company demonstrates strong growth momentum with a Net Revenue Retention (NRR) of >125%, which implies >25% year-over-year revenue growth without requiring new client additions. According to ICICI Securities, this metric underscores Amagi's ability to maintain and expand its existing client relationships effectively.
ICICI Securities highlights Amagi's commitment to staying ahead of technological trends, noting that 55% of its workforce is engaged in R&D activities. This significant R&D investment demonstrates the company's focus on developing innovative solutions for the evolving media and entertainment industry.
The recommendation comes as traditional broadcast media globally faces moderating top-line growth, with management focus shifting toward bottom-line optimization. As reported by ICICI Securities, this industry transformation creates opportunities for technology-enabled solutions like Amagi's platform to gain market share and drive operational efficiency improvements across the media sector.