Emkay Global has upgraded GAIL (India) to 'buy' from 'add' with a target price of ₹200, seeing an upside potential up to 15.6% from current levels. According to Emkay Global, the brokerage firm has given the target price of ₹200, seeing an upside potential up to 15.6% based on steady core business and earnings outlook along with attractive valuations. The upgrade comes as gas transmission volumes are expected to improve quarter-on-quarter and could exceed the company's FY27 guidance of 123 mmscmd, despite the Strait of Hormuz crisis and elevated LNG prices. GAIL's gas transmission volumes are expected to improve quarter-on-quarter and could exceed the company's FY27 guidance of 123 mmscmd, with the firm building in Brent at $85/bbl though the 1HFY27 average is likely to be $100/bbl.
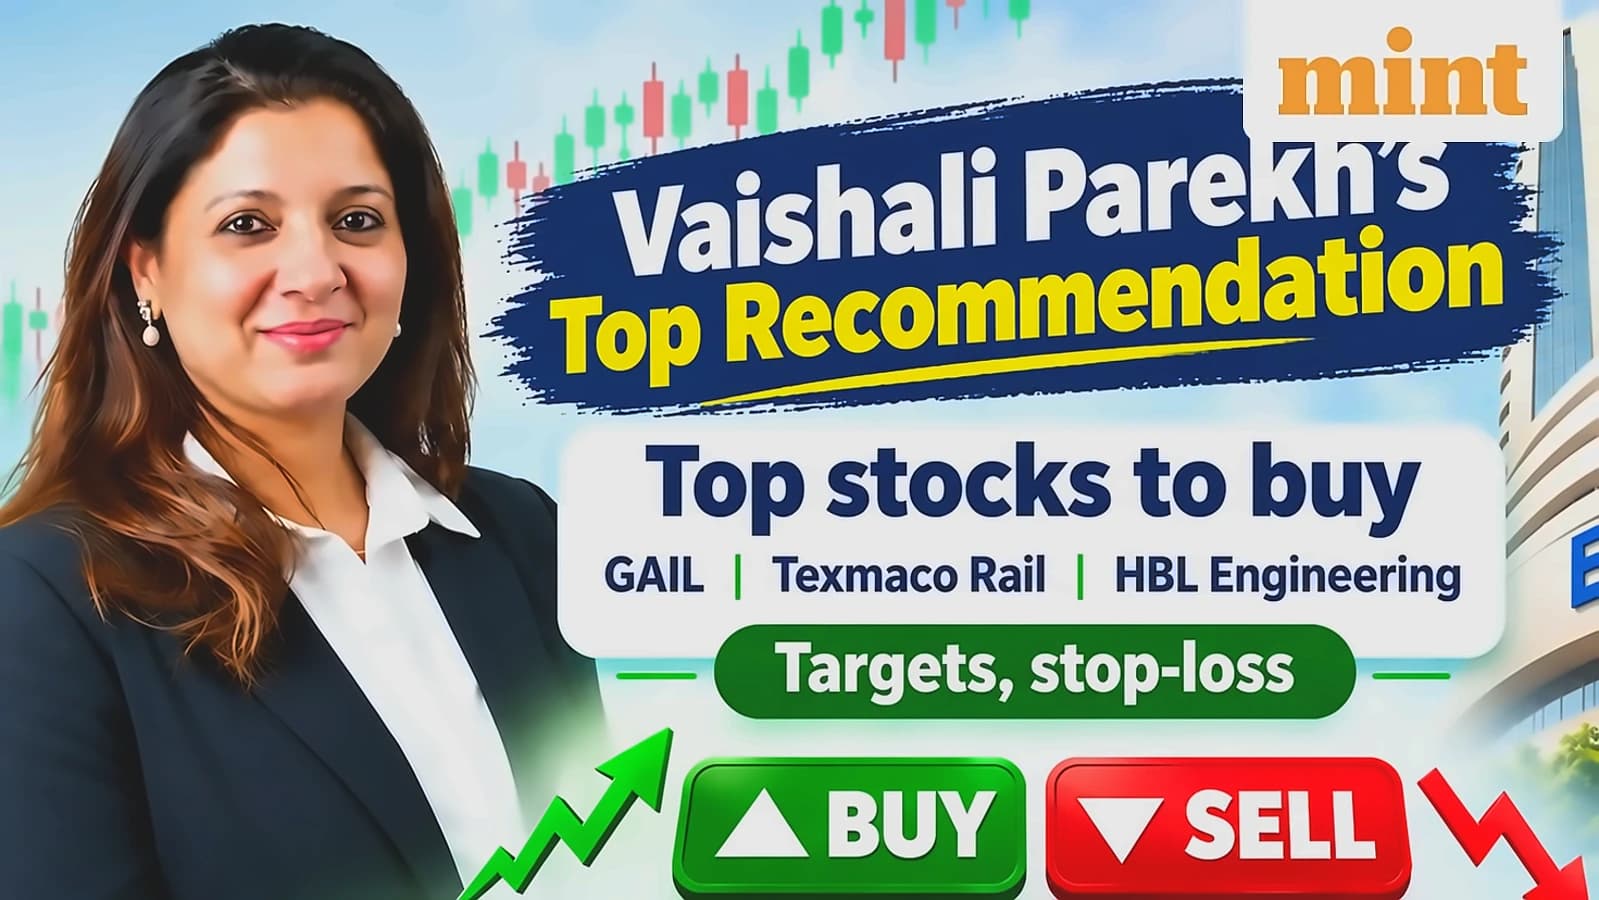
Sachin Gupta, VP – Technical Research at Choice Broking, has recommended three additional stocks for today's trading session with specific buy levels, targets, and stop-loss levels. According to Business Standard, the latest recommendations include PGIL at ₹1,320 with target ₹1,400-1,450 and stop loss ₹1,265, Hyundai at ₹2,120-2,130 with target ₹2,250-2,300 and stop loss ₹2,050, and HBL Engineering at ₹806 with target ₹850-880 and stop loss ₹760. The recommendations are based on technical patterns including breakouts from Pole & Flag patterns, bullish recovery candles, and strong momentum indicators. Vaishali Parekh, Vice President – Technical Research at Prabhudas Lilladher, has also recommended GAIL at ₹173 with target ₹182 and stop loss ₹168, Texmaco Rail at ₹126 with target ₹140 and stop loss ₹120, and HBL Engineering at ₹774 with target ₹810 and stop loss ₹750.
The Indian stock market suffered heavy losses in Thursday's trade, with Nifty 50 plunging 1.64% to settle at 25,169.50 and Sensex finishing at 73,580, down 1.67% from the previous session. As reported by LiveMint, the pain was more pronounced in the broader market, with Nifty Midcap 100 falling 2.57% and Nifty Smallcap 100 tumbling 2.25%. The market decline was attributed to surging global bond yields and volatility in crude oil prices, with investor sentiment significantly impacted by these factors. However, Nifty witnessed a rangebound session in the final hours, sustaining the important 23000 zone and indicating some revival to end in the green near 23150 level with a cautious approach maintained.
According to Parekh's analysis reported by LiveMint, the Nifty indicated a big bearish candle formation with a gap-down opening on the daily chart, closing near the 23000 zone and breaching below the previous low made near 23100 zone. The index has turned the bias and sentiment into a very tense scenario for coming sessions, with crucial support at 23000 zone and next major support zones at 22600 and 22200 levels. On the upside, 23600 level shall be the important resistance zone that needs to be breached decisively. Meanwhile, Ventura Securities notes that Texmaco Rail has recently formed higher bottoms and broken out of a symmetrical triangle, with support from higher trading volumes. For Bank Nifty, the index sustained the low made in the previous session at 55350 zone and ended in the green near 55600 level with a very cautious approach, with major support at 54500 level and crucial level at 53000 zone that needs to be sustained.
As reported by LiveMint, Bank Nifty sustained the low made in the previous session at 55350 zone and ended in the green near 55600 level with a sluggish session visible, maintaining bias with a very cautious approach and would need a significant revival from current rates. The index would have the major support at 54500 level and thereafter, the important and crucial level at 53000 zone which needs to be sustained failing which the overall trend would turn weak. A decisive move above the hurdle at 56700 level is necessary to improve the bias as of now. Support for the day is seen at 23000 levels, while resistance is seen at 23400 levels, with Bank Nifty having the daily range of 55000-56000 levels.
Texmaco Rail shares have rallied around 60% in FY27 so far, while gaining approximately 42% over the past six months, according to LiveMint. The company reported a 70.7% year-on-year increase in consolidated net profit to ₹50.07 crore for Q1 FY27, compared with ₹29.33 crore in the corresponding quarter last year. However, consolidated income declined to ₹775.20 crore in Q1 FY27, compared with ₹918.61 crore in the year-ago period. The company also reported a reduction in total expenses, which fell to ₹737.09 crore from ₹881.26 crore a year earlier. Ventura Securities expects the stock to move towards ₹165, while identifying ₹120–116 and ₹111–107 as intermediate support zones in case of a pullback, with a recommended stop-loss at ₹102.