India's cotton carry-forward stocks are projected to rise 42% to 85 lakh bales due to increased imports and duty exemptions. According to the Cotton Association of India (CAI), cotton imports in the 2025-26 season are expected to reach 60-65 lakh bales following the government's recent decision to exempt import duty. As of end-May, imports stood at 43.5 lakh bales, up nearly 32% from 33 lakh bales in the corresponding period last year. "Imports of 43.5 lakh bales had already arrived at Indian ports by the end of May. Following the recent duty exemption, we expect an additional 15 lakh bales to be imported. Total imports this season could reach 60-65 lakh bales," said Atul S Ganatra, Chairman of CAI's Crop Committee. Closing stocks for 2025-26 are projected at 85.59 lakh bales, about 25 lakh bales higher than the previous season's estimated 60 lakh bales, with the higher closing stock primarily attributed to increased imports.
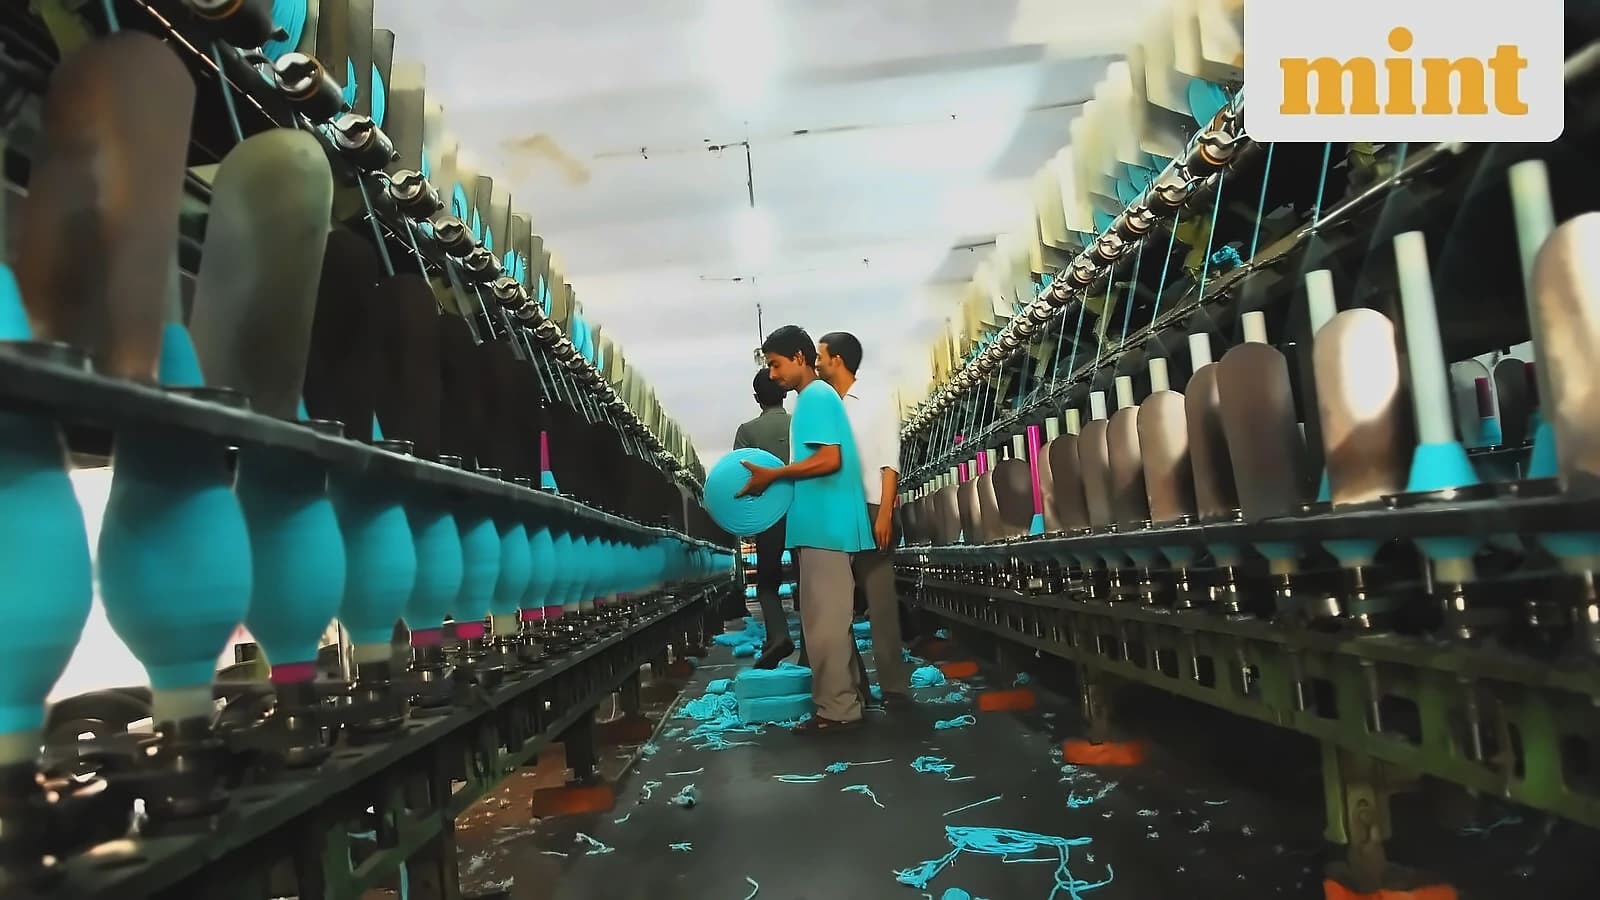
India's textile exporters received welcome relief with the government's temporary removal of the 11% import duty on cotton, valid from June 1 to October 30, 2026. According to Atul Ganatra, president of the Cotton Association of India, the move gives the industry access to cotton at more competitive global prices and helps reduce raw material costs. Cotton prices in domestic markets have dropped by almost 5% for the benchmark Shankar 6 variety from around ₹64,500 per candy to around ₹61,500 per candy, while yarn prices of the benchmark 30 count variety have fallen from ₹325 per kg to ₹310 per kg. "The biggest benefit will be for spinning mills and yarn manufacturers, as cotton is a major part of their production cost," Ganatra told Business Standard. Fabric manufacturers and integrated textile companies are also expected to gain from cheaper raw materials, with garment exporters benefiting indirectly through lower yarn and fabric prices.
Despite domestic and imported cotton being available at similar prices, textile mills continue to favour imported cotton as it delivers around 4% higher yarn realisation. According to CAI, yarn produced from imported cotton commands a premium of about ₹7 per kg in the market, making imports more attractive despite price parity. "Though domestic and imported cotton are currently available at similar prices, textile mills continue to favour imported cotton as it delivers around 4 per cent higher yarn realisation," Ganatra explained. This preference for imported cotton, combined with the duty exemption benefits, is expected to drive continued import growth and support the projected increase in carry-forward stocks.
However, traders and market players caution that the relief from duty reduction might be short-lived as global markets face multiple headwinds. "As soon as India starts importing heavily, global prices in the ICE exchange will start inching upwards. Also, worldwide there is much uncertainty over the cotton crop due to El Nino and its impact on dry weather in the US, a major producer," cautioned Gnanasekar Thiagarajan of Commtrendz Research and Fund Management Ltd. He noted that domestic prices are unlikely to continue on a downward path as there is significant uncertainty in India regarding the size of the 2026-27 domestic cotton crop if the El Nino effect is particularly harsh. The October import window design also warrants reconsideration, with traders arguing that extending duty-free imports into October risks putting downward pressure on domestic prices at a critical harvest phase.
Emkay Global Financial Services has initiated coverage on three textile sector stocks with 'Buy' ratings - Arvind with a target price of ₹700, Nitin Spinners with a target price of ₹750, and Sanathan Textiles with a target price of ₹550. According to Harsh Mittal, Research Analyst at Emkay Global Financial Services, domestic textile companies are well-positioned to absorb future shocks, supported by a robust domestic market, a favourable USD-INR exchange rate, and healthy balance sheets. The brokerage expects the coverage universe to deliver revenue, EBITDA, and adjusted profit after tax (APAT) CAGR of 21%, 34%, and 45% respectively over FY26–FY28E. Latest market data shows these stocks are positioned for significant growth as India's textile sector demonstrates resilience amid global disruptions.