Elara Securities has initiated coverage on Adani Power with an Accumulate rating and a target price of ₹220, implying an upside of around 17% from current levels, according to The Economic Times. The brokerage values the company at 12x FY29E EV/EBITDA multiple. The current market price stands at ₹189, indicating an upside potential of approximately ₹31 from the target price.
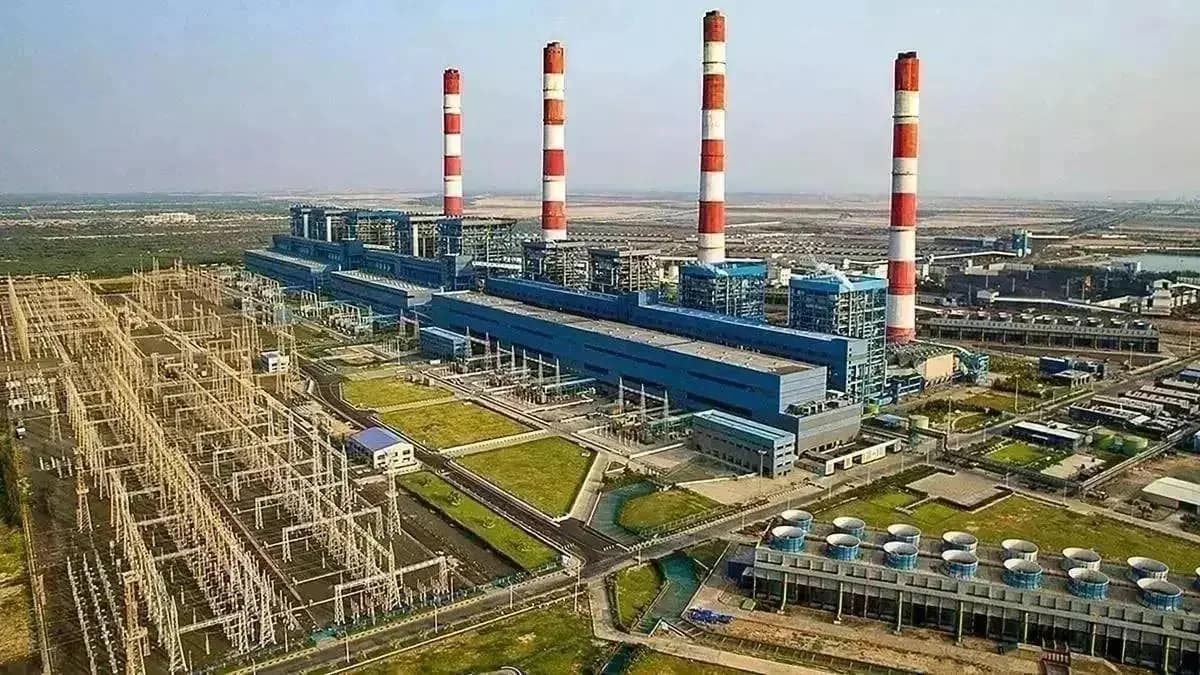
Adani Power is India's largest private thermal power generator with operating capacity of 18.3 GW across 13 assets, predominantly comprising high-efficiency supercritical and ultra-supercritical thermal plants, as reported by The Economic Times. The company is pursuing one of the sector's largest capacity expansion programmes with 24 GW of locked-in capacity that would increase its targeted portfolio to 42 GW by FY32. Around 60% of the pipeline is Brownfield, supporting faster execution and lower project costs. The expansion plans offer significant revenue visibility, with 13.3 GW of upcoming capacity backed by long-term power purchase agreements (PPAs).
According to The Economic Times, Elara expects revenue to rise to ₹82,254 crore by FY29. EBITDA is projected to grow at a compound annual growth rate of 19% between FY26 and FY29, reaching ₹33,091 crore. The brokerage projects profit after tax to reach ₹15,678 crore by FY29. Thermal power is expected to remain relevant as India's electricity demand grows and renewable energy generation fluctuates, with India's plan to add around 80 GW of coal-based capacity by FY32 supporting the demand outlook for thermal power.
As reported by The Economic Times, Elara's target price suggests that the opportunity is not without limits at the current valuation. The brokerage has flagged several execution risks including delays in commissioning new capacity, volatile coal prices and fluctuations in merchant power prices that could affect the earnings outlook. Rising debt as capital expenditure picks up is another key risk factor. While the company's experience in acquiring and turning around stressed thermal power assets could provide another avenue for growth, delivering on capacity plans and managing the cost of expansion will be critical to sustaining the brokerage's positive view.