The cement sector experiences predictable seasonal challenges during monsoon periods, with demand softening as construction activities slow. According to The Economic Times, this annual pattern creates what the market terms 'usual monsoon weakness,' leading to pressure on cement stocks. The predictability of this seasonal decline can sometimes be misleading, as underlying business fundamentals may differ from year to year despite similar surface-level market movements. As reported by The Economic Times, this seasonal pattern occurs like clockwork every year, with the monsoon arrival causing demand to soften as construction slows, creating predictable market pressure on cement stocks.
The ongoing US-Iran war in the Middle East has increased the risk of a 'higher-for-longer' cost cycle for the cement sector, particularly through Q2FY27 and Q3FY27, according to Morgan Stanley. Imported petcoke and global thermal coal prices have risen around 20% since the end of July, pointing to significant pressure on input costs. The brokerage estimates that cement companies could face ₹150-200 per tonne of power and fuel-led cost inflation cumulatively in Q2-Q3-FY27. Including other cost pressures, companies may need to raise pan-India cement prices by around ₹10-15 per bag, including GST, over the next 2-3 months to offset the impact.
The ability of cement companies to successfully implement price increases as monsoon conditions end serves as a crucial indicator of sector strength. As reported by The Economic Times, the sustainability of these price hikes over recent years demonstrates whether there is sufficient demand to help the sector manage cost pressures effectively. Price retention capacity becomes a key metric for assessing whether long-term sector fundamentals are overcoming short-term seasonal challenges. The analysis focuses on whether price increases come and stick, as this indicates strong enough demand to help the sector handle cost pressures effectively.
Despite seasonal headwinds and cost inflation risks, the cement sector presents compelling investment opportunities with nine stocks identified as having upside potential of up to 28%. According to The Economic Times, these opportunities are being highlighted through comprehensive analysis focusing on five key components: earnings, fundamentals, relative valuation, risk, and price momentum. The analysis is powered by Refinitiv's Stock Reports Plus platform, which provides detailed company analysis and standardized scoring systems for over 4,000 listed stocks.
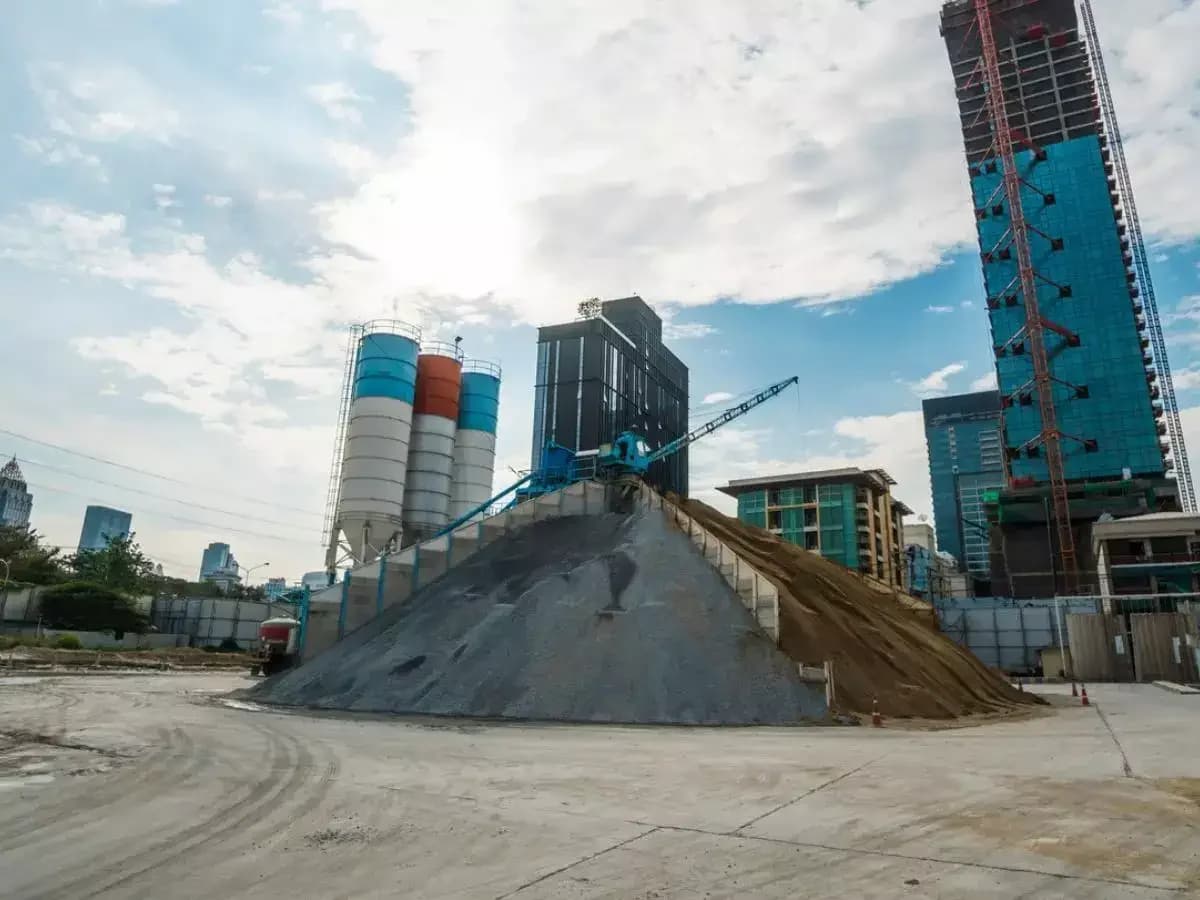
The cement sector's resilience will be determined by how effectively companies navigate the current monsoon period while maintaining pricing power and managing cost inflation risks. As reported by The Economic Times, sustained pricing power after the monsoon and festive season will be crucial for margin protection. If demand remains resilient and companies are able to push through price hikes, margins could be protected. However, Morgan Stanley warns of potential earnings estimate downgrades and continued margin pressure in Q3FY27 if demand weakens or pricing power fails. The brokerage notes that cumulative rainfall was around 15% below the long-term average as of September 20, with potential impact on agricultural activity and rural cement demand likely to emerge with a lag, particularly affecting Q4FY27 and Q1FY28.