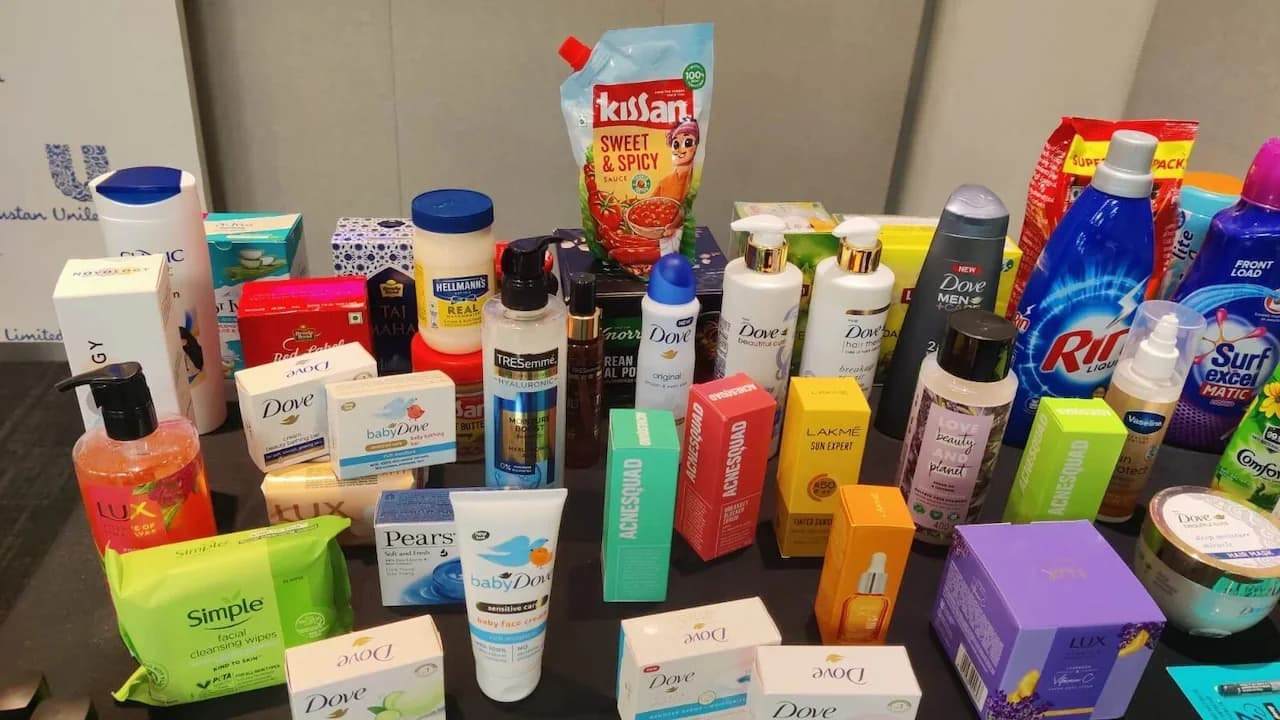
Hindustan Unilever (HUL) shares surged 3% to ₹1,864 on Thursday, following robust second quarter earnings that exceeded analyst expectations. The stock opened at ₹1,812.80 and surged to a session high of ₹1,864, recovering from a fresh 52-week low of ₹1,758.20 hit on Monday, October 27. According to The Economic Times, the company delivered Q2 consolidated volume and sales growth of 7% and 15% respectively, surpassing estimates of 5% and 11% respectively. UBS has emerged as the most bullish with a target price of ₹2,700, implying nearly 49% upside from Wednesday's closing price of ₹1,815.80, as reported by Moneycontrol. Jefferies and HSBC both retained 'Buy' ratings with significant upside potential, as reported by CNBC TV18. Jefferies maintains a 'buy' rating with a target price of ₹2,350, indicating an upside of 29.4% from the previous closing price of ₹1,815.8. HSBC maintained its Buy rating and marginally raised the target to ₹2,220 from ₹2,210, while Morgan Stanley retained its Equal-weight rating with a target price of ₹2,480. The strong quarterly performance demonstrates the company's ability to navigate inflationary pressures through strategic pricing and operational efficiency.
HUL reported a 14.5% year-on-year increase in revenue to ₹18,226 crore for the September quarter, marking its strongest revenue growth in 14 quarters, according to CNBC TV18 data. Underlying volume growth stood at 7%, at the upper end of analysts' expectations of 6-7%. Net profit stood at ₹2,790 crore, marking a 4% increase from ₹2,685 crore in the corresponding quarter last year, as reported by The Economic Times. EBITDA stood at ₹4,089 crore, marginally exceeding estimates, though operating margin contracted 140 basis points year-on-year to 22.4%. The company's market capitalisation stood at ₹4.28 lakh crore as of Thursday's trading session. HUL's management said underlying demand remained resilient but cautioned that commodity inflation was expected to persist in the short term. The company maintained its EBITDA margin guidance of 22-24% despite current pressures. The board also declared an interim dividend of ₹19 per share, with a record date of November 12, as reported by The Hindu BusinessLine.
According to NDTV Profit, HUL's underlying sales growth reached 15%, the highest in 14 quarters, with underlying volume growth rising to 7% in the September quarter, its highest since the first quarter of FY22. The company attributed this strong performance to calibrated pricing actions, market-development initiatives, product innovation and stronger distribution as key elements of its strategy. Home care growth reached 22%, beauty and wellbeing sales grew 16%, and earnings before interest, taxes, depreciation, and amortisation (EBITDA) stood at ₹4,089 crore with 8% growth. Net profit stood at ₹2,796 crore with 8.7% growth. The year-ago period included a one-off gain of ₹273 crore from the resolution of prior years' tax matters, while in the September 2026 quarter, exceptional items included a ₹2 crore gain from the disposal of surplus assets. CEO Priya Nair noted that the performance reflected the company's focus on building brands and strengthening distribution.
Motilal Oswal reiterated a Buy rating with a target price of ₹2,150, noting the 7% underlying volume growth as a positive but flagging Home Care margin pressure as a concern, with gross margin contracting 400 basis points year-on-year to 47.6%, as reported by The Hindu BusinessLine. JM Financial also retained a Buy with a revised target of ₹2,225, cutting its target P/E to 40x from 45x, citing the broader sector de-rating. However, Nomura was more cautious, cutting its target price to ₹2,100 from ₹2,450, implying an upside of 16% from current levels, as reported by The Economic Times. Elara Securities was more cautious, maintaining an Accumulate with a trimmed target of ₹2,100, down from ₹2,230, pointing to limited earnings visibility beyond the second half of FY27. Trading volumes stood at 11.18 lakh shares worth ₹206 crore, with sell orders still outpacing buy orders at 56.50% versus 43.50%, indicating some caution persists in the market. At the current price, the stock trades at a symbol P/E of 28.30, well below its 52-week high of ₹2,526 touched on October 28, 2025.
Of the 42 analysts covering HUL stock, 30 have 'buy' ratings, nine have 'hold' ratings, and three have 'sell' ratings, according to CNBC TV18. The stock was trading at ₹1,827, up 0.6% in early morning trade on Thursday, as reported by Moneycontrol. The gains came amid a positive broader market, with Sensex up 169.61 points (0.23%) at 73,415.64 and Nifty gaining 39.95 points (0.18%) to trade at 22,738.80 at 9:36 am. The stock has declined 21.6% so far in 2026, compared with a 13.2% fall in the Nifty 50. The positive analyst sentiment reflects confidence in HUL's ability to manage inflationary pressures while maintaining volume growth. HSBC maintained its Buy rating and raised the target to ₹2,220 from ₹2,210, while PL Capital upgraded HUL to Buy from Accumulate but cut the target to ₹2,268 from ₹2,326. The latest quarterly results show Q2 underlying sales growth of 15% with volume growth at 7%, though EBITDA margin contracted 140 bps YoY to 22.4% due to inflation pressures.