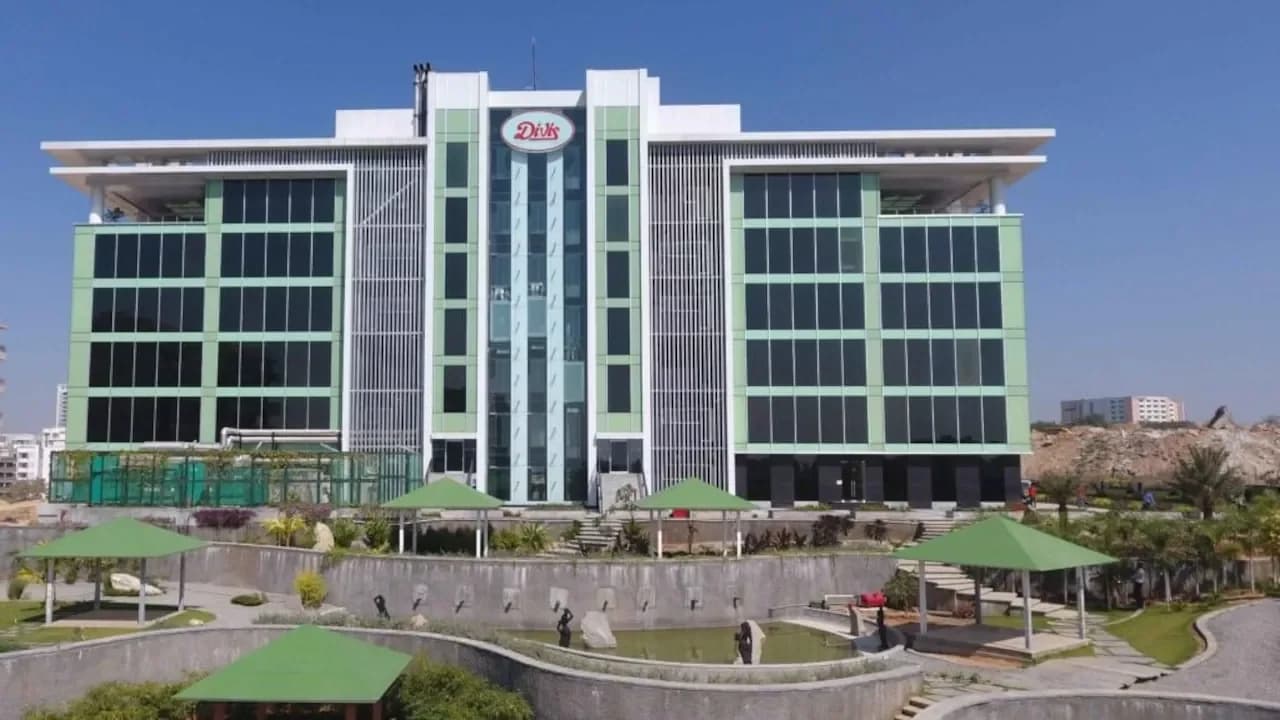
Divi's Laboratories shares surged to a fresh 52-week high after strong Q2 FY27 results and positive broker commentary. The stock opened at ₹11,105 on BSE and touched an intraday high of ₹11,818 per share, marking the second consecutive session at record levels. The pharmaceutical company's consolidated net profit jumped nearly 64% year-on-year to ₹1,127 crore in Q2 FY27, while revenue from operations increased over 35% YoY to ₹3,676 crore. The stock has surged 84% so far in 2026, demonstrating strong investor confidence in the company's growth prospects.
According to latest reports, Divi's Laboratories delivered exceptional Q2 FY27 results with net profit rising 64% year-on-year to ₹1,127 crore and revenue growing 35% to ₹3,676 crore. The company reported a foreign exchange gain of ₹24 crore during the quarter, compared with ₹63 crore in the year-ago period. The custom synthesis business was the key growth driver, recording 54% YoY expansion against Goldman Sachs' estimate of 34%, while the generics segment also performed better than expected, growing 12% against the brokerage's forecast of 4%. The EBITDA margin expanded by 989 basis points year-on-year to 42.6%, surpassing Goldman Sachs' estimate by 535 basis points.
Following the strong quarterly performance, several brokerages have turned more positive on Divi's Laboratories. Goldman Sachs maintained its 'Buy' rating and raised the target price to ₹11,700 from ₹10,225, with the brokerage raising FY27-FY29 earnings per share estimates by up to 17%. JPMorgan maintained its 'Overweight' rating and raised the target price to ₹12,500 from ₹9,100, expecting 37% EPS CAGR through FY29. Nuvama Institutional Equities maintained its 'Buy' rating and increased the target price to ₹12,000 from ₹9,600, citing the company's promising opportunity in peptide manufacturing with installation of 3,000-litre solid-phase peptide synthesis lines. However, Motilal Oswal Financial Services maintained a 'Neutral' rating at ₹11,110, noting that the stock's current valuation leaves limited room for further upside despite raising earnings estimates by 21% for FY27 and 19% for FY28.
The brokerages highlighted significant growth potential in Divi's Laboratories custom synthesis and peptides businesses. JPMorgan expects the transition of projects from validation stage to commercial production to emerge as a key growth driver, with one programme nearing commercialisation and two expected to advance over the next few quarters. The company is targeting a position among the world's top three integrated peptide manufacturers through multi-tonne capacity expansion. Motilal Oswal believes Divi's is well-positioned to secure business from large innovator customers supported by scientific capabilities across peptides, contrast media and generics. The company's EBITDA margin expansion of 989 basis points to 42.6% was driven by favourable business mix, higher custom synthesis contribution, and operating leverage benefits.
According to technical analysis from SAHI, Divi's Laboratories is witnessing a strong continuation breakout and trading at an all-time high. The stock had earlier broken out of a broadening wedge pattern and ₹11,800 is the immediate resistance level to watch, while trailing support is placed around ₹11,200. Gaurav Arora from SAHI noted that the technical structure remains strong as long as the stock holds above this support level. The broader market sentiment reflects positive momentum across multiple sectors, with MCX, Shyam Metalics, JSW Steel, South Indian Bank, Marico, Divi's Laboratories, Navin Fluorine International and Motilal Oswal Financial Services having scaled their 52-week peaks, indicating strong investor interest across these sectors.