According to reports from LiveMint, Axis Securities believes India's diagnostics sector is entering a multi-year growth upcycle, supported by rising demand, scalable models and strong cash generation. The brokerage highlighted that the sector offers a compelling multi-year investment opportunity, citing structural demand visibility, scalable business models, strong cash generation, and improving returns. The firm believes the sector is entering a secular upcycle, with improving utilization, stronger cash conversion, and disciplined expansion creating an attractive combination of growth and quality.
As reported by LiveMint, Axis Securities has assigned a 'buy' recommendation to Dr Lal PathLabs with a target price of ₹2,315 per share, implying 20% upside from the current market price of ₹1,934. The brokerage highlighted that the company combines a pan-India hub-and-spoke network with a strong B2C franchise, which contributes more than 70% of revenue and provides direct access to a large and diversified patient base. The company's National Reference Laboratory in New Delhi anchors the network and supports high-complexity testing, while its extensive retail presence provides scale and brand recall. The brokerage emphasized that the company's zero-net-debt balance sheet, strong operating cash flow generation, and healthy EBITDA margins of around 26%–27% further strengthen the investment case.
According to LiveMint, Axis Securities also assigned a 'buy' rating to Vijaya Diagnostic Centre with a target price of ₹1,730 per share, implying 20% upside potential from the CMP of ₹1,437. The brokerage noted that Vijaya stands out through its integrated B2C model, combining pathology with high-end radiology services such as MRI, CT, and PET-CT under one roof. With more than 140 centers and a strong leadership position in South India, the company benefits from higher customer convenience, cross-selling opportunities, and strong patient stickiness. The brokerage highlighted that the company's differentiated integrated model has translated into best-in-class EBITDA margins of around 39%–40%, demonstrating the strength of its operating economics.
As reported by LiveMint, for Nephrocare Health Services, Axis Securities has given a 'buy' rating with a target price of ₹750 per share, implying 21% upside potential from the CMP of ₹616. The brokerage highlighted that Nephrocare is India's and Asia's largest specialized dialysis service provider, with 490 clinics across 269 cities spanning India, the Philippines, Uzbekistan, and Nepal. The company's diversified expansion model across captive hospital units, public-private partnership (PPP) contracts, and standalone centers provides multiple growth avenues while reducing dependence on any single format. The brokerage noted that the company's strong execution, with revenue from operations growing at a 31.5% CAGR to ₹756 crore in FY25, alongside a healthy EBITDA margin of 22.1% and an impressive operating cash flow (OCF)-to-EBITDA conversion of 81.2%. According to TradingView News, Axis Direct has set a target price of ₹750 for Nephrocare Health Services, also known as NephroPlus, with the company operating 255 captive hospital clinics, 176 public-private partnership (PPP) clinics and 59 standalone facilities.
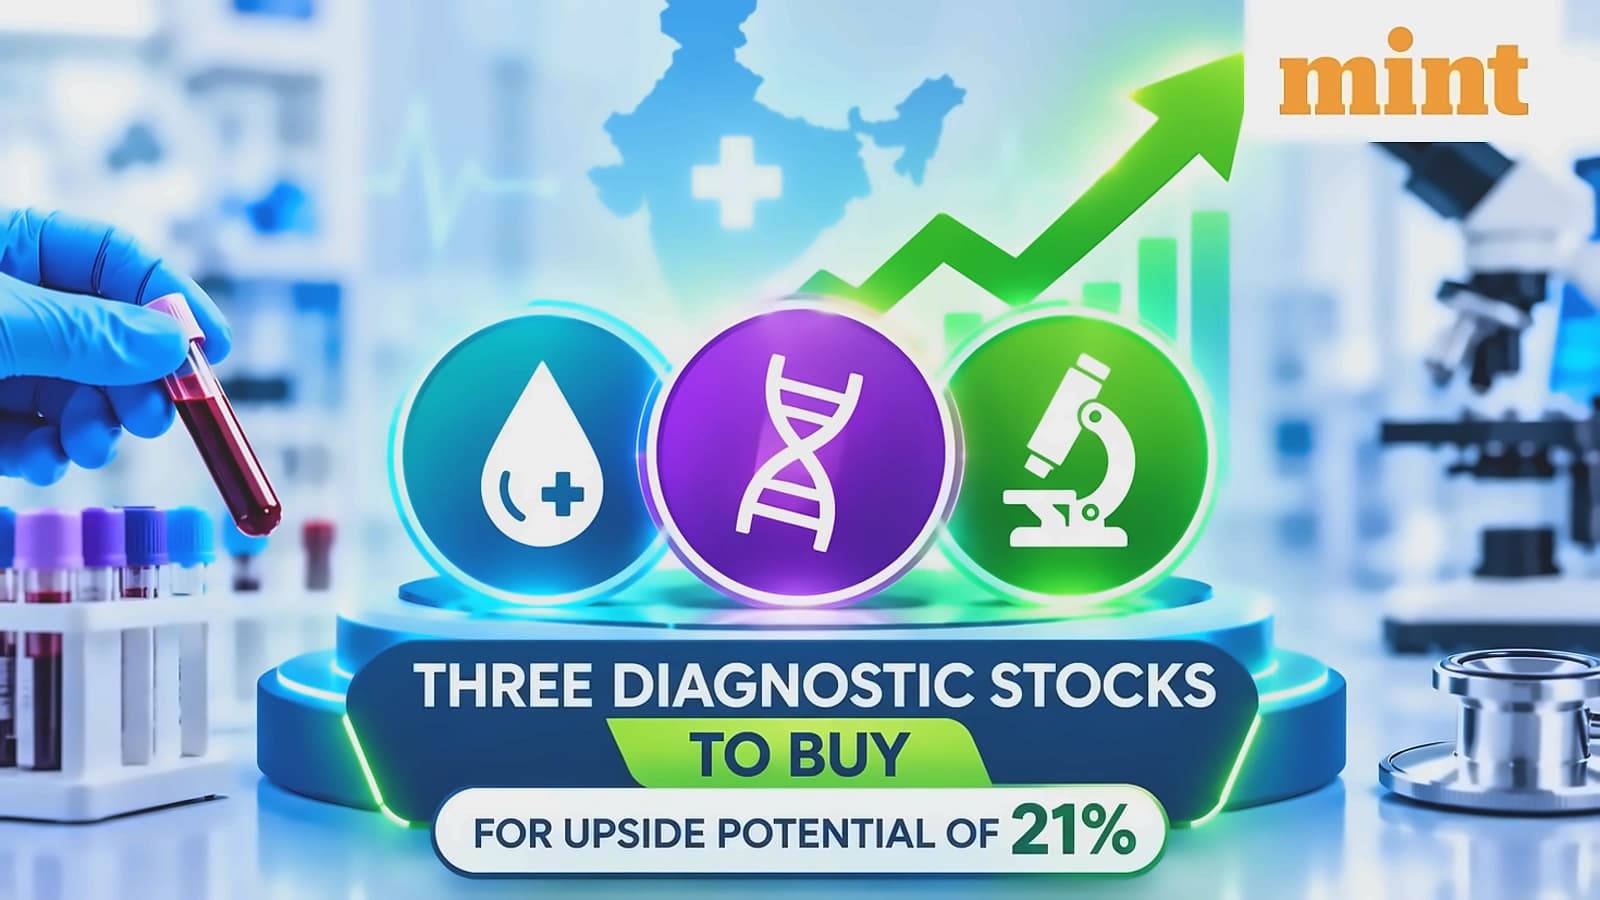
As reported by TradingView News, Axis Direct estimates India's diagnostic services market, valued at ₹86,000-87,000 crore in FY24, will grow at a CAGR of 10%-12% to ₹1,27,500-1,37,500 crore by FY28. The brokerage identified rising chronic disease incidence, greater awareness of early detection, a shift towards accredited organised providers and expanding government healthcare schemes and private health insurance penetration as key growth drivers. The specialized renal care and dialysis segment is projected to expand at a 19.3% CAGR to around $198 crore by 2029. The brokerage highlighted that improving cash generation and capital efficiency across the sector, with operating cash flow-to-EBITDA ratio reaching 70%-80% or more, while return on capital employed continues to improve alongside minimal net leverage, supports valuations for organized healthcare and diagnostic companies.