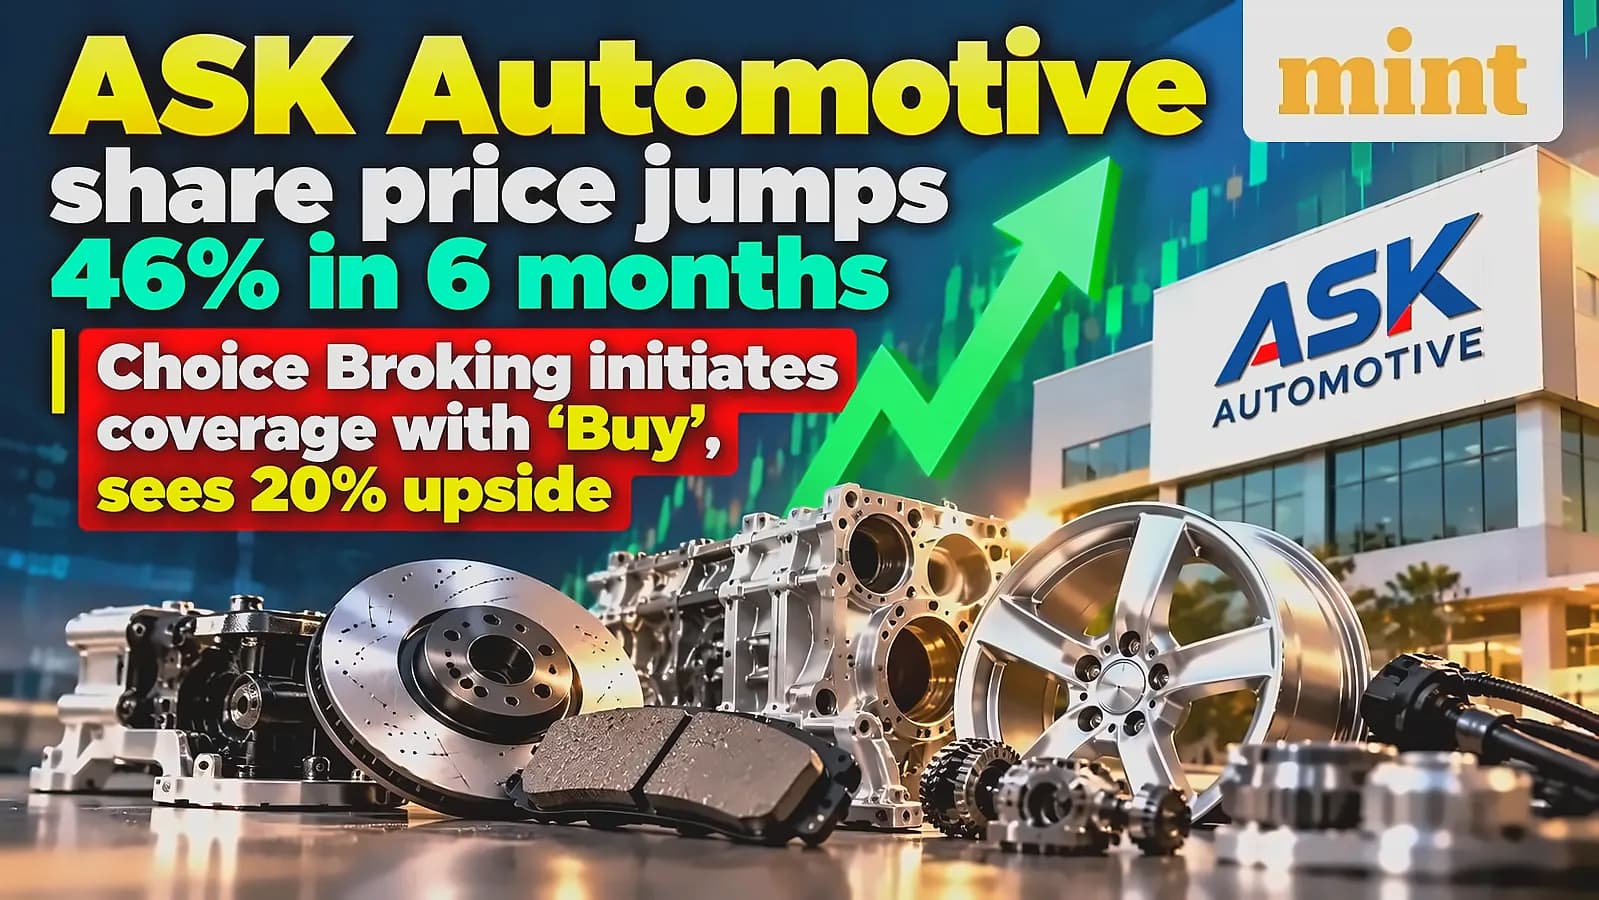
ASK Automotive shares have demonstrated impressive market performance, rising 46% over the past six months and gaining 32.14% year-to-date. According to reports from LiveMint, Choice Institutional Equities has initiated coverage with a 'Buy' rating and target price of ₹730, implying an upside of around 20.3% from the current market price of ₹608. The brokerage values the stock at 30x its average estimated earnings for FY28–FY29. As per Choice Institutional Equities, the company has consistently outpaced two-wheeler industry growth with a consolidated revenue/EBITDA/PAT CAGR of ~20%/~33%/~37% respectively over FY22–FY26, driven by capacity per vehicle gains and product mix across ALPS and ABS segments.
Choice Institutional Equities expects Aluminium Lightweighting Precision Solutions (ALPS) to become ASK Automotive's biggest growth engine, with ALPS' contribution to revenue increasing from 51% in FY26 to 62% by FY29E. As reported by LiveMint, the growth is expected to be driven by increasing aluminium content per vehicle and higher wallet share with original equipment manufacturers (OEMs). The brokerage estimates ALPS will achieve a CAGR of around 26% during the period, with electric vehicles typically using 30–50% more aluminium than internal combustion engine vehicles, creating a structural opportunity for the company. Choice Institutional Equities notes that aluminium lightweighting improves fuel efficiency and reduces vehicle weight, while ASKAUTO's powertrain-agnostic portfolio and established OEM relationships position it to capture this shift.
ASK Automotive's core braking business remains an important growth pillar, with the company being India's largest manufacturer of two-wheeler brake shoes and advanced braking systems (ABS), holding an estimated 50% OEM market share. According to LiveMint, the braking segment contributed around 37% of FY26 revenue and is expected to grow at approximately 11% CAGR between FY26 and FY29E. The company is expanding its brake-shoe and disc-pad capacity from 260 million to 320 million units, with capacity utilisation at around 90%. As per Choice Institutional Equities, this transition towards higher-value braking products, alongside ~90% utilisation and continued capacity expansion at Bangalore and Karoli, should support sustained growth and strengthen the franchise despite a gradually changing two-wheeler product mix.
Beyond braking and ALPS, ASK Automotive is expanding across exports, aftermarket, passenger-vehicle components and safety-control cables. As reported by LiveMint, the aftermarket business, supported by a network of more than 450 dealers, recorded a 21% CAGR between FY24 and FY26. The company is also entering the high-pressure die-casting (HPDC) alloy-wheel segment through technical collaborations with Taiwan-based LIOHO and Japan's Kyushu Yanagawa, with Choice Institutional Equities expecting this business to generate around ₹2,500 crore, or 4% of total revenue, by FY28E. Additionally, new product opportunities through a joint venture with AISIN and T.D. Holding in sunroof cables provide additional growth avenues.
Choice Institutional Equities expects ASK Automotive to deliver approximately 18% revenue CAGR, 20% EBITDA CAGR and 20% PAT CAGR between FY26 and FY29E. According to LiveMint, the company reported FY26 ROE and ROCE of 25.3% and 25.4% respectively, with the management targeting 20% export CAGR between FY26 and FY29E. The exit from the low-margin Wheel Assembly business is expected to provide around 80 basis points of structural improvement in EBITDA margins. As per Choice Institutional Equities, the company's experienced, promoter-led management, industry-leading return ratios, and financial track record that has consistently outpaced two-wheeler average industry growth support the positive outlook.