The Securities and Exchange Board of India has proposed allowing third parties, including employers or mutual fund companies, to pay for investments on behalf of individuals. According to SEBI's consultation paper, the current regulatory framework mandates that all payments for mutual fund investments must originate directly from the investor's own bank account and be routed exclusively through RBI-authorised payment aggregators or SEBI-recognised clearing corporations. To mitigate third-party payment risks, asset management companies must ensure compliance with Prevention of Money Laundering Act, verify that source bank accounts belong to unit-holders, and use payment modes with independent traceability. The proposal, issued on May 20, 2026, is currently open for public comments until June 10, 2026, with final rules expected to take effect 30 days after issuance.
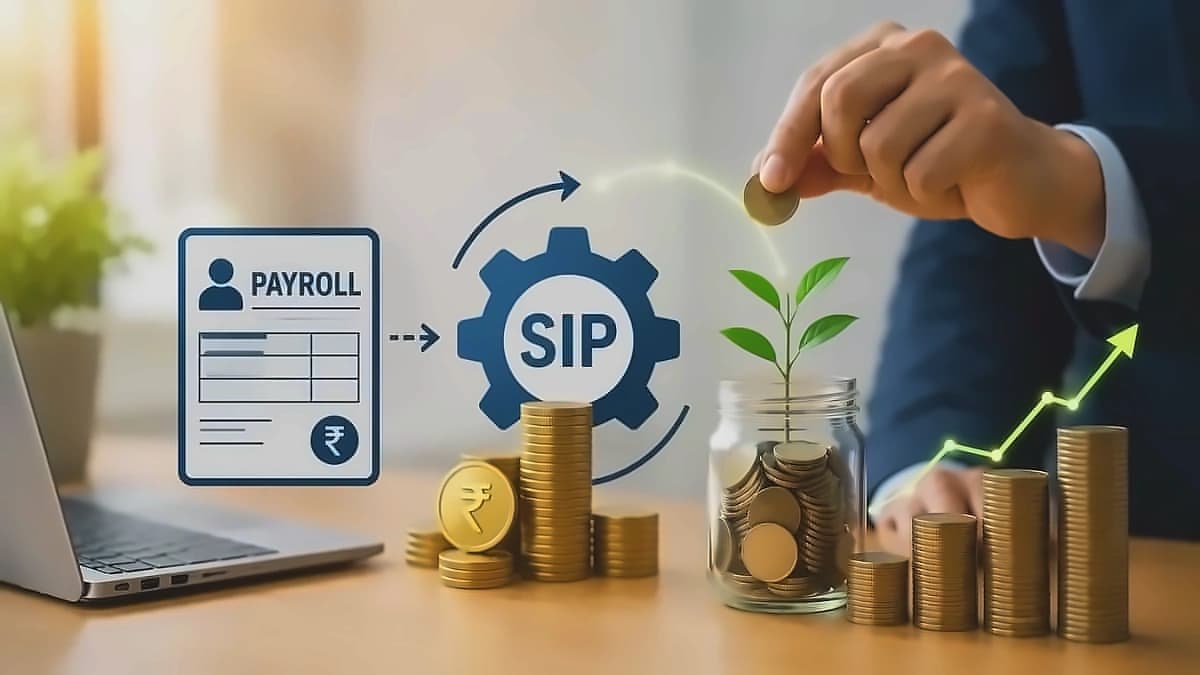
SEBI's proposal introduces a revolutionary concept where salaried employees may voluntarily choose to have mutual fund SIP contributions deducted directly from salary through employers. This mechanism could fundamentally alter India's investing discipline by moving investments before lifestyle spending begins. As reported by SEBI, this facility would be available to all listed and EPFO registered companies and asset management companies, with only interested employees opting for such arrangements. The draft requires KYC verification of both payer and beneficiary, a clear written mandate from the investor, and non-cash, electronic, auditable money trail through segregated accounts. The proposal leverages the same psychology that makes EPF contributions automatic - by keeping investment money separate from spending accounts, it could reduce emotional decision-making and improve long-term participation rates.
Currently, employees are indirectly investing in equity markets through EPFO contribution, with the EPFO authorised to invest up to 15% of its fresh accretions into equities through exchange traded funds tracking Nifty50 and S&P BSE Sensex, as well as specific CPSE ETFs for government disinvestments. According to SEBI, the EPFO has invested over ₹3 lakh crore in equities. Similarly, the National Pension System invests in market-linked retirement schemes, managing ₹14.44 lakh crore at the end of 2024-24, with it being mandatory for Central government employees joined from 2004 and voluntarily adoptable by corporates.
SEBI is considering multiple additional features beyond employer-led investments. The proposal includes allowing fund houses to pay part of a distributor's commission as mutual fund units instead of cash, applying only to distributors registered with AMFI who sell AMC's schemes. Additionally, SEBI is considering letting investors redirect part of their subscription, redemption, dividend, or returns toward social causes through Zero Coupon Zero Principal (ZCZP) instruments or directly to NGOs named in scheme documents. Two models are proposed: a dedicated social-cause mutual fund scheme or a donation facility built into existing schemes. These features aim to encourage long-term distributor investment and provide investors with opportunities to combine investing with charitable giving.
The proposal could establish an ecosystem comparable to the US 401(k) framework, fundamentally changing how salaried India builds wealth through automated investing discipline. For employees, the proposal could simplify mutual fund investment by allowing automatic salary deductions, potentially encouraging disciplined investment behaviour and reducing the common mistake of treating investments as optional. This system could promote savings practices beyond traditional bank accounts, potentially extending to contractors and smaller companies in the future. SEBI's initiative aims to integrate investing into everyday financial activities, such as payroll savings, while retaining safeguards against misuse. The proposal specifically addresses conflict-of-interest concerns, with SEBI flagging potential issues such as employers steering employees toward group company schemes and distributors receiving commission in fund units potentially influencing recommendations.