Eurozone government bond yields rose sharply on Thursday as higher energy prices reinforced expectations of tighter monetary policy, with investors continuing to sell debt of heavily indebted countries such as France and Italy, according to Reuters. The renewed selling came amid a global bond market rout driven by growing expectations of central bank rate hikes and concerns over elevated government debt burdens. Brent crude rose about 3% to $103 a barrel, near its highest level in a week, as geopolitical tensions involving Iran, Israel, Saudi Arabia and Yemen added to concerns over energy supplies. The rise in oil prices has intensified worries that inflation could remain elevated, potentially limiting the scope for central banks to ease monetary policy or increasing the likelihood of further rate increases.
France has been at the centre of the selloff as the government struggles to contain a budget deficit of more than 5% of gross domestic product, with the deterioration in investor sentiment pushing the premium demanded to hold French debt over German bonds to levels last seen during the euro zone debt crisis. France's 10-year bond yield rose 6 basis points to 4.931% on Thursday, approaching the 24-year high of 4.994% reached last Friday, while the spread between French and German 10-year yields widened 4 basis points to 142 basis points. It had climbed to nearly 160 basis points last week, its highest level since 2012. Germany's benchmark 10-year bond yield rose 2 basis points to 3.504%, with German government bonds benefiting from their safe-haven status during this week's market turbulence.
Eurozone business activity expanded at its fastest pace in nearly 3-1/2 years in September, driven by strong service demand and AI investments, according to Reuters. The S&P Global Eurozone Services Purchasing Managers' Index rose to 53.0 in September from 51.6 in August, marking its highest level in 10 months and matching its preliminary reading. The composite PMI, which combines services and manufacturing, climbed to 53.1 from 52.0, reaching its highest level since April 2023 and the strongest quarterly performance for the eurozone since the second quarter of 2022. IT-related services were among the strongest areas of growth, supported by increased investment in artificial intelligence as well as continued expansion in professional and commercial services. Spain remained the strongest-performing major economy in the survey, followed by Ireland, while Germany's recovery also accelerated, reaching one of its strongest rates since early 2022. However, the improvement in activity did not translate into comparable employment growth, with a slowdown in services-sector hiring offsetting modest factory job creation.
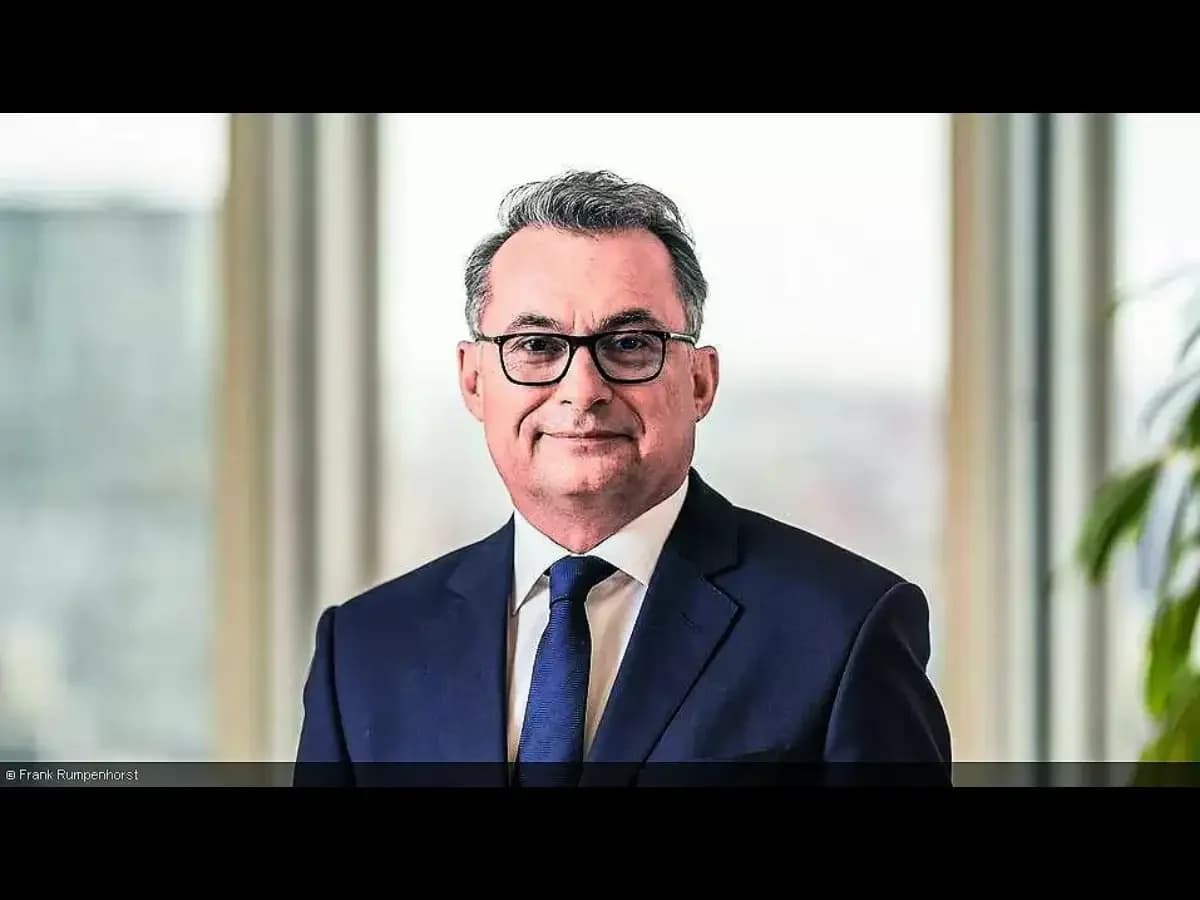
ECB policymaker Olli Rehn stated that eurozone energy inflation has not yet spread broadly to other goods and services, according to Reuters. This represents a significant development as it suggests that the current inflation surge, driven largely by soaring energy costs, may not spill over into broader price pressures across the economy. Rehn highlighted that rising bond yields were contributing to slower economic growth and reducing the extent to which higher energy costs were being passed through to consumer prices and wages. The ECB Chief Economist Philip Lane has similarly pointed to the potential impact of tighter financial conditions on inflation, while ECB board member Isabel Schnabel warned that the economy could react more strongly to higher borrowing costs than previously expected. Eurozone government bond yields have climbed to their highest levels in more than a decade, driven partly by rising U.S. Treasury yields and growing concerns over debt sustainability in some European countries. Rehn maintained the ECB's approach of avoiding forward guidance on interest-rate decisions.
Eurozone inflation currently stands at 3.8%, nearly double the European Central Bank's 2% target, according to reports from Reuters. The increase has been driven largely by soaring energy costs, with the survey highlighting renewed price pressures across the eurozone. Both input costs and prices charged by businesses increased at their fastest pace in four months. Despite these elevated levels, Rehn's comments suggest that opposing economic forces could help contain further price pressures. Financial markets currently expect another two to three rate increases during the current tightening cycle, with an around 80% probability of a hike by December. The combination of stronger-than-expected economic activity, rising energy costs and accelerating price pressures is creating a complex policy environment for European policymakers, with markets pricing in more than two ECB interest-rate increases by the middle of next year.