
Indian benchmark indices experienced a sharp sell-off on March 2, 2026, with the BSE Sensex plunging over 1,000 points (1.3%) to 80,226 and the NSE Nifty 50 slipping to 24,837, breaching the key psychological 25,000 level in opening minutes. The sell-off was driven by a 10% surge in Brent crude to $78.52 per barrel following strikes in the Middle East, sparking a broad risk-off sentiment that sent the India VIX up 17.7% to 16.13, reflecting sharp rise in market fear. Market breadth was heavily negative, with 2,551 shares declining against just 363 advances on the NSE, while broader markets followed suit with the BSE MidCap falling 1.06% and SmallCap index dropping 1.64%. The decline comes after heightened geopolitical tensions over the weekend, specifically following strikes in Iran, which raised concerns about energy supply disruptions.
Persistent selling by Foreign Institutional Investors (FIIs) continues to weigh on Indian markets, with FIIs offloading Indian stocks worth ₹7,536 crore on the last trading day of February, according to Mint. Even though Domestic Institutional Investors (DIIs) stepped in to buy shares worth ₹12,293 crore, their efforts weren't enough to stem the tide—FIIs finished February as net sellers, marking their eighth consecutive month of outflows since July 2025. Over the month, FIIs sold a net ₹6,640 crore in the cash segment. On Monday alone, FPIs sold nearly ₹3,230 crore worth of equities, according to provision data from the National Stock Exchange. This steady FII exodus is attributed to the Bank of Japan's decision to raise interest rates to 2.50% after 17 years, ending its era of negative rates. The move is expected to increase demand for Japanese treasury bonds and disrupt the so-called cash carry system that FIIs have long relied upon, resulting in higher funding costs for foreign investors.
The immediate trigger was a sharp rally in global crude oil prices, with Brent crude surging 10% to $78.52 per barrel amid fears of traffic halts in the Strait of Hormuz, a key chokepoint for global oil flows. Some early spikes even hit $80+ per barrel, adding to market anxiety. For India, higher oil prices directly translate into: inflationary pressure from higher input costs for transport and manufacturing, potential widening of the trade deficit, and rupee weakness. The Indian Rupee weakened to approximately 91.35 per USD as geopolitical tensions escalated. India imports roughly 85% of its crude oil requirements, with about 46% sourced from Saudi Arabia, Iraq, the United Arab Emirates and Kuwait—a region now embroiled in the current conflict. Devarsh Vakil, head of prime research at HDFC Securities, noted that paints, lubricants, aviation and chemical companies, where crude-linked inputs account for an estimated 40-70% of total raw material costs, would bear the brunt of the latest shock.
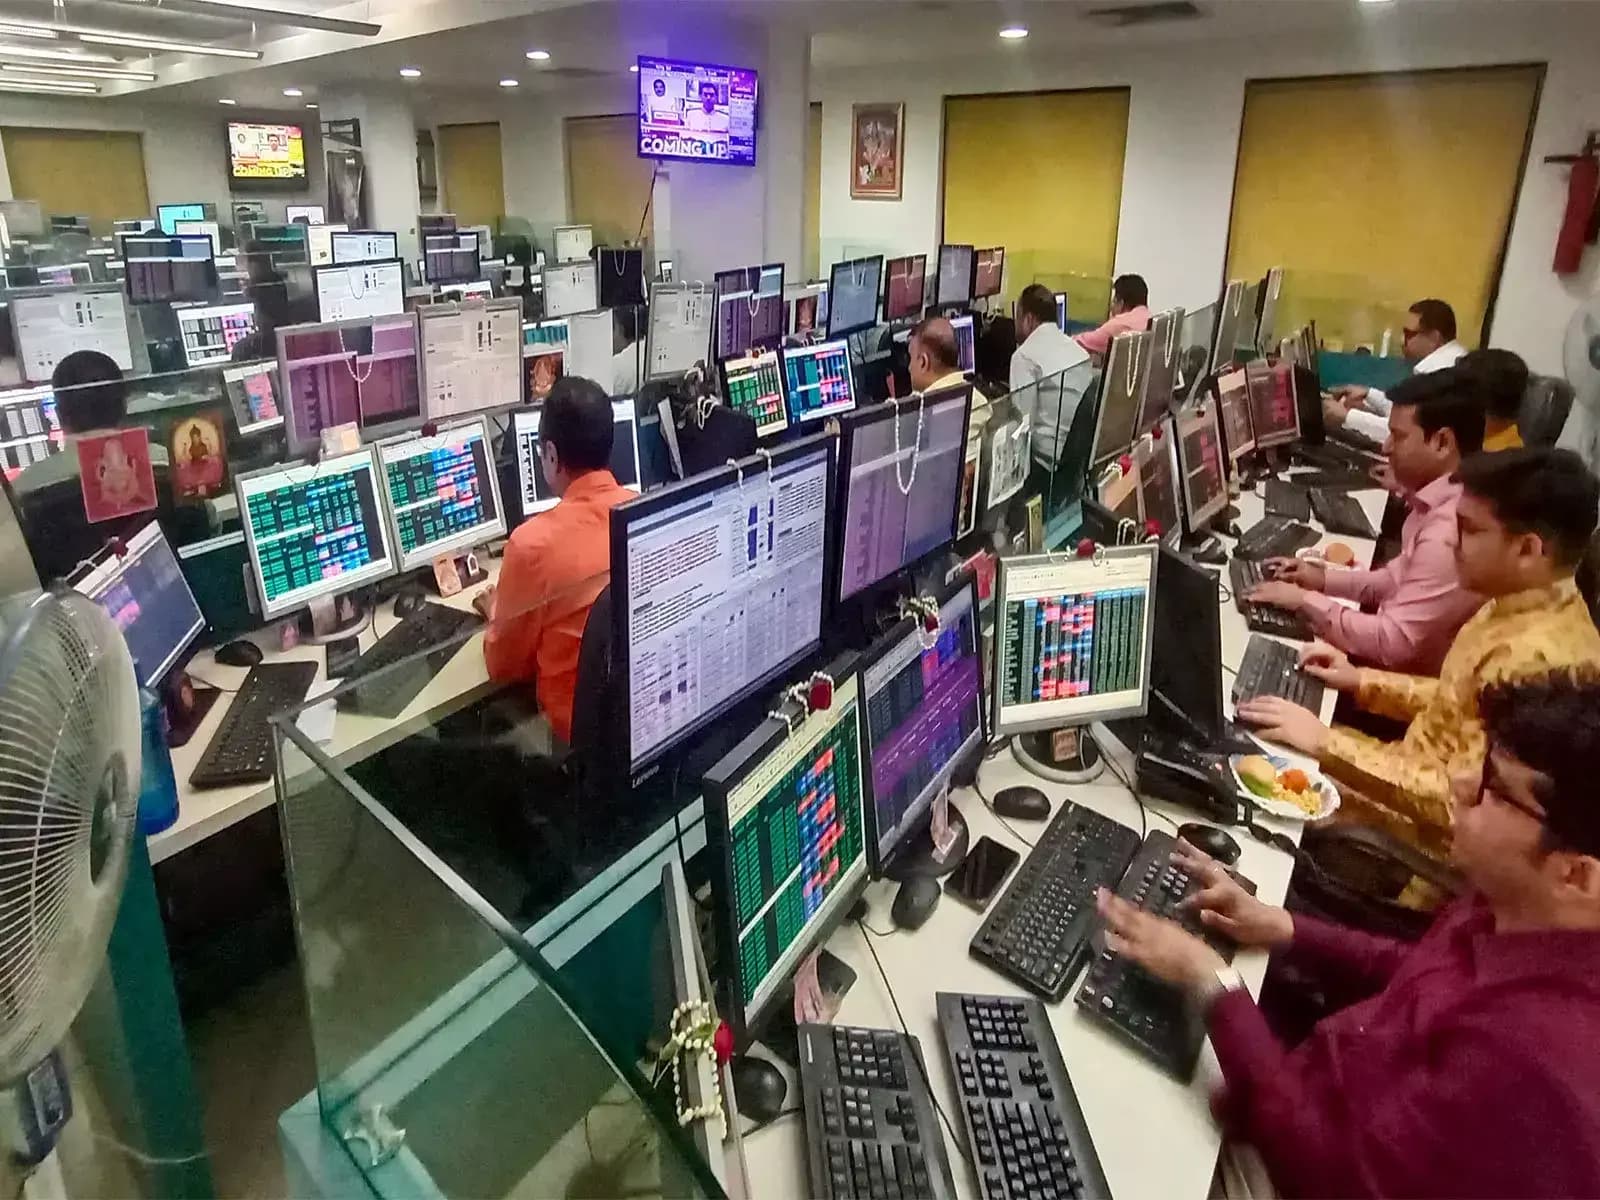
The crude oil shock could significantly impact India Inc's earnings outlook for the coming quarters. After the December-quarter results, consensus pegged Nifty 50's FY27 earnings growth at around 16%, but experts warn this could slip into single digits if the oil shock persists. Harshal Dasani, business head at INVasset PMS, noted that Indian markets are likely to remain extra sensitive to fresh global triggers, given they were already contending with valuation fatigue and sector-specific stress, particularly in IT. "It's less about panic and more about risk positioning," he said. "When markets are stretched, they tend to react more swiftly as uncertainty rises." The immediate quarter may escape major damage, but prolonged elevated crude prices could squeeze India Inc's profit margins at a time when its profit growth slowed to a five-quarter low in the December quarter. Top laggards included Aviation (IndiGo -5%), Real Estate (Nifty Realty -4%), and Auto (Maruti -2.5%), while upstream oil companies like ONGC (+0.47%) and defense stocks like HAL and BEL showed resilience. The Indian chemicals sector is also facing similar headwinds, with heightened tensions involving countries such as Israel and Iran increasing risks around key maritime routes, particularly the Strait of Hormuz—a vital corridor for global energy and chemical shipments.
From a technical standpoint, the breach of 25,000 on the Nifty is significant, with the index now testing support zones at 24,800 and 24,600. For the Sensex, the 80,000 mark remains the immediate psychological floor. Despite current volatility, historical analysis shows that markets typically recover quickly from geopolitical shocks. In each of these episodes, the market recovered to its pre-shock levels within nine days on average, according to Mint's analysis of major post-Covid conflicts. However, experts warned that this crisis could test market resilience more severely, as crude prices near $80 and major growth tailwinds already priced in create additional pressure. India's benchmark Nifty 50 fared marginally better than most emerging peers, with Thailand leading declines at nearly 4%, followed by Indonesia and Hong Kong where benchmark indices slipped 2-3%.