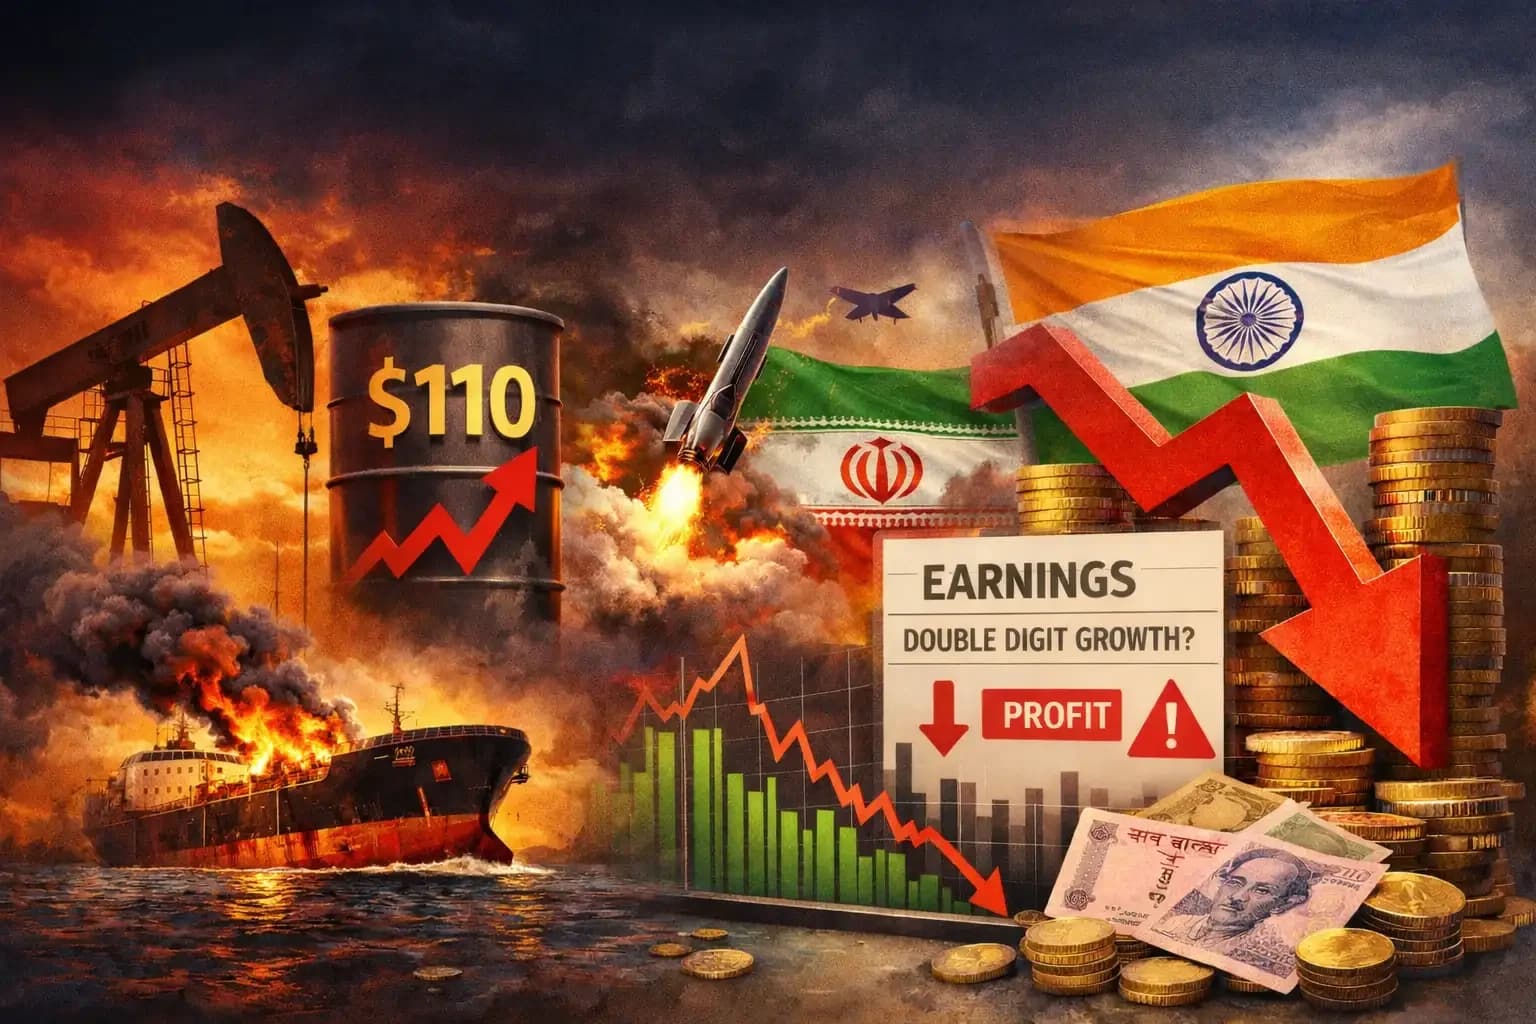
India Inc's expected double-digit earnings growth for FY27 faces significant risk as crude oil surges past $110 a barrel and the Iran conflict escalates. According to reports from The Economic Times, consensus estimates for FY27 growth have been downgraded from a robust 15-16% to a more modest 8-13% range, with risks of further cuts if the conflict prolongs. Dr V K Vijayakumar, Chief Investment Strategist at Geojit Investments Limited, warns that if crude remains elevated and gas availability restrictions continue, another round of earnings downgrades will become inevitable, particularly for import-intensive and crude-related segments. The oil shock has already forced analysts to slash their optimism, with overall FY26 earnings remaining subdued to single digits.
The Q4 FY26 earnings season kicks off this week with IT bellwether Tata Consultancy Services (TCS) announcing results on April 9. As reported by The Economic Times, what was expected to be a quarter cementing India Inc's recovery trajectory could instead mark the beginning of a painful recalibration of profit expectations across sectors. Axis Securities notes that Q4FY26 management commentary will be critical in reassessing FY27 earnings expectations, especially with elevated crude prices hovering near $110-115/bbl. The recent oil shock challenges earlier assumptions of stable input costs, steady demand recovery, and margin normalization that were underpinning mid-teen earnings growth expectations for the Nifty 50. Any indication of cost absorption, weak pricing ability, or early demand slowdown could trigger earnings downgrades, with the upcoming earnings season being pivotal in determining whether the oil-led disruption is transient or likely to have a more structural impact.
The damage is already visible across energy-intensive industries, with paints, adhesives, and tyres sectors hit by petroleum input costs. According to The Economic Times, energy-intensive manufacturing including fertilizers, chemicals, ceramics, paints, glass, and tires face severe margin pressure from acute LPG/LNG shortages, plant shutdowns, and sharp spikes in input costs. The impact will be felt most acutely in Q1 FY27 rather than Q4, as noted by Dr V K Vijayakumar. The auto and aviation sectors are similarly struggling with production hiccups and surging fuel expenses that directly squeeze profitability and dampen consumer demand. IT services are expected to report a muted finish to the fiscal year as global uncertainty delays deal closures, though exporters will gain from currency tailwinds. Oil marketing companies, logistics, and export-heavy sectors like gems and jewelry are navigating elevated volatility and a broader consumption slowdown, while upstream oil and defense remain relatively resilient.
Despite the headwinds, some analysts maintain cautious optimism. Motilal Oswal argues that while the ongoing war may have adverse impact on current earnings estimates, the impact should not be as sharp as seen at the start of FY25. As reported by The Economic Times, the brokerage estimates ~16% earnings CAGR for both the MOFSL universe and Nifty over FY26-28, though this may come under test due to geopolitical upheaval. Sanjeev Prasad from Kotak Institutional Equities notes that limited earnings downgrades for FY2027E and FY2028E are possible if the Iran-Israel/US war ends within 2-3 weeks and oil & gas supply conditions improve over the next few months. The critical question now is whether crude prices stabilize quickly or remain elevated for months, with Axis Securities warning that if elevated oil prices persist longer than anticipated, the impact on input costs, margins, and overall corporate profitability could be meaningful.
The critical question now is whether crude prices stabilize quickly or remain elevated for months. According to Axis Securities, if elevated oil prices persist longer than anticipated, the impact on input costs, margins, and overall corporate profitability could be meaningful, thereby increasing the likelihood of earnings downgrades across sectors. As Q4 results roll out over the coming weeks, management guidance for FY27 will be the critical metric to watch even as the broader markets have likely already priced in much of this near-term damage. For now, India Inc's double-digit dream hangs in the balance, hostage to events unfolding thousands of miles away in the Middle East. The stakes are particularly high as the much-anticipated double-digit earnings growth that was supposed to define India Inc's FY27 is now at serious risk and looks delayed by at least two quarters and potentially downgraded to single digits if the geopolitical storm persists.