Michael Saylor has made an unexpected endorsement of his Bitcoin rival Strive, stating in a Wednesday essay on X that he 'wants Strive to succeed' and wants every well-managed issuer of Bitcoin-powered Digital Credit to succeed. This support is particularly notable given that MicroStrategy holds 847,666 BTC, more than any other listed company, while Strive ranks fifth among public holders with 27,462 BTC. As Saylor explained, every coin Strive buys adds demand for an asset with a fixed supply, arguing that a higher price would lift the value of both companies' holdings. The two firms follow the same playbook of raising money from investors to buy Bitcoin, with Strive CEO Matt Cole agreeing that the two firms are stronger together.
Michael Saylor has unveiled an ambitious prediction that Bitcoin could reach a $120 trillion market capitalization if it captures just 10% of the global asset pool. Speaking on September 29, Saylor described Bitcoin as entering 'hyper-growth mode' and framed the opportunity as a 'BTC gold rush'. The calculation involves starting with the roughly $3 trillion crypto economy and projecting Bitcoin's potential share of a much broader asset pool valued at $1,000-1,200 trillion. Saylor emphasized that this represents a 40-fold increase from current levels, though he acknowledged the arithmetic is straightforward while important questions about the starting measure and adoption assumptions remain unresolved.
The ties between MicroStrategy and Strive extend beyond competitive dynamics, with Strive serving as a significant customer of MicroStrategy. As reported by AMBCrypto, Strive purchased $50 million of MicroStrategy's STRC shares in March, initially acquiring 500,000 shares. The relationship has continued with both firms making recent Bitcoin purchases - Strive bought 1,355 BTC on September 21 and both companies added Bitcoin this week, with MicroStrategy purchasing 1,666 BTC. Strive CEO Matt Cole revealed that the company raised 85% of the money for its latest purchase by selling SATA, paying an average of $85,396 per coin while Bitcoin traded near $83,699 on Wednesday. This cross-holding relationship demonstrates the practical benefits of cooperation between Bitcoin treasury companies.
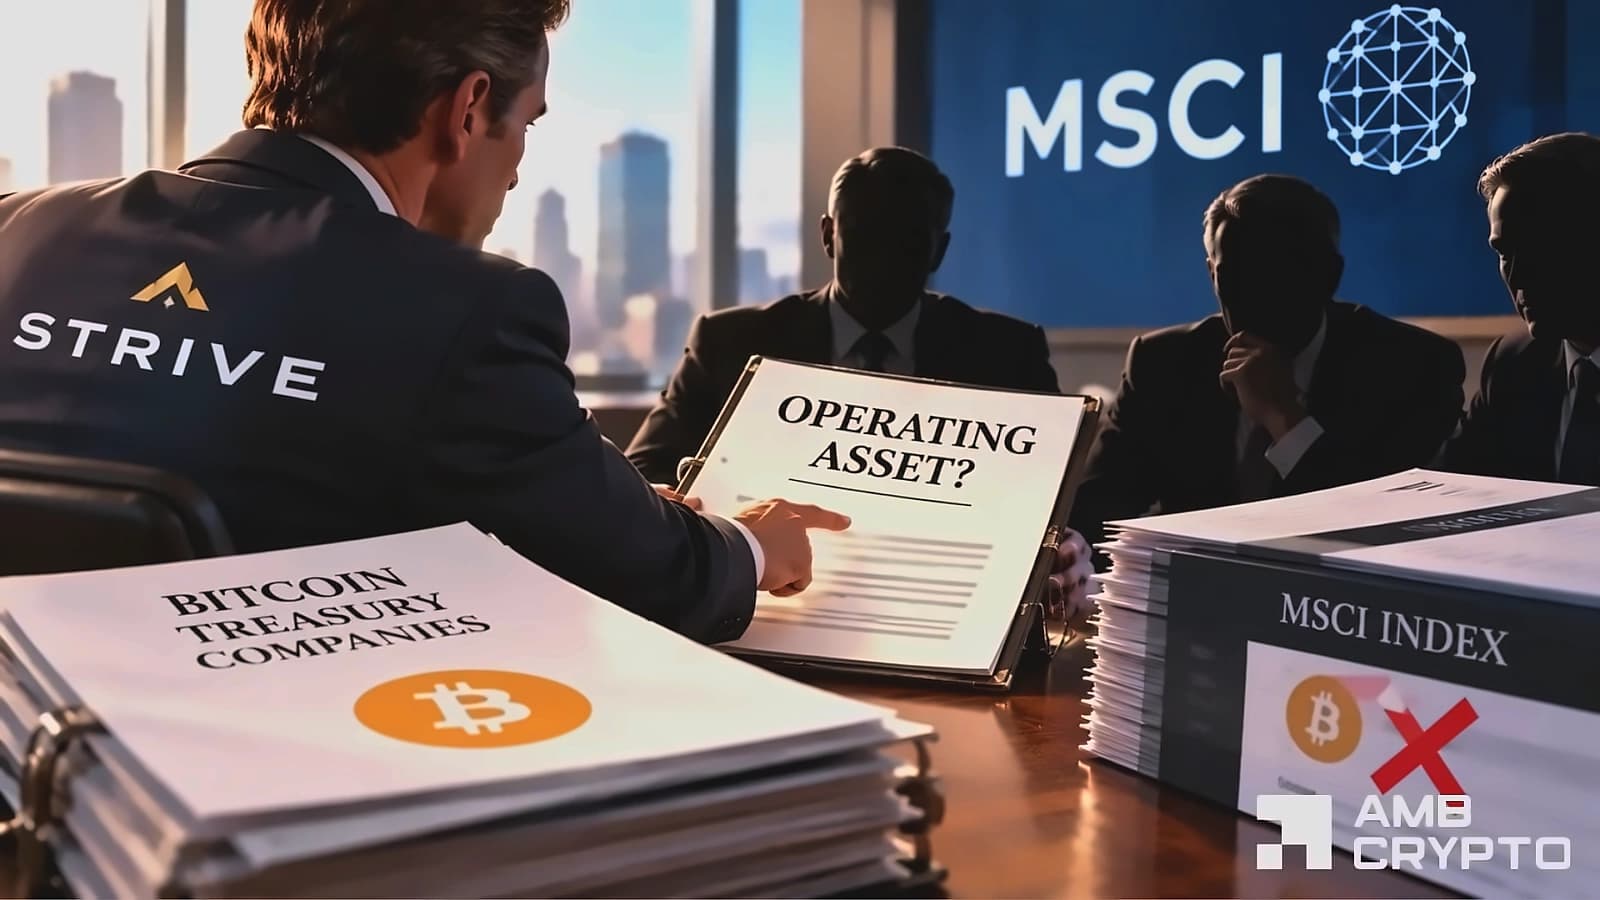
Strive, the fifth-largest Bitcoin treasury, has mounted a significant challenge against MSCI's proposal to exclude crypto treasuries from the global index. According to reports from AMBCrypto, Strive's feedback on the proposal acknowledges the 2026 framework as a material improvement over the 2025 version, which directly targeted crypto treasuries for exclusion. The current proposal asks a fundamental question: when does a public corporation cease to be an operating company and become, in economic substance, an investment vehicle? Strive argues that MSCI is now asking the right question but has yet to supply a rule capable of answering it, while also asking MSCI to define the meaning of 'operating asset'.
Strive has insisted that Bitcoin treasuries fit the profile of an operating company, citing Strategy's digital credit products tied to BTC reserves as evidence. As reported by AMBCrypto, companies that issue digital credit belong on the operating side of the line, using balance sheet assets as inputs, applying continuing financial and risk-management processes, and producing differentiated financial claims with payment and risk characteristics. Strategy's list of preferred stocks, including STRC, STRF, STRK, and STRD, earn bi-monthly and quarterly dividends, with a proposal to offer daily interest. TD Securities has made a similar argument, stating that the primary product is not Bitcoin itself, but rather differentiated forms of Bitcoin-backed exposure tailored to varying investor preferences for risk, duration, leverage, yield and liquidity.
Despite Saylor's support, the competitive landscape faces challenges from investor skepticism. According to DWF Ventures, only four of the top 20 crypto treasury stocks trade above the value of the coins they hold. Bitcoin pays no interest, and Saylor acknowledged this reality in his essay, noting that the income promised to investors must come from company cash or new fundraising. The competitive dividend structure remains evident, with Strategy's STRC carrying a 12% annualized dividend rate and Strive's SATA maintaining a 13% annualized dividend rate. Saylor himself warned that one weak company could damage trust across the whole sector, highlighting the importance of maintaining strong operational performance and investor confidence in the Bitcoin treasury model.