The stablecoin card market is expanding with innovative solutions addressing longstanding user challenges. Phemex has launched a new crypto Mastercard that draws directly from available USDT or USDC in users' spot accounts, removing the need for separate card balances. Unlike traditional prepaid cards that require users to move funds before spending, the Phemex card converts stablecoins on-the-fly when purchases are made. The card supports Apple Pay and Google Pay and is currently available to eligible residents of the European Economic Area. This represents a practical advancement over existing solutions like Crypto.com's prepaid card, which still requires separate balance management despite offering automatic top-ups.
Global payments giant Visa has reported nearly 200% year-over-year growth in payment volume across its stablecoin-linked card programs, demonstrating the rapid acceleration of stablecoin adoption in mainstream payments. According to Visa's latest data, more than 160 consumer, business and commercial programs are now operating globally, representing a significant expansion from previous figures. The company also revealed that stablecoin settlement activity has surpassed a $4.5 billion annualized run rate as of January 2026, highlighting the substantial scale of real-world stablecoin usage in the payments ecosystem. However, these settlement figures represent settlement activity between payment organizations rather than completed consumer purchases, with the annualized rate extending shorter periods across a full year.
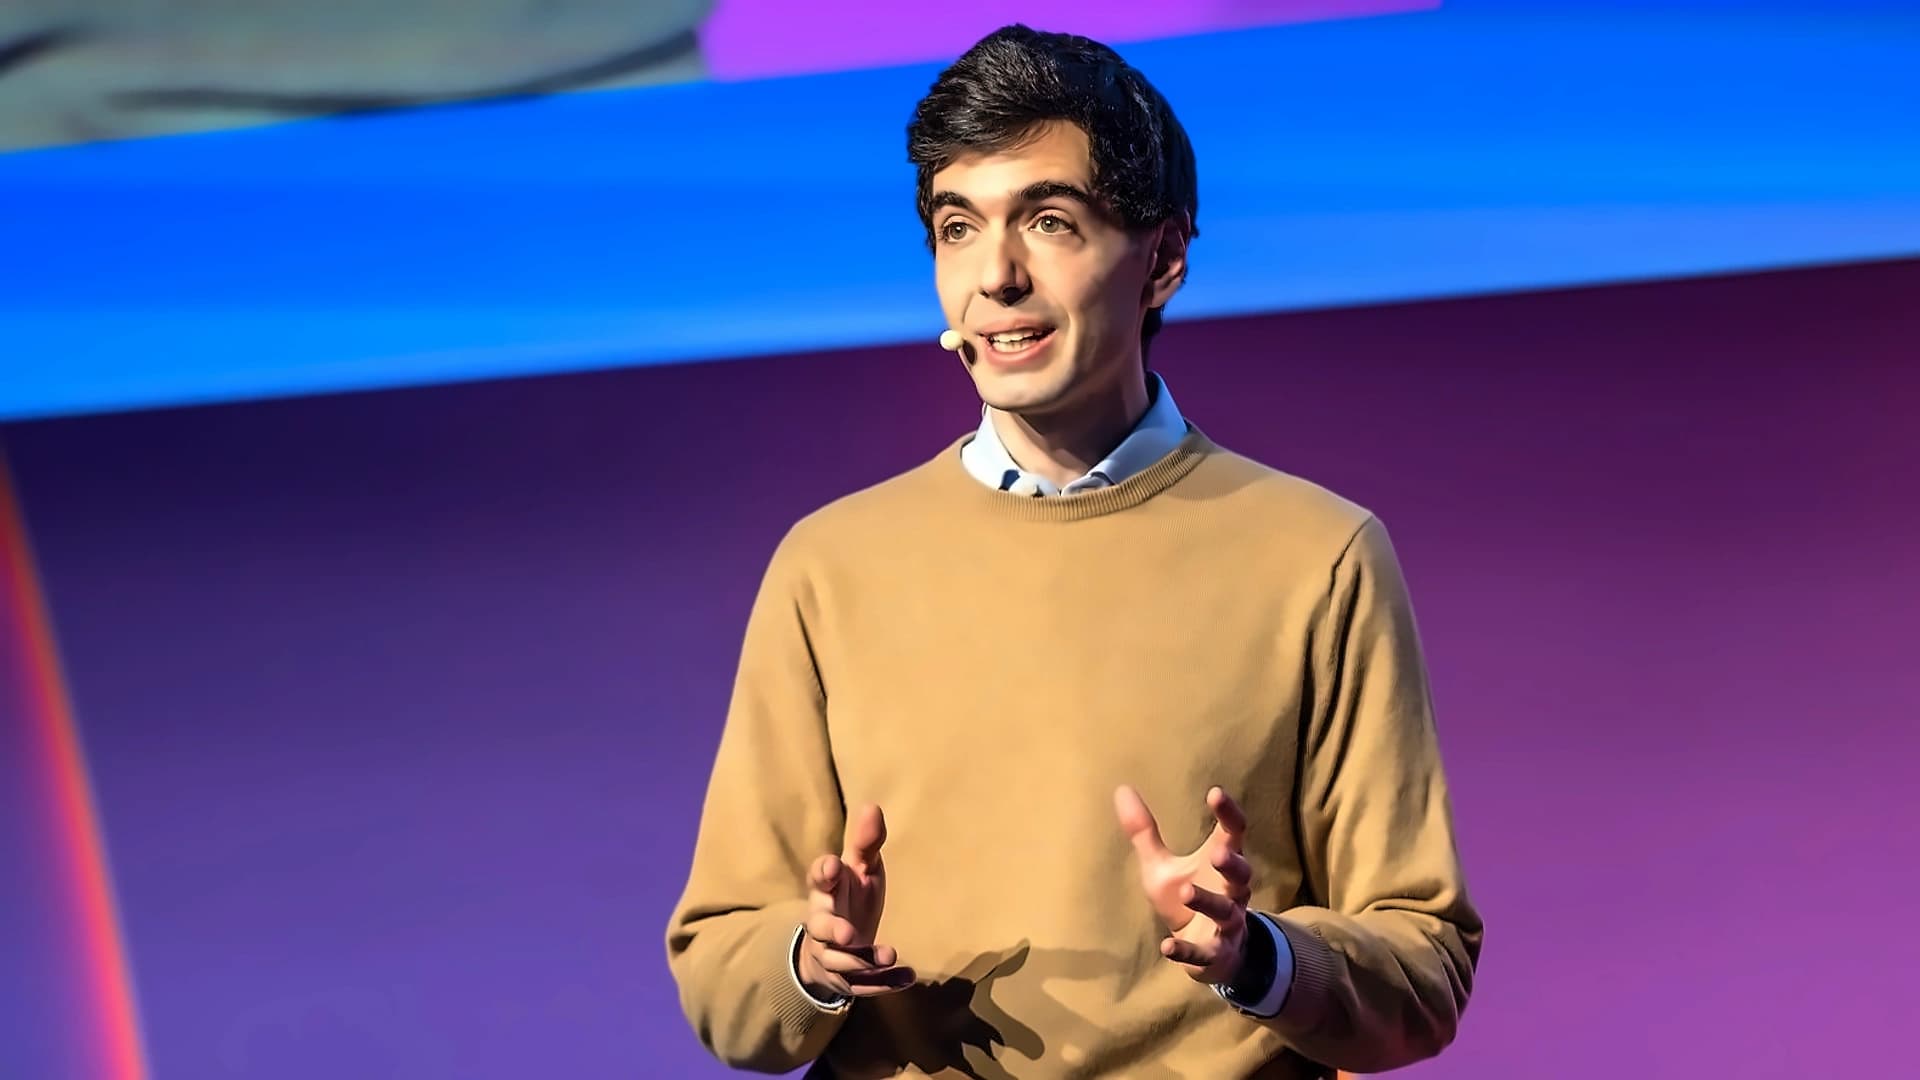
Global payments giant Stripe is planning a major global expansion for its stablecoin cards business, with CEO Henri Stern announcing plans to expand stablecoin card programs to more than 100 countries by year-end. According to reports from CoinDesk, Stern has taken on an additional role overseeing stablecoins and crypto across Stripe, having previously served as CEO and co-founder of crypto wallet infrastructure firm Privy that Stripe acquired in 2025. Current customers include crypto exchange Kraken, fintech Ramp, and payments app Morse. Stripe processes trillions of dollars annually for companies ranging from early-stage startups to large enterprises across various sectors including retail, travel, AI, insurance, SaaS, and nonprofits. The company's approach involves plugging stablecoins into existing infrastructure rather than building separate crypto systems, combining its card issuing business with Bridge, the stablecoin infrastructure company Stripe purchased for $1.1 billion in 2024.
The expansion comes as stablecoin cards emerge as a fast-growing corner of the $300 billion-plus digital dollar market. As reported by PaymentScan, about $1.2 billion of stablecoins were spent through cards last month, tripling in volume from a year earlier. According to Visa's latest data, business and commercial cards make up about 17% of fiscal 2026 year-to-date stablecoin-linked card volume, indicating growing institutional adoption beyond consumer use cases. Stripe has issued more than 400 million cards and processed hundreds of billions of dollars in card volume since 2018. However, as noted by AMBCrypto, stablecoin card adoption numbers can be misleading since a card can work at millions of shops without those shops ever receiving stablecoins, and the acceptance network already exists with the new card connecting to it rather than retailers introducing cryptocurrency checkouts.
According to CoinDesk reports, Stripe's approach involves plugging stablecoins into existing infrastructure rather than building separate crypto systems. The company combines its card issuing business with Bridge, the stablecoin infrastructure company Stripe purchased for $1.1 billion in 2024. For companies like Ramp, this could mean taking corporate cards into new countries using stablecoins instead of rebuilding banking and payments connections market by market. Kraken has explored letting customers spend from accounts where they already hold digital assets. Phemex takes this integration further by allowing users to spend directly from their spot account balance without requiring separate card top-ups. Phemex charges no issuance or annual fee, but builds variable conversion charges into the rates used to convert stablecoins to regular money, with additional costs for currency conversion when spending in euros.
As reported by CoinDesk, Stripe has been assembling pieces for a broader blockchain payments push after acquiring Bridge and Privy. The company also partnered with crypto investment firm Paradigm to develop Tempo, a blockchain designed for payments. Stripe is also a founding investor in Open Standard, the company developing Open USD, a stablecoin that aims to challenge Circle's USDC and Tether's USDT. Bridge co-founder Zach Abrams recently moved to run Open Standard full time. Stripe provides developer tools and APIs for businesses to accept payments globally, prevent fraud, automate revenue management, move and manage money, monetise payments and financial services, and operate across borders.
According to CoinDesk interviews, Stern emphasized that Stripe remains 'completely stablecoin agnostic, completely blockchain agnostic' and intends to cater to users who are here for stablecoins only while serving millions of users of Stripe who use fiat rails. The company is exploring tokenized deposits, decentralized finance (DeFi) use cases, and accepting more digital assets as payments, with Stern noting that 'by far, the bulk of our work happens with stablecoins'. Phemex offers cashback rewards in USDT directly into users' spot accounts, with standard users earning 0.25% and VIP users receiving 1% on eligible spending. The card settles in US dollars, with the company charging variable conversion costs and additional fees for currency conversion when spending in euros. Visa is also expanding stablecoin tools for settlement, payouts, funding and enterprise infrastructure, indicating the growing institutional focus on stablecoin payments across the payments industry.