
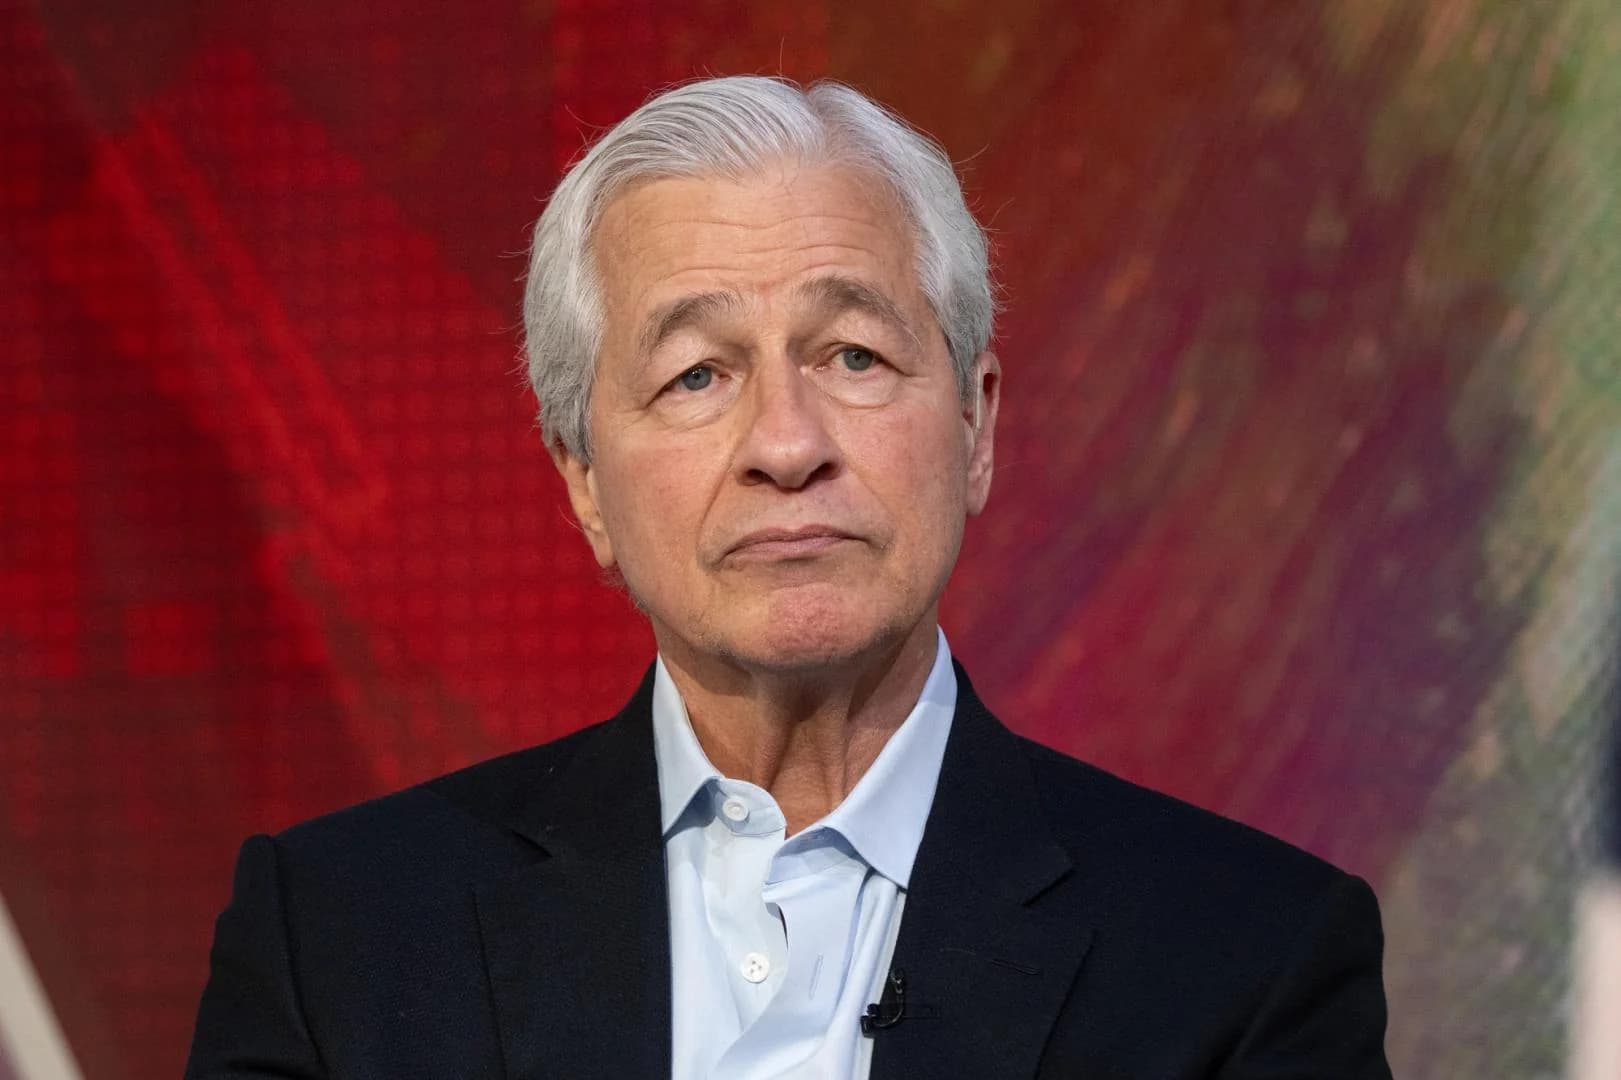
JPMorgan Chase CEO Jamie Dimon has called for stablecoin issuers that pay interest on customer balances to face the same regulatory requirements as traditional banks. According to reports from CoinDesk, Dimon made these comments during an interview with CNBC on Tuesday, arguing that firms operating like deposit-taking institutions should meet the same standards as banks, including capital and liquidity rules, anti-money laundering controls and federal deposit insurance requirements. He drew a distinction between transaction-based rewards and interest on stored balances, stating that 'rewards are the same as interest' and that companies paying interest should be regulated accordingly. As reported by ETHNews, Dimon reiterated his position by stating, 'If you are going to be holding balances and paying interest, that's the bank. Not a payment company. Not a fintech. A bank, with all the obligations that classification carries.'
The regulatory debate has intensified following the CLARITY Act's missed March 1, 2026 deadline for a deal between lawmakers and the crypto industry. According to ETHNews, the legislative standoff comes down to whether stablecoin issuers can offer yield to users, and neither side has moved enough to close the gap. JPMorgan analysts still forecast the CLARITY Act passes by mid-2026, though the missed deadline represents a setback rather than a collapse. The window for passage is narrowing, with midterm election dynamics making legislation harder to push through after August 2026, and the political coalition requiring both crypto-friendly Republicans and enough Democrats to avoid a filibuster. The stablecoin rewards question has become the sticking point that could either get resolved in a compromise or kill the bill entirely.
Despite the regulatory stance, Dimon has proposed a more nuanced middle ground that distinguishes between different types of stablecoin rewards. As reported by CoinDesk, Dimon's proposed compromise allows rewards paid on transactions to be acceptable, as they function as payment incentives similar to credit card rewards. However, rewards paid on stagnant balances that sit in an account earning returns without any transaction activity are the problem. This distinction, functional payment tool versus deposit-like investment vehicle, is where he draws the regulatory line. The context behind Dimon's renewed push includes a reported confrontation at the World Economic Forum in early 2026 with Coinbase CEO Brian Armstrong, who has been arguing that banks are using regulation as a weapon to block crypto competition. Dimon framed the issue as one of fairness and safety, stating 'Level playing field by product,' arguing that companies offering similar financial services should operate under similar oversight.
Despite the regulatory stance, Dimon emphasized that JPMorgan supports competition and uses blockchain in its own operations. According to CoinDesk reports, the bank has developed a deposit token and processes payments and data transfers on distributed ledger systems. Dimon stressed that the bank is 'in favor of competition, but it's got to be fair and balanced.' He pointed to the broader compliance burden banks carry, including anti-money laundering checks and community lending obligations, designed to protect the financial system for the safety of the system, not just fairness of competition. As reported by ETHNews, Dimon's counter to Armstrong's demand for a level playing field is that Armstrong's demand for the same access to customers and financial activity that banks have should also carry the same regulatory burden.
The stablecoin oversight debate has become a central issue as the Financial Action Task Force (FATF) has warned that stablecoins are increasingly used in sanctions evasion and money laundering. According to CoinDesk, recent analyses show stablecoins accounted for the vast majority of illicit crypto transaction volume in 2024 and 2025. The FATF has called for stronger regulation of stablecoin issuers, with the international anti-money laundering standards body releasing a report on March 4th citing concerns about stablecoins becoming a primary tool for illicit transactions. This regulatory pressure adds urgency to the legislative debate as lawmakers weigh how to regulate digital assets without pushing activity into less transparent market corners. The FATF has urged countries to impose anti-money laundering rules on stablecoin issuers, address risks from peer-to-peer transfers via unhosted wallets, and consider tools such as wallet freezing and restrictions on certain smart-contract functions as the market surpasses $300 billion.