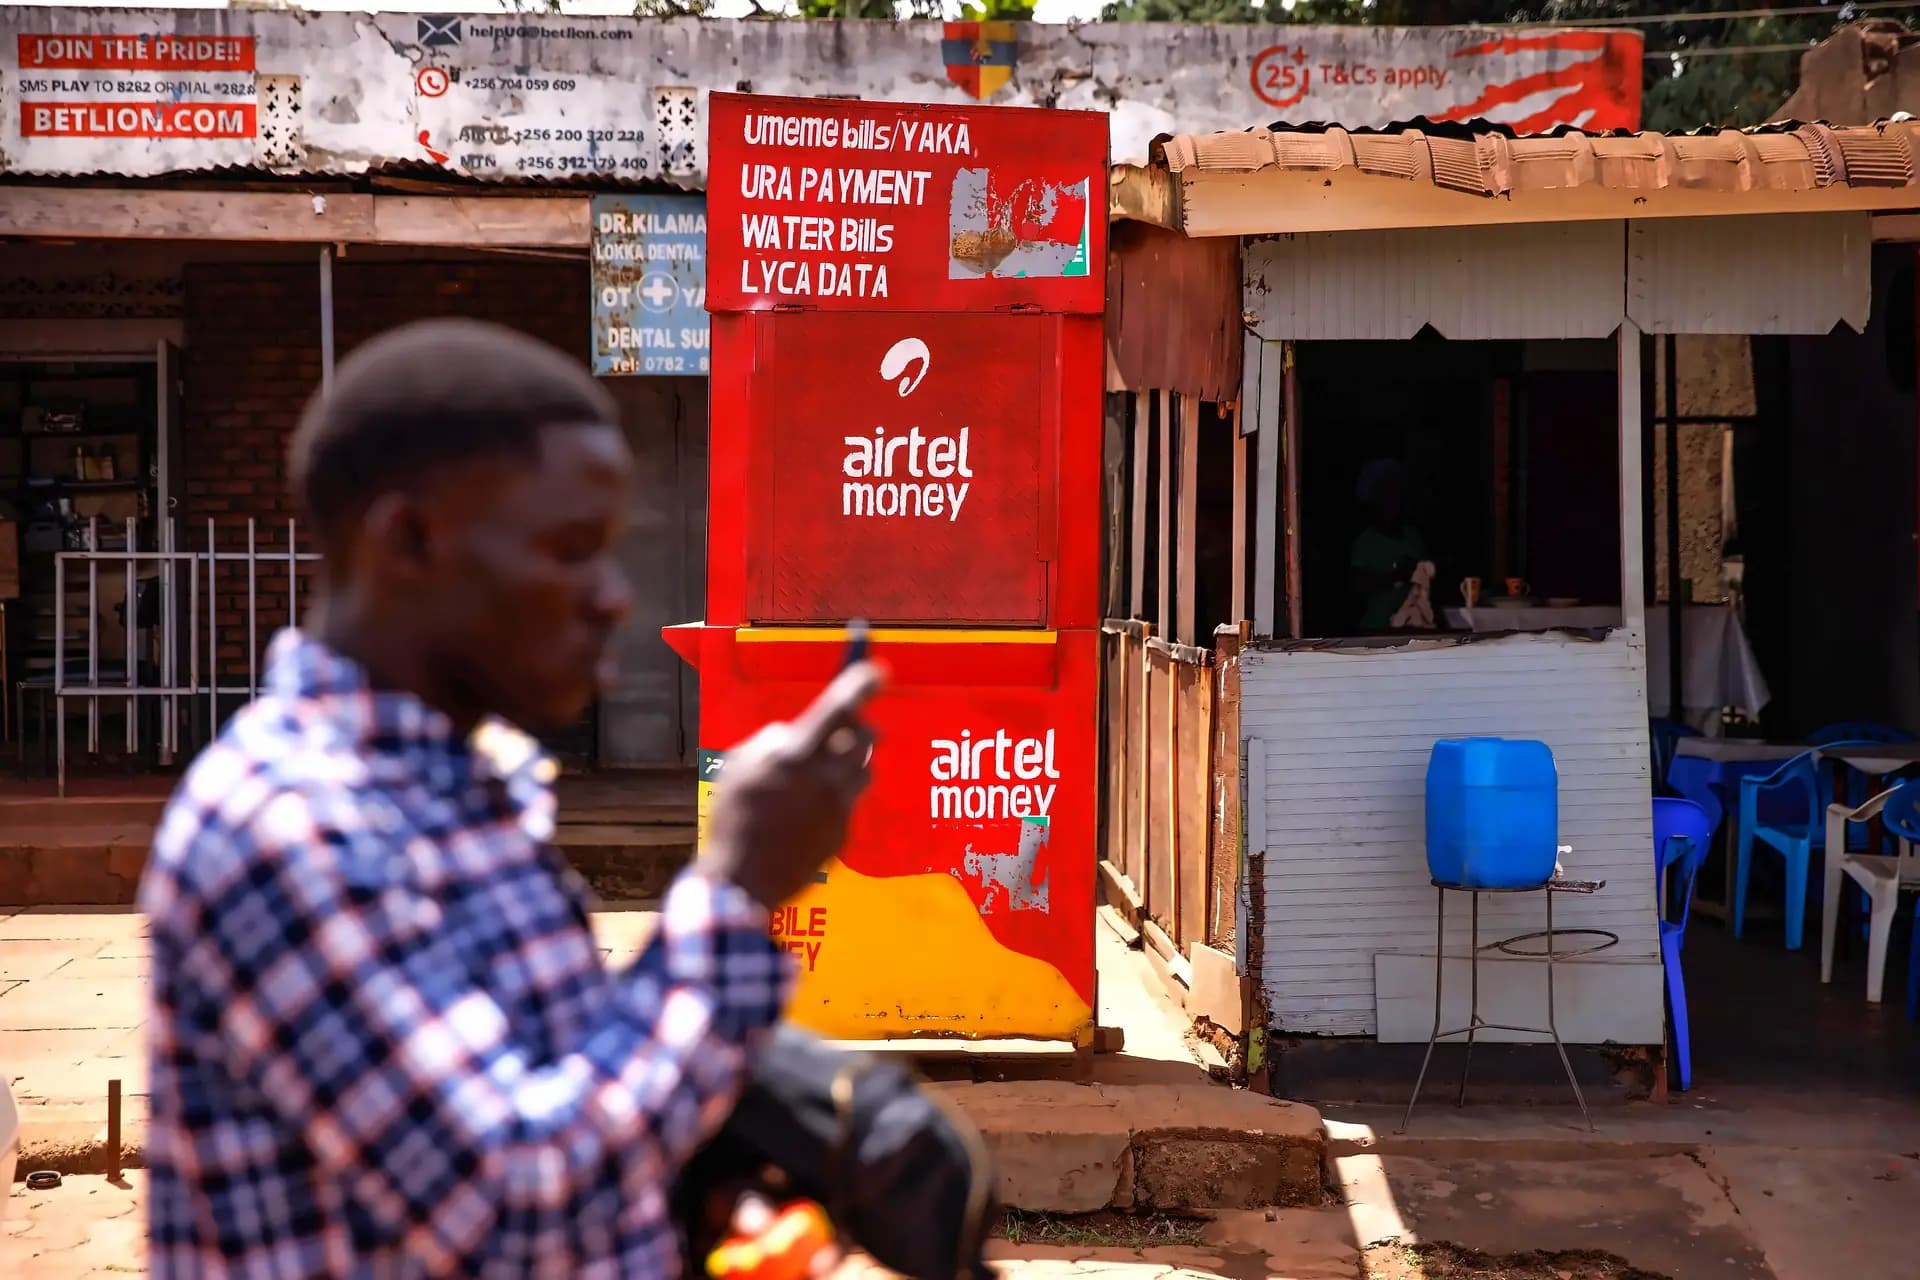
Bharti Airtel delivered a strong performance for the quarter ended September 30, 2026, reporting consolidated revenue of Rs 60,878 crore, up 16.7% year-on-year. This growth was fueled by robust execution across both its Indian and African operations, though the dynamics differed significantly between the two geographies. While India provided steady, quality-led growth, Africa emerged as the faster-growing engine, driving the consolidated top line beyond what the domestic business alone could achieve.
India: The ARPU Story
The India business reported revenue of Rs 42,308 crore, a 9.4% increase. The star of the show was undoubtedly the mobile segment, where revenue grew 10.1% year-on-year. This wasn't about adding millions of low-value users; it was about getting more from the existing ones. The company's mobile Average Revenue Per User (ARPU) climbed to Rs 271, up from Rs 256 in the previous year.
This ARPU expansion was the primary driver, accounting for a little over half of the mobile revenue growth. The rest came from a larger, better-quality customer base. The company added 18.8 million smartphone data customers over the past year, shifting the mix decisively toward data-consuming users. This strategy, known as portfolio premiumisation, focuses on winning quality customers rather than chasing sheer subscriber volume. The results speak for themselves: postpaid net additions hit a record 1.2 million during the quarter, and smartphone data customers grew by 2.9 million sequentially.
Africa: The High-Growth Engine
While India delivered steady growth, Africa delivered speed. The continent's revenue grew 20.6% year-on-year in constant currency terms, significantly outpacing India's 9.4%. The customer base expanded to 193.9 million, supported by strategic investments in digital infrastructure, including the deployment of 497 towers and 11,684 mobile broadband base stations during the quarter.
This growth trajectory isn't new. Management has highlighted that Africa has delivered a constant currency revenue CAGR of over 20% for five years, contributing nearly half of the group's consolidated revenue growth. The drivers are a mix of network expansion and operational improvements. The company is rolling out its homegrown technology stack across African markets, standardizing platforms and processes that have worked in India. This "War on Waste" program, combined with shared infrastructure deals, is improving efficiency and supporting the 6.7% quarter-on-quarter constant currency growth reported for the region. Transcript
The Profit Miss: Expansion vs. Earnings
The financial picture wasn't without its wrinkles. Net profit before exceptional items rose 32.7% year-on-year to Rs 9,015 crore. However, a reported net profit figure of Rs 8,888 crore missed the CNBC-TV18 estimate of Rs 9,209 crore by about 3.5%. This miss, despite strong revenue growth, underscores the inherent tension between aggressive network expansion and immediate profitability.
The company is investing heavily to build capacity. Capital expenditure for the quarter stood at Rs 12,467 crore, including Rs 9,908 crore in India. Additionally, Rs 2,826 crore was invested in a strategic land parcel for future data center expansion. These investments boost depreciation and finance costs, which flow below the EBITDA line. Consequently, while EBITDA margins expanded to 57.9%—up 50 basis points from the previous year—net profit felt the pressure of these heavy capital outlays.
The ARPU-Margin Relationship
The ability to sustain these high EBITDA margins amid rising infrastructure costs hinges directly on ARPU. Network costs are largely fixed; when ARPU rises faster than these costs, the additional revenue flows largely to the bottom line. The increase to Rs 271, up from Rs 264 in the previous quarter, demonstrates this leverage in action.
This ARPU growth is being driven by several factors. The company is successfully migrating feature phone users to smartphones, with 4G/5G users now comprising over 80% of the mobile base. Rising data consumption, 5G adoption, and international roaming are all contributing to higher spending per user. Furthermore, the company is differentiating its postpaid offering through "Fast Lane" technology, which uses 5G network slicing to provide priority data to premium customers. The recent partnership with Apple to bundle iCloud+, Apple TV, and Apple Arcade with family postpaid plans aims to further this premiumisation push, though its impact in Q2 was likely limited given the late-September announcement. Transcript +1
Beyond Mobile: Homes and Business
The growth story extends beyond the core mobile business. The Homes segment reported a 25.3% year-on-year revenue increase, driven by 676,000 customer additions during the quarter. This growth is supported by a disciplined acquisition strategy and a focus on fixed-mobile convergence. The company has shifted its approach in this segment, tightening FWA (Fixed Wireless Access) acquisition quality to improve cohort economics and focusing on fibre deployment where it makes the most sense. Transcript
Airtel Business also delivered strong momentum, with revenue growing 11.4% year-on-year and 3.8% sequentially. This growth is broad-based, spanning core connectivity and digital services like cloud, cybersecurity, IoT, and CPaaS. The company is also making significant bets on future infrastructure, with ambitions to build 1 GW of data center capacity through its Nxtra subsidiary. Transcript
Synergies and the Outlook
Across the group, management emphasizes that synergies are beginning to deliver tangible operating gains. These include sharing technology platforms, procurement, and best practices between India and Africa. The expansion of Indus Towers into African markets is expected to lower tower-related costs, while shared energy initiatives aim to reduce diesel dependence. Transcript +1
The balance sheet remains resilient, with the net debt-to-EBITDA ratio improving to 1.18x from 1.63x a year ago. This financial strength provides the flexibility to continue investing in growth while maintaining shareholder returns.
Looking ahead, the company's trajectory appears clear. India will continue to drive steady, margin-accretive growth through premiumisation and ARPU expansion. Africa will remain the high-growth engine, leveraging its vast market potential and operational improvements. The new growth engines—data centers, financial services, and digital B2B solutions—are gaining momentum. The trade-off between expansion and profitability will persist, but if ARPU continues its upward climb, Bharti Airtel is well-positioned to turn its heavy investments into sustainable long-term returns.