Shares of Vishal Mega Mart fell over 7% in two sessions and hit a new 52-week low of ₹86.63 on Thursday after reporting Q2FY27 results that disappointed investors. The stock has dropped roughly 34% so far in 2026, weighed down by a private equity stake sale in February. The PE firms, which are currently the company's promoters, retain a 40% stake, fueling investor concerns over further divestments and an ultimate exit. According to Motilal Oswal Financial Services, "Concerns over potential promoter stake sales and long-term promoter ownership remain key overhangs for the stock." With the stock trading around 42 times estimated FY27 earnings according to Bloomberg data, Vishal Mega Mart will need stronger sales growth and margin recovery to justify its valuation.
Vishal Mega Mart reported a net profit of ₹160 crore in Q2FY27, registering a growth of 3.7% from ₹152 crore in the year-ago period, falling short of earlier projections of 17.8% growth. Revenue during the September quarter grew 14% to ₹3,727 crore from ₹3,281 crore, YoY, though this also missed the estimated 17.4% growth. The company's same-store sales growth (SSSG) stood at 5.4%, indicating healthy performance from existing store locations, though this was largely impacted by the shift of festive demand from Q2 to Q3. The apparel segment's contribution to total revenue fell from 42.2% in the previous year's same quarter to 40.6% in Q2 FY27, while general merchandise and FMCG segments saw gains, rising to 29.6% and 29.7% of total revenue respectively. Earnings before interest, taxes, depreciation, and amortisation rose 4.4% to ₹412 crore from ₹395 crore in Q2 of FY26, while EBITDA margin narrowed to 12.1% from 13.2% year-on-year.
The key factor behind the earnings miss was the timing of festivals, with Navratri, Durga Puja and Dussehra shifting into the October-December quarter, affecting demand for clothing during the July-September period. According to JM Financial, apparel sales grew 9.5%, compared with 18.2% growth in fast-moving consumer goods (FMCG). At the operational front, EBITDA margin collapsed by 111 basis points to 12.1% in Q2FY27 from 13.2% year-on-year, representing a significant compression from the previous year. The company's adjusted profit after tax (PAT), before ESOP charges, stood at ₹172 crore, up 6.4% year-on-year, while adjusted PAT margin declined to 5.1% from 5.4% in the year-ago quarter. Operating EBITDA rose 3.7% YoY to ₹262 crore compared to ₹252.9 crore in the same period last year. Pre-Ind AS EBITDA margin contracted ~90bp YoY to 7.2%, due to weaker gross margin (-30bp YoY, ~20bp impact due to the festive shift) and higher employee costs including minimum wage hikes and ESOP costs.
Gross margin contracted 32 basis points year-on-year, pinched by inflation and a lower share of high-margin apparel sales. To manage these pressures, the company froze prices in its entry-level segment, undertook selective hikes on mid-priced merchandise, and implemented the largest increases at higher price points. These segments account for about 20%, 55%, and 25% of revenue, respectively. Management indicated that further price hikes may not be necessary at this stage. The company's adjusted profit after tax (PAT), before ESOP charges, stood at ₹172 crore, up 6.4% year-on-year, while adjusted PAT margin declined to 5.1% from 5.4% in the year-ago quarter. Operating EBITDA rose 3.7% YoY to ₹262 crore compared to ₹252.9 crore in the same period last year.
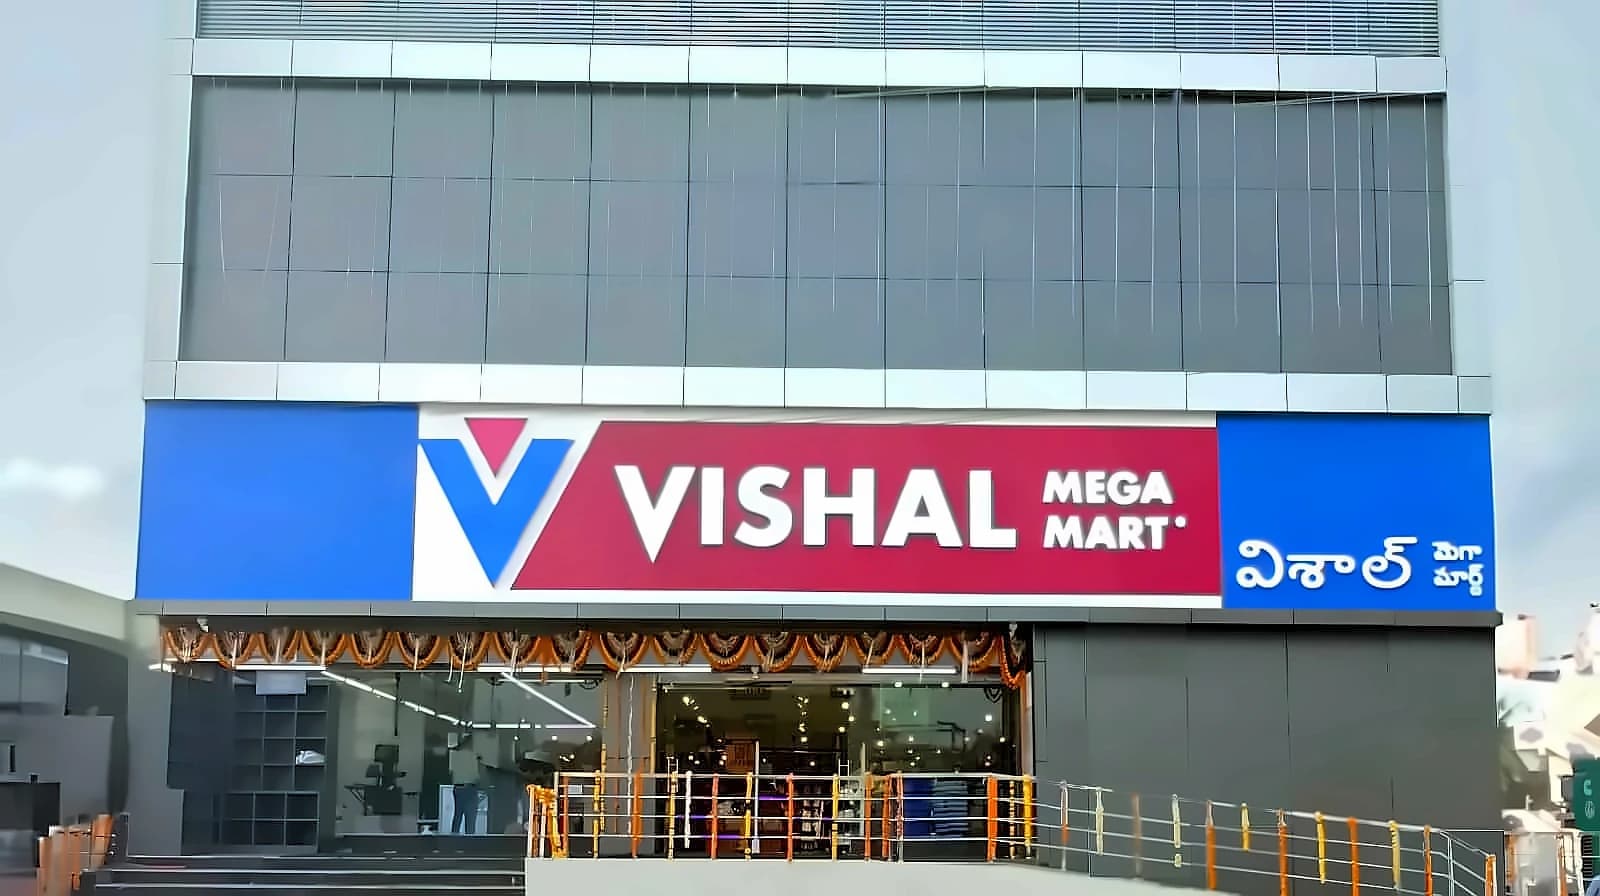
The retail chain added 26 gross stores and 25 net stores during Q2FY27, primarily in south India, demonstrating continued expansion despite margin pressures. As of September 30, 2026, the company operated 844 stores across 582 cities spanning a total retail area of ~1.41 crore Sq. Ft., showing steady growth in store count. Management estimates the retailer has room to expand its network to about 3,000 stores. During the second quarter, Vishal Mega Mart also piloted 'Belong & Co.', a premium clothing-focused format targeting young, affluent urban shoppers. Management noted an encouraging initial response, with more than 50% of store footfalls converting into purchases, as well as repeat visits. The company plans to open a few more pilot stores this year, before deciding on the wider expansion plan for this format.
Commenting on the results, Gunender Kapur, Founder, Chief Executive Officer and Managing Director noted that the company delivered another strong quarter supported by own-brand offerings and customer-first approach. Management reported a strong start to the festive season and expects double-digit same-store sales growth in Q3FY27, with the company targeting more than 100 store additions annually and expecting annual EBITDA margin improvement of around 30 basis points. The management expressed confidence that gross margins will remain stable in the second half, despite elevated raw material prices, having limited price increases to higher-priced products and not currently planning further hikes. Motilal Oswal notes that festive demand started strongly in 3Q, with no moderation in demand, supporting management's optimistic outlook. Operating leverage should help deliver ~30bp annual EBITDA margin expansion over the medium term, with cost reengineering likely to offset raw material inflationary pressures.