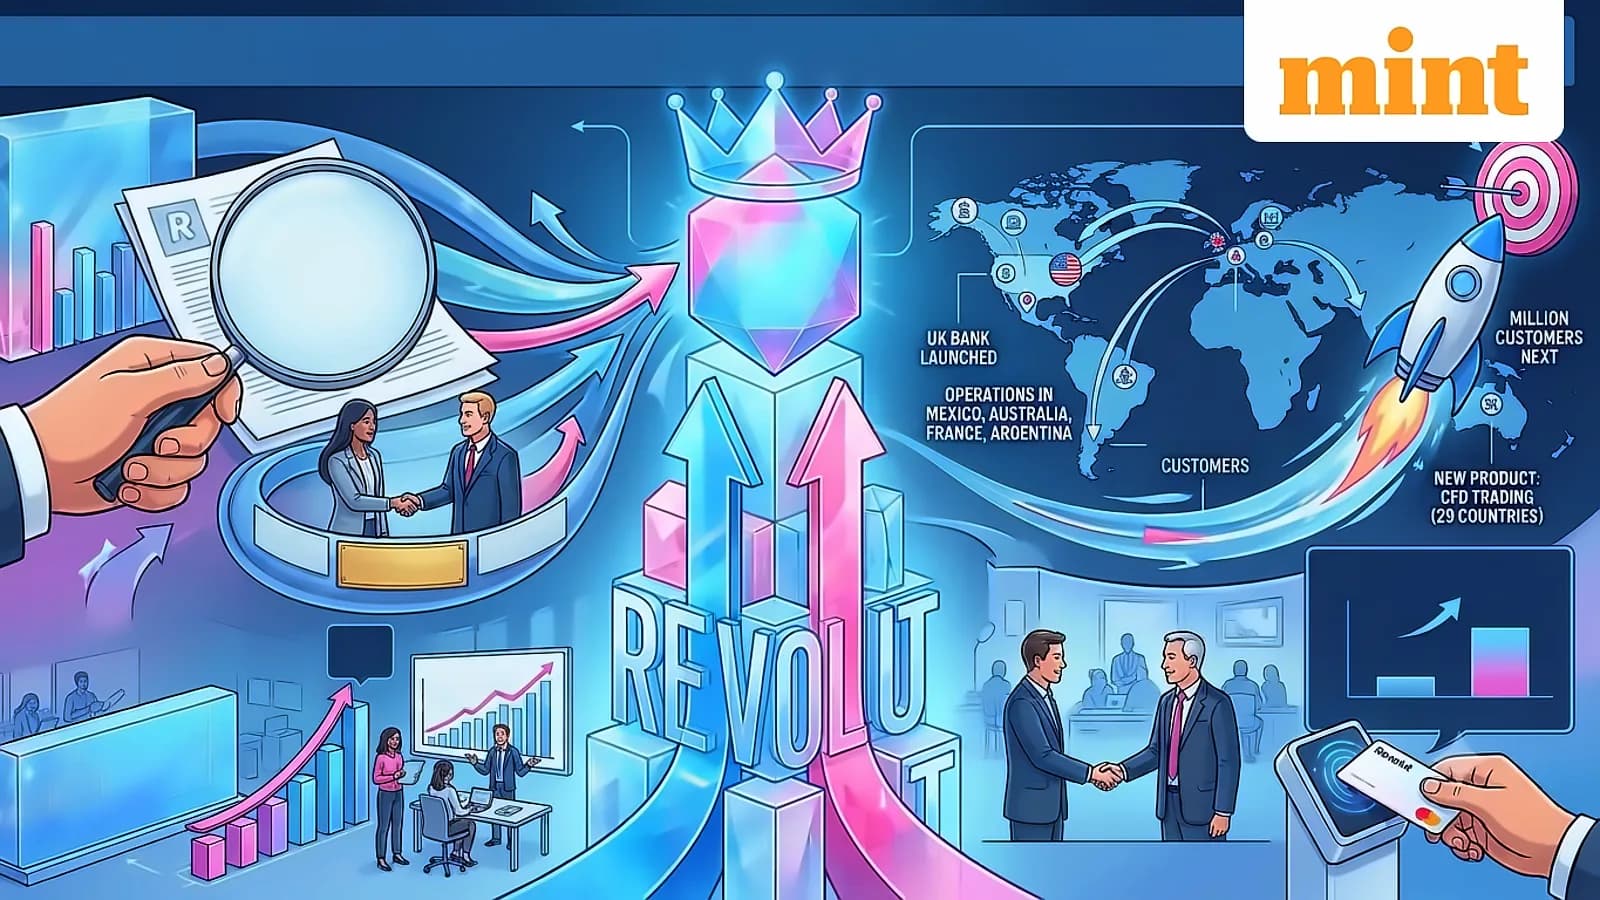
British fintech company Revolut Ltd. has closed its latest secondary share sale, confirming a valuation of $115 billion, marking a significant increase from its $75 billion valuation in its previous funding round completed less than a year ago. According to reports from Bloomberg, the transaction was led by Glade Brook Capital Partners, Coatue, Durable Capital Partners, accounts advised by T. Rowe Price Associates Inc. and Baillie Gifford. The secondary share sale, which began in July, allowed existing investors, including employees, to sell their holdings to other investors without the company issuing new shares.
CEO Nik Storonsky emphasized the importance of employee ownership in the company's culture, stating that the latest transaction provided employees with an opportunity to benefit from the value created by the business. As reported by Bloomberg, Storonsky noted that "Employee ownership has been central to our culture from day one. That's why we've once again given them the chance to share in the value they've created." The secondary sale provides liquidity to existing shareholders without requiring the company to raise fresh capital through new equity issuance.
The latest valuation increase comes as Revolut prepares to launch a US bank, marking a significant expansion of its financial services offerings. According to Bloomberg reports, Storonsky has previously indicated that he wants to take the company public, though a stock market listing is unlikely before 2028. The company is considering a dual listing in the United Kingdom and the United States, which would allow its shares to trade in both markets.
The company has entered the UK's unsecured personal lending market, offering loans ranging from £2,000 to £25,000 with interest rates starting at 6.9% and going up to 29.3%. As reported by Reuters, UK CEO Francesca Carlesi stated that the company wants to "transition from being a very successful everyday spending app and disrupting the market, to become effectively the primary bank of choice for everybody in the UK." The loans will initially be available to a selected group of customers before gradually expanding to the company's entire UK customer base of approximately 14 million over the coming months.
The expansion into UK consumer lending represents a shift beyond the company's traditional payments, money transfer and subscription-based offerings towards a riskier business that exposes lenders to potential defaults and credit losses. According to Reuters, Carlesi confirmed plans to introduce a credit card product in the near future as part of the company's strategy to compete more directly with traditional banks across multiple consumer banking segments. The entry into personal lending could help the fintech deepen relationships with existing customers while competing for a larger share of the country's retail banking business.