According to the latest regulatory filing, Patanjali Foods Ltd. reported a consolidated net profit of ₹420 crore for Q2 FY2026-27, marking a 46% year-on-year jump from the corresponding period of the previous fiscal. The company demonstrated strong revenue growth with total income rising 15.6% to ₹11,323 crore in the second quarter of the current fiscal from ₹9,799 crore a year ago. Of the total revenue from operations, the edible oil business contributed ₹8,532 crore with 22.4% growth, while the FMCG segment generated ₹2,923 crore with marginal increase, as per the latest disclosure. For the six-month period, the company achieved record revenue from operations of ₹22,660 crore, up 22.1% over the year-ago period, indicating sustained momentum in its diversified business portfolio.
Despite the strong profit growth, the company's operational efficiency showed pressure during the quarter. Earnings before interest, taxes, depreciation and amortisation (Ebitda) declined 22.9% to ₹426 crore from ₹552 crore in the preceding fiscal year. More concerning was the Ebitda margin contraction to 3.76% from 5.63% in the prior financial year, indicating deteriorating operational efficiency despite revenue growth. The company attributed this to inflationary pressures that increased during the quarter, with retail inflation rising from 4.45% in July to 5.54% in September, marking its highest level since the revised series began in January. Price pressures were particularly sharp in rural markets due to deficient monsoon and El Nino conditions, even as resilient non-farm rural activity continued to cushion household incomes.
Jefferies has retained its 'Buy' rating on Patanjali Foods with a price target of ₹550 per share, despite cutting earnings estimates following the mixed quarterly results. The brokerage has lowered its FY27 estimated earnings by 19%, factoring in the impact of import duties, and has also cut its FY28-FY29 earnings estimates by 4-6%. According to CNBC TV18, the stock market reflected investor concerns about the mixed financial results and margin pressure, with Patanjali Foods shares ending 2.27% lower at ₹421 on Friday. At current levels, the stock has declined around 24% so far in 2026, underperforming the broader market. Despite near-term earnings pressure, Jefferies expects a stronger second half of FY27, supported by festive and wedding-related demand, volume growth and improving profitability in the Foods business.
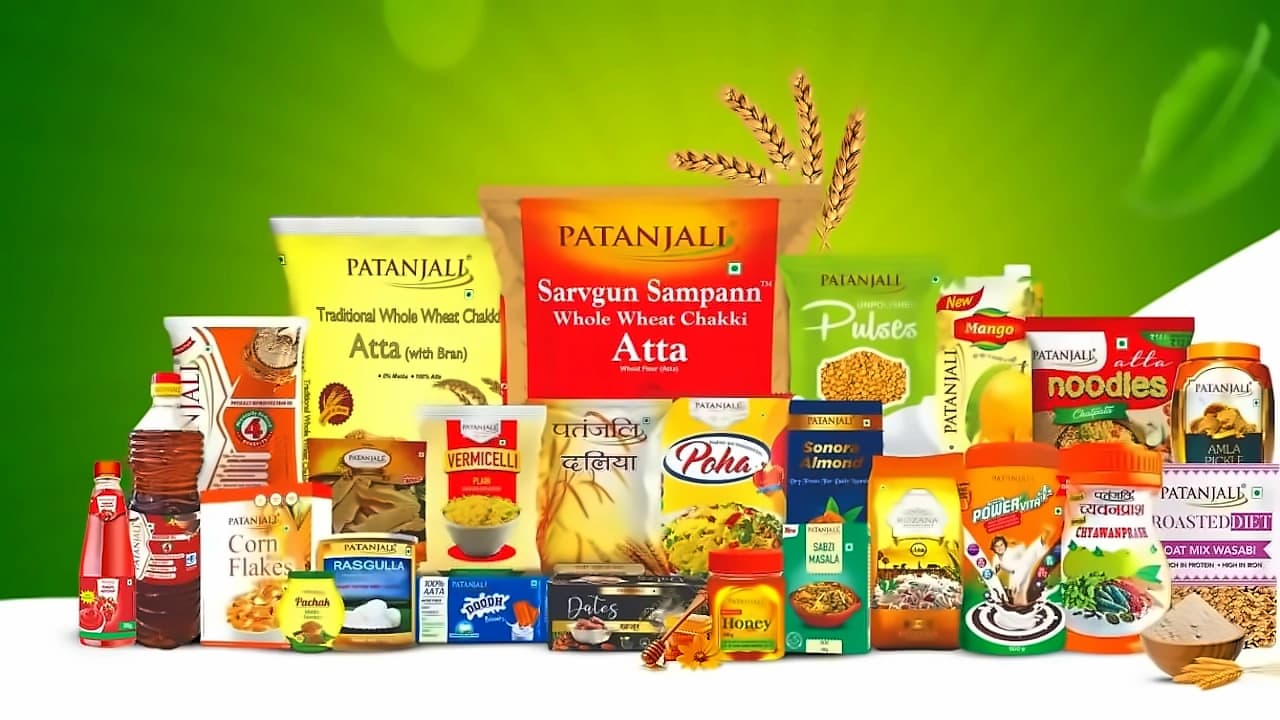
Sanjeev Asthana, Chief Executive Officer of Patanjali Foods, attributed the September quarter performance to the resilience of the company's integrated business model across branded edible oils, upstream oil palm plantations and growing FMCG portfolio. He noted that Doodh Biscuits, Nutrela, Saundarya and Dant Kanti sustained their growth trajectory, supported by the diversified portfolio and extensive distribution network. Asthana highlighted that the second quarter saw a shift in festive demand, with Navratri beginning in October this year compared to September last year, while Pitru Paksha in September deferred some festive-led purchases. Despite inflationary challenges, he expressed optimism about future growth momentum, stating that with the recent festive season and the upcoming wedding season, growth momentum is expected to continue.
The company pointed out that inflationary pressure increased significantly during the quarter, with food inflation standing at 7.7%, contributing to the overall price pressures. The demand environment remained supportive during the festive season, indicating healthy consumer momentum despite inflationary headwinds. Price pressures were particularly acute in rural markets due to deficient monsoon and El Nino conditions, even as resilient non-farm rural activity continued to cushion household incomes. The company expects its growth momentum to continue in light of the recent festive season and the upcoming wedding season, suggesting confidence in its ability to navigate current market challenges and capitalize on seasonal demand patterns.