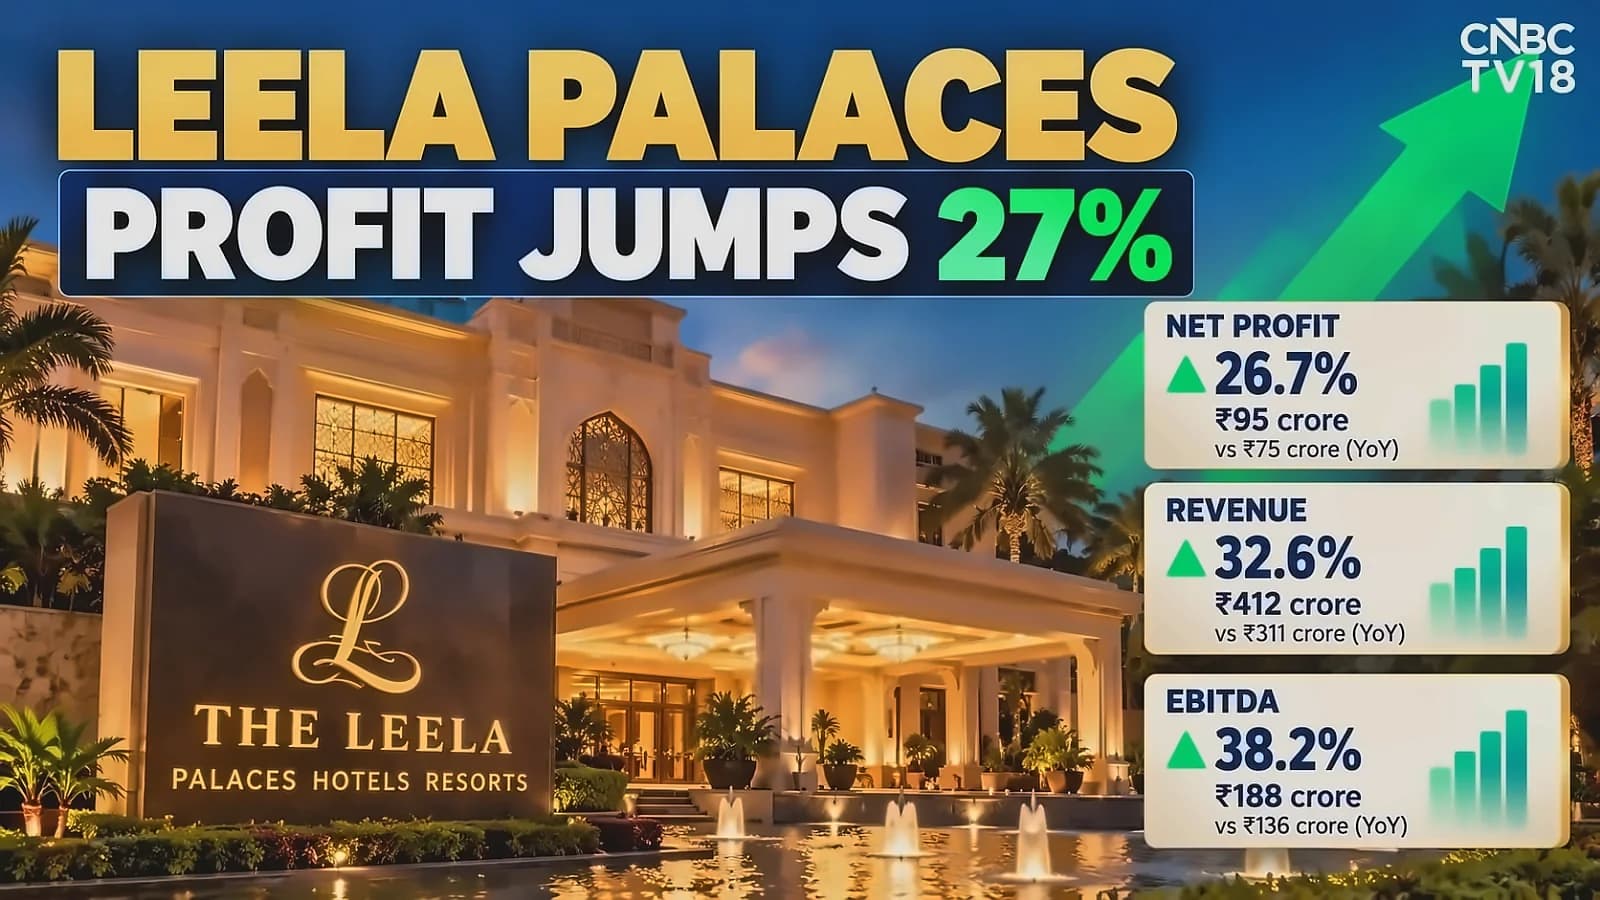
Leela Palaces Hotels & Resorts reported a 26.5% year-on-year rise in net profit for Q2FY27, reaching ₹94.6 crore from ₹74.7 crore in the previous year. According to the latest quarterly results announced on Wednesday, revenue surged 32.5% YoY to ₹412 crore from ₹311 crore in Q2 FY26. The company's operating EBITDA increased 36% to ₹188 crore, with EBITDA margin expanding to 45.6% from 44.4% in the corresponding period last year. Following the strong results announcement, shares of Leela Palaces Hotels rallied nearly 6% on Thursday, trading at ₹606 on the NSE, gaining around 2.5% after closing at ₹591.30 in the previous session. The stock has rallied over 40% in the last six months and surged more than 19.5% in the past month alone, with the company currently trading at a price-to-earnings multiple of 42.65 times and a market cap of ₹20,690 crore.
The company's strong performance was primarily driven by significant improvements in room rates and occupancy metrics. As reported in the latest results, revenue per available room (RevPAR) increased 30% YoY to ₹17,225 in Q2 FY27, while average daily rate (ADR) rose 30% to ₹25,046. India headline occupancy stood at 69%, compared with 68.7% in the year-ago quarter. Suite occupancy increased by over 700 basis points, reflecting continued premiumisation, while marquee events, including the BRICS Summit in Delhi, supported demand. Demand was broad-based across retail, corporate and leisure segments, with domestic revenue growing more than 30% across all segments. Jefferies analysts noted that the growth was entirely ARR-led, supported by favorable domestic travel tailwinds & strong MICE demand. For the first six months of FY27, operating revenue grew 30% and operating EBITDA grew 38%, with the margin expanding by 246 basis points.
Leela Palaces has raised its guidance and now expects high teens earnings before interest taxes depreciation and amortization (EBITDA) growth in the second half of FY27, implying mid-20% EBITDA growth for the full fiscal year 2027. According to management, demand is expected to benefit from international conferencing, leisure travel, weddings, and domestic tourism. Jefferies has raised its EBITDA and Profit After Tax (PAT) estimates for Leela Palace Hotels by 3% and 7% respectively, seeing it as a high-quality luxury hospitality play. Jefferies analysts continue to forecast 21-23% Revenue/EBITDA/PAT compound annual growth rate (CAGR) over FY26-29e, with EBITDA and PAT projected to grow at similar CAGR. Nomura has maintained its 'buy' rating with a target price of ₹650 per share, implying an upside of 10% from previous closing levels. All 21 analysts who have coverage on the stock have 'buy' ratings, with Jefferies raising its target price to ₹735 from ₹675 previously, projecting up to 24.3% upside potential.
According to the latest results, room revenue rose 39% YoY to ₹204.1 crore, while food and beverage revenue increased 21% to ₹145.6 crore. Hotel management agreement (HMA) fees grew 76% to ₹28.9 crore, reflecting the ramp-up of managed properties and wider brand footprint. Revenue from other operational services, including wellness, retail, club memberships and transport, rose 25% to ₹33.3 crore. The company noted that non-room revenue accounted for more than half of total revenue in the first half of FY27, highlighting its diversification efforts beyond accommodation. Jefferies analysts highlighted that the domestic segment witnessed over 30% revenue growth, with the company maintaining its strong performance across multiple revenue streams.
As reported in the latest results, Leela Palaces Hotels has a pipeline of 1,038 keys across 10 properties that are progressing on schedule. The upcoming properties span wildlife, heritage, hill station, desert and spiritual destinations. The Leela Jaisalmer and The Leela Luxury Residences in Mumbai are in the active pre-opening stage and are expected to start operations in FY27, marking the company's entry into a new business vertical. Jefferies analysts noted that the Jaisalmer hotel & Mumbai Luxury Residences remains on track for FY27 opening, while other Greenfield projects are scheduled across CY27 (Srinagar, Bandhavgarh), CY28 (Agra, Ayodhya, Ranthambore, Sikkim), & CY30 (Tadoba). The company's balance sheet remains well-positioned to support growth with net debt/EBITDA currently at 1.4x. JM Financial expects the stock re-rating to continue in the near term and retains Leela as their top pick in this space.