India's private equity market entered a disciplined phase in 2025, with total PE-VC investments declining approximately 17% to $36 billion, according to the India Private Equity Report 2026 by Bain & Company and the Indian Venture and Alternate Capital Association. Despite this moderation in value, deal volumes remained resilient, increasing by approximately 10%, indicating sustained investor interest despite a more cautious deployment approach. Average deal size declined roughly 25% year-over-year, reflecting a structural shift toward smaller check sizes driven by lower ownership stakes and fewer large buyouts. This disciplined approach was underpinned by tighter leverage conditions, persistent valuation gaps, and greater selectivity in underwriting, with capital increasingly spread across a broader set of opportunities.
India's private equity landscape is experiencing a significant transformation as investors pivot away from technology-focused investments toward more stable sectors. According to the India Private Equity Report 2026, consumer and retail investments surged 2.6 times year-on-year in 2025, while manufacturing and industrial investments rose around 55-60 per cent. In contrast, investment activity in Information Technology and IT-enabled services (IT/ITeS) declined nearly 30 per cent, and healthcare investments fell about 44 per cent. As reported by Business Standard, this shift reflects a broader movement toward "resilient, domestically anchored sectors" as investors move away from uncertainty linked to tariffs, global demand slowdowns, and prolonged cash burn. The Bain report indicates that investors are now prioritising operational improvement, governance upgrades, and buy-and-build strategies to generate returns rather than relying on leverage and valuation expansion.
The investment evolution represents a fundamental change in private equity fund evaluation criteria. According to CA Akshay Dawra, Fund Manager (Private Equity) at Chanakya Opportunities Fund-II, the shift is from "growth at any cost" to "quality growth with earnings visibility" and scalable cash flows. Kulmani Rana, Founder of venture platform Fibonacci X, noted that the transition has been building since 2023 and is tied to investor pressure for real cash returns. The DPI challenge, which measures how much money PE funds have returned to investors compared to capital invested, is driving this shift as older funds face pressure to deliver exits and real cash returns. This approach is exemplified by recent funding rounds where investors are backing companies with strong unit economics and sustainable business models, moving away from cash-burning businesses toward profitable ventures.
The consumer opportunity is expanding beyond traditional metropolitan markets, fundamentally changing how brands scale across India. According to Siddharth Purohit, Fund Manager-Equity at Invest Value Capital Pvt Ltd, the rapid rise of quick commerce and e-commerce has significantly accelerated consumer brand penetration. Post-pandemic, there has been a dramatic shift in consumer behaviour, with customers increasingly willing to experiment with newer brands unlike earlier when established names commanded natural premiums. The trend is spreading strongly across Tier II and Tier III cities, with categories such as beauty care, wellness, luggage, footwear, premium food, and lifestyle products seeing new-age brands emerge rapidly and challenge legacy players. Food and beverage brands, quick-service restaurants, cafes, electronics, and fashion were among the biggest magnets for PE capital in 2025, with the massive private equity deal involving Haldiram Snacks Food Pvt. Ltd. signalling strong investor interest in iconic regional brands. Packaged snacks are becoming an increasingly important growth engine for FMCG companies amid shifting consumer preferences, with brands such as Lay's, Kurkure, and Quaker Oats remaining key contributors to sustained growth.
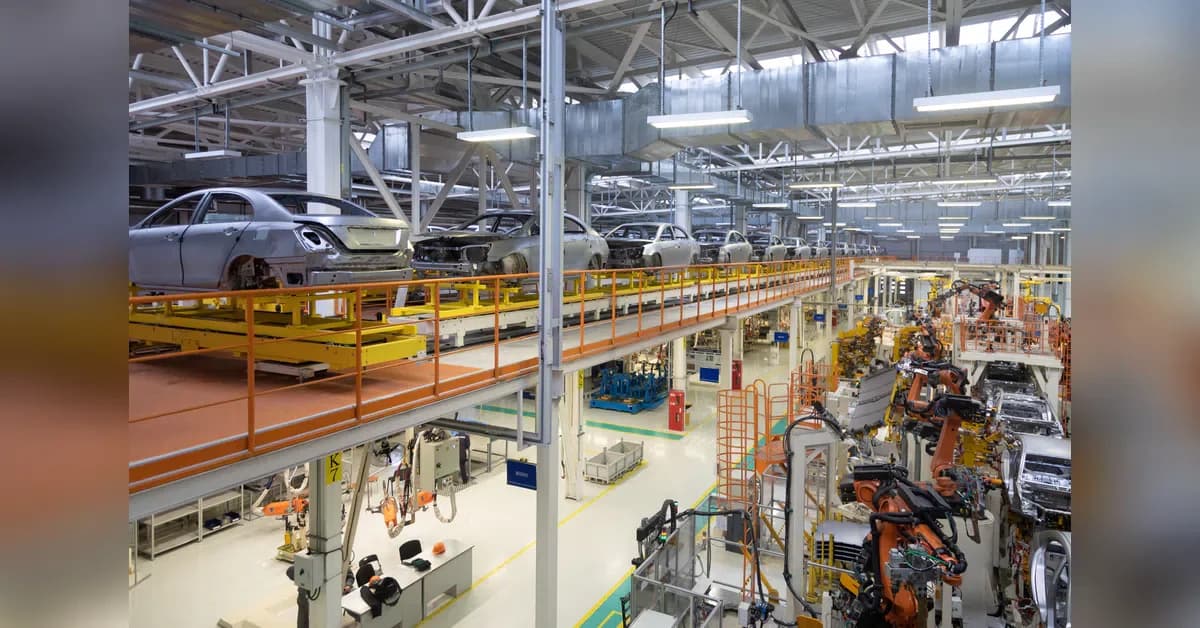
The manufacturing boom is being powered by a combination of geopolitical shifts, supply-chain diversification, and policy support. According to Purohit, changing geopolitical equations and supply chain realignments have altered India's perception as a serious global manufacturing alternative. The Bain report highlights that investors are increasingly favouring manufacturing due to global supply-chain realignment, production-linked incentive (PLI) schemes, rising infrastructure spending, localisation push, and increasing value-added manufacturing. Dawra noted that electronics exports crossed ₹48 billion in FY26, reflecting the scale-up opportunity investors are pursuing. Sectors such as electric mobility, electronics manufacturing, semiconductors, aerospace, and industrial platforms are attracting strong investor attention, with the common thread being exportability with domestic demand as a floor.
Growing investor caution around traditional technology bets is driving the shift toward more stable sectors. According to Dawra, tariffs, geopolitical tensions, supply-chain disruptions and higher interest rates have reduced investors' appetite for long-gestation, cash-burning businesses. While several Indian startups have built strong visibility and revenue growth, persistent cash burn remains a concern for many investors. However, Rana cautioned against reading too much into the decline in IT/ITeS investments alone, noting that the sector experienced a 300 per cent surge the previous year due to one-time mega-deals. Experts believe this move toward consumer and manufacturing is more structural than temporary, with India set to overtake Japan as the third-largest consumer market this year and PLI producing exportable scale in mobile phones and electronics.