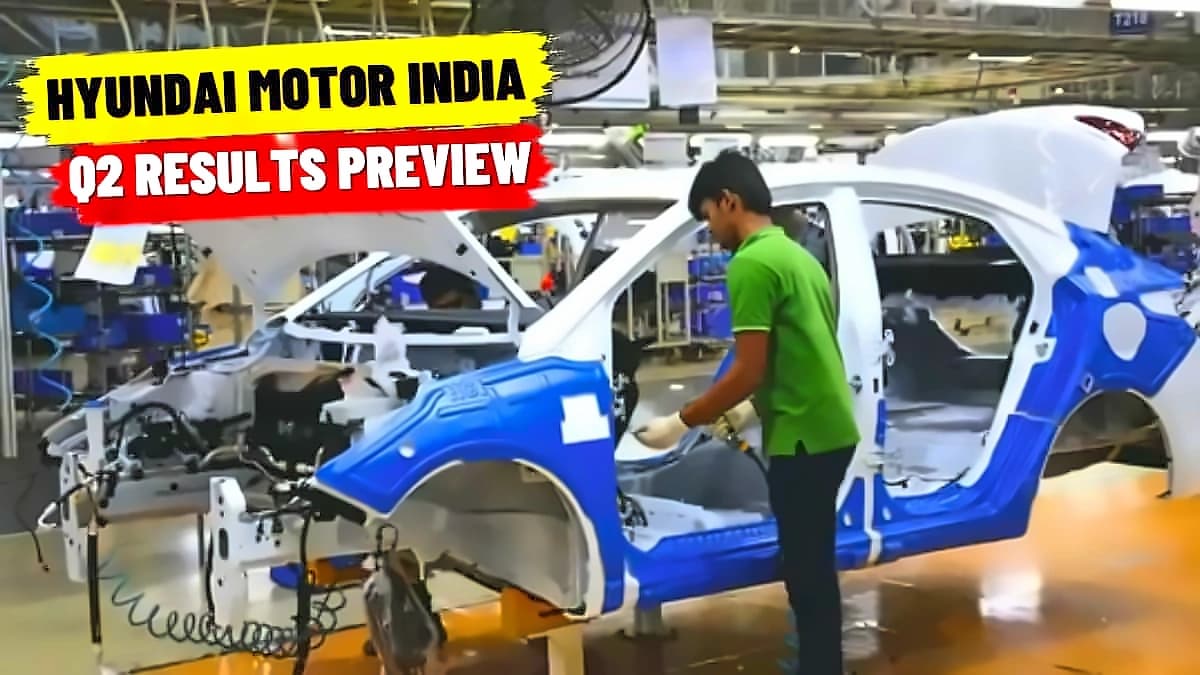
According to Zee Business research, Hyundai Motor India is expected to log a 21.2% year-on-year fall in consolidated net profit to ₹1,239 crore for the quarter ended September 30. The carmaker's top-line is estimated to increase 17% on year to ₹20,422 crore, indicating strong revenue growth despite profitability challenges. However, analysts anticipate the company will face significant margin pressure due to elevated input costs despite achieving double-digit volume growth.
The company's EBITDA is expected to fall 18.3% year-on-year to ₹1,986 crore with a 420-basis-point fall in margin to 9.7%. As reported by Zee Business, analysts expect commodity headwinds and plant startup costs to put pressure on the company's margins. Despite these challenges, Hyundai Motor India is anticipated to register volume growth of 14.7% to 21.9 lakh units, with realisations expected to remain steady during the quarter.
According to market data, Hyundai Motor India shares declined 0.4% to close at ₹1,861.3 on NSE on Tuesday. The stock has lost 19.5% of its value so far this year, underperforming the Nifty 50's loss of 13% and Nifty Auto's decline of 10.1%. As reported by Zee Business, the stock has underperformed key indices over the past year, with a -18.1% decline compared to Nifty 50's -12.4% and Nifty Auto's -7.1% performance.
According to Zee Business, investors will closely monitor management commentary on three key aspects: launch pipeline, demand trends, and the Pune plant rampup. Hyundai Motor India has inaugurated its third car-manufacturing facility in the country at Talegaon, near Pune, with an initial annual capacity of 1,70,000 vehicles. The company plans to expand the Pune capacity in phases to 3,20,000 units annually by 2030. AI-powered market intelligence platform Kwala Intel advises a 'wait and watch' approach on the stock, citing the absence of a clean setup.