Finolex Cables has delivered a remarkable 60% rally in 2026, positioning the stock for continued growth according to Jefferies analysts. Despite this strong performance, the stock trades at around 21x one-year forward PE, which Jefferies considers a notable discount to peers. Analysts Sonali Salgaonkar and Saurabh Kulkarni have retained their 'Buy' rating on the stock with a target price of ₹1,410, valuing the company at around 23x forward PE, a 15% premium to its five-year historical average.
The biggest change in Finolex Cables' earnings profile is coming from its communication business, which is around 75% optic fibre cable (OFC). According to Jefferies analysis, the segment's EBIT margin jumped to around 30% in the June 2026 quarter from just 1% a year earlier, making communication around 23% of the company's quarterly EBIT despite accounting for only about 9% of sales. This transformation has been driven by a sharp rise in optic fibre prices, with standard fibre prices climbing from around $5–6 per km in December 2025 to $17–18 per km by mid-2026, driven by AI-related demand. Prices now appear to be settling around $11–13 per km, still roughly twice their level at the start of the year. Jefferies cautions that fibre prices could eventually normalise as demand settles and older, lower-cost raw-material inventory gets exhausted, but for now, the price environment is providing a major lift to margins.
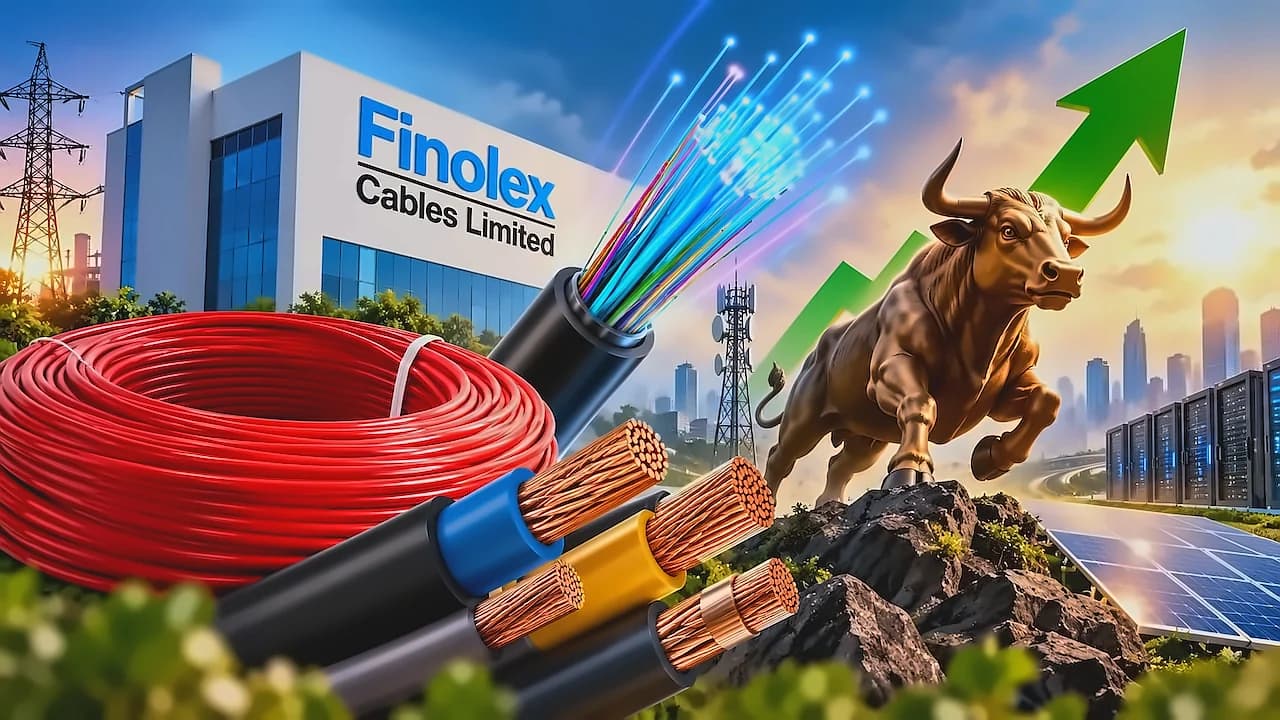
Finolex is targeting a doubling of its fibre-draw capacity to 8 million km by December 2026, or Q3FY27E. At an assumed fibre price of around $11 per km, Jefferies estimates the expanded capacity could generate quarterly sales of around ₹200-250 crore, equivalent to roughly 11% of FY28E revenue. Higher-value products and better design could push this potential towards ₹3 billion per quarter. Jefferies expects communication revenue to rise 27% year-on-year in FY27E, with overall sales projected to grow at around 15% CAGR through FY26–29E. The brokerage estimates Finolex Cables' sales and EBITDA to compound at 17% and 22% respectively between FY26 and FY29E.
Despite the OFC opportunity, Finolex remains primarily an electricals company, with the segment accounting for around 85% of total sales. Construction wires make up roughly 65% of electricals, while auto, agricultural and industrial cables contribute around 10% each. Jefferies sees further growth even without major new investments, with capacity utilisation potentially increasing from around 66% in FY26 to 80–85%, potentially supporting around 15% additional sales growth. The brokerage estimates electricals revenue will grow at around 17% CAGR over FY26–29E. Jefferies expects growth to normalise thereafter in the communication segment after the current surge.
Finolex's newer businesses are beginning to contribute meaningfully to growth. The company launched solar cables last year and has ordered a second e-beam line, which could double capacity. Its EHV cable joint venture with Sumitomo Electric posted ₹24 crore profit in FY26, while June-quarter sales and profit stood at ₹87 crore and ₹7 crore, respectively. The EHV JV has an order book of around ₹300 crore and supplies cables up to 500kV. Demand is currently strongest in the 66–110kV range, with 220kV demand also increasing. Exports remain relatively small at around ₹50 crore in Q1, but around ₹30-40 crore came from OFC exports to the US and Europe, with export margins higher than domestic margins. Jefferies notes that export margins are higher than domestic margins, adding another potential benefit as the OFC business scales.