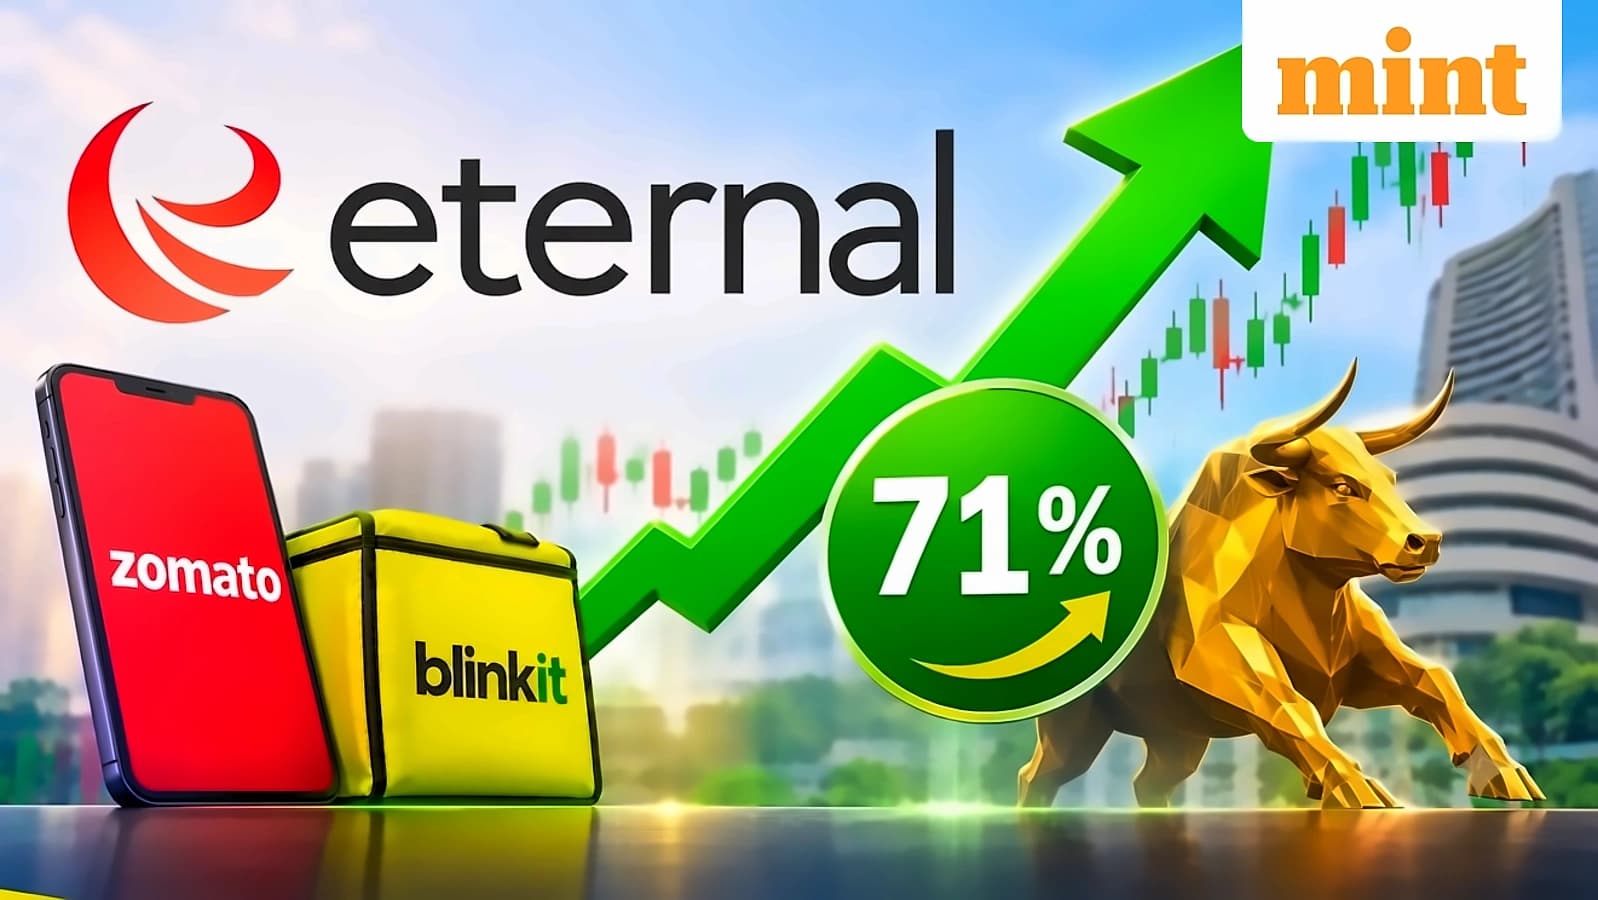
Eternal shares have rebounded 71% from their March low of ₹212.60, closing at ₹364 and emerging as the biggest recovery story among Nifty constituents in 2026. According to reports from LiveMint, the stock began the year on a tepid note, closing the first three months in the red, but turned fortunes in April with the rally strengthening each subsequent month. The sharp turnaround has been driven by improving investor sentiment towards the company's quick commerce business execution and reflected in September quarter earnings.
Blinkit's net order value surged 79.3% year-on-year to ₹20,940 crore in Q2 FY27, while the business reported an adjusted EBITDA profit of ₹184 crore, marking its sixth consecutive quarter of margin improvement. As reported by LiveMint, Eternal plans to expand Blinkit's network to more than 3,500 stores by March 2027 and around 5,000 by March 2028, from 2,751 stores at the end of September. The company added 308 net new stores during the September quarter, with significant portion of new additions expected from smaller cities.
Eternal reported a consolidated net profit of ₹125 crore in the September quarter, nearly doubling from ₹65 crore in the year-ago period, supported by the rapid scaling of its quick-commerce business. According to LiveMint, the company expects growth in Blinkit to accelerate from the December quarter as it bets on a more stable competitive environment to expand its network faster without compromising margins. Chief Financial Officer Akshant Goyal stated that there would be no short-term margin reduction on account of accelerated store addition.
Eternal now trades at ₹364 from the start of the year, with bearish analysts on Simply Wall St seeing its Fair Value below that level. The valuation concerns center on store economics, working capital demands and fresh AI spending behind current expectations. The main challenge for investors is maintaining customer retention and order frequency in food delivery and quick commerce while funding higher inventory, store build costs and new AI products. Key risks include Eternal's push into smaller cities, larger dark stores and higher per store CapEx keeping investment heavy while exposing margins to volatile throughput and working capital needs.
While Eternal has been winning back investors' confidence, its close peer Swiggy is facing deep trouble with shares crashing 51% in less than 11 months, adding to the 29% decline recorded in 2025. According to LiveMint, this highlights the contrasting fortunes of two companies operating in the same business, with Eternal staging a strong recovery while Swiggy continues to struggle. The divergent performance reflects the market's appreciation for Eternal's execution in its quick commerce business and improving profitability across segments.