Dhoot Transmission shares fell for the fourth consecutive session on Monday, September 28, with the stock opening lower and remaining in the red despite recovering some early losses. According to CNBC TV18, Kotak Institutional Equities has initiated coverage with a 'Sell' recommendation and a price target of ₹1,400 per share, implying a further downside of 10% from the stock's last closing level on Friday. The brokerage warns that Dhoot Transmission's current valuation already reflects these growth prospects, limiting the scope for further upside. The stock's recent decline reflects investor concerns about the company's premium valuation despite strong fundamentals.
Dhoot Transmission is strategically expanding beyond its core wiring harness business as rising electric vehicle penetration increases the amount of electrical content supplied per vehicle. The company is adding battery packs, electronic controllers, sensors, chargers and other components, while using the acquisition of Multilink and new manufacturing capacity to support growth. According to reports from NDTV Profit, EV-related sales accounted for 27% of revenue in Q1FY27, up from 24% in FY26, while revenue from non-wiring products rose 67.7% year over year to ₹358 crore. The company's non-wiring portfolio includes battery pack assemblies, electronic controllers, switches, sensors, chargers, connectors and plugs, with battery pack assembly being the largest business within this segment. Battery pack sales grew 81% year over year and 25% quarter over quarter in Q1FY27, with the company supplying all of Bajaj Auto's battery pack assembly requirements for the Chetak electric two-wheeler.
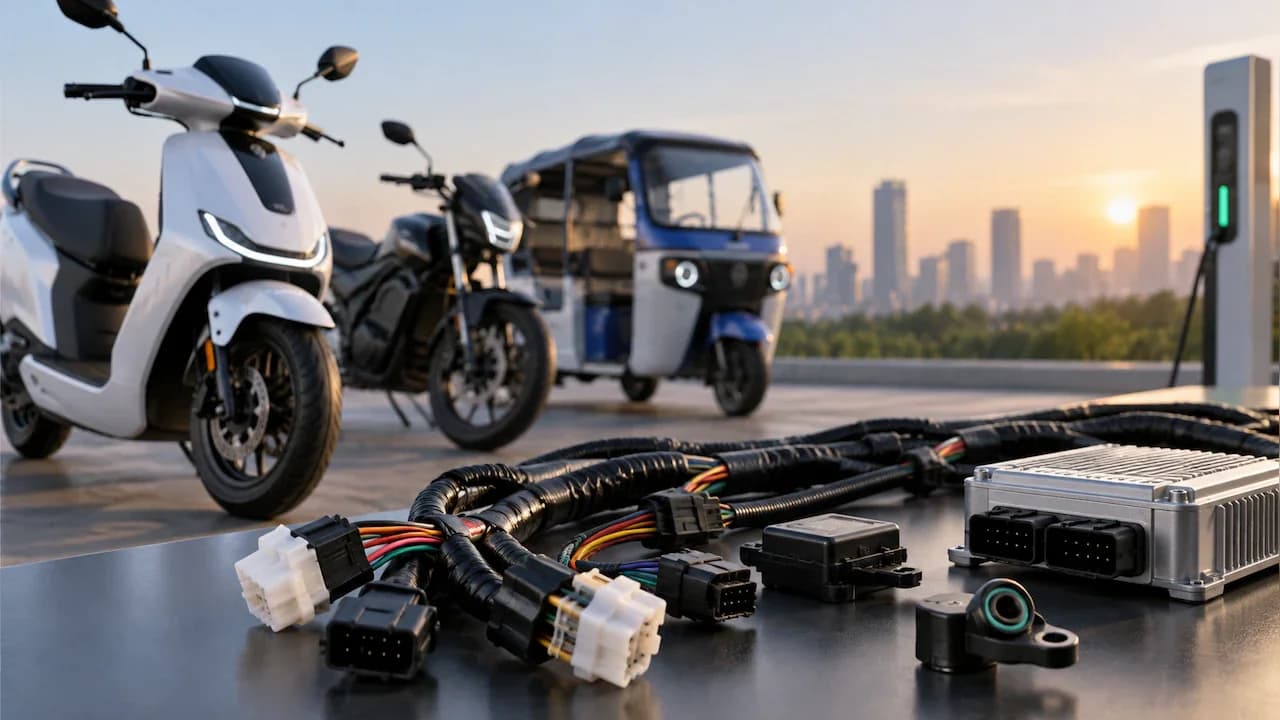
Wiring harnesses remain the main source of revenue for Dhoot Transmission, with the company generating ₹3,484 crore from wiring harnesses in FY26, or 77% of total revenue. As reported by NDTV Profit, the company has a 41% share of the domestic two-wheeler and three-wheeler wiring harness market and about 70% of the electric two-wheeler and three-wheeler wiring business. Two-wheelers accounted for 65% of FY26 revenue and three-wheelers for 13%, while commercial vehicles, off-highway equipment and non-auto businesses contributed the remaining 22%. The company's customers include Bajaj Auto (32% of FY26 revenue), TVS Motor (20%), Honda (11%), Suzuki, Royal Enfield, Ather and Hero Electric, with the five largest customers accounting for 71% of Q1FY27 revenue. The company also remains heavily dependent on the domestic market, which contributed 92% of revenue in Q1FY27.
The larger opportunity comes from the increase in electrical content as vehicles shift from internal combustion engines to electric powertrains. According to NDTV Profit, wiring harness content has already increased 2.5 to 3.5 times between BS-IV and BS-VI vehicles, with Ambit estimating that wiring harness content could rise from about ₹1,800-1,900 in BS-VI models to ₹4,000-5,000 in electric two-wheelers. Kotak Institutional Equities expects Dhoot Transmission's revenue and EBITDA to grow at a 23% CAGR each over FY26-29E, driven by 17% growth in wiring-harness revenue and 50% growth in EV components. EV revenue rose 79.2% year over year to ₹390.5 crore in Q1FY27 and accounted for 27% of total revenue, while internal combustion engine-related revenue still accounted for 63%, leaving scope for the EV share to increase as the market shifts. About 95% of its auto product portfolio is either EV-focused or powertrain-neutral, positioning the company well for the electric mobility transition.
The acquisition of Multilink provides Dhoot Transmission with another route to expand its product portfolio and customer base. As reported by NDTV Profit, Multilink has an annual revenue run rate of about ₹450 crore and an EBITDA margin of around 20%, implying annual EBITDA of roughly ₹90 crore at the current run rate. The acquisition adds relays and fuel level sensors to the company's portfolio and provides vendor-code access to Hero MotoCorp, Ola Electric, River Mobility and Greaves Electric. Management expects operational integration to be completed within three to four months and is targeting 25% to 30% annual revenue growth from the acquired product portfolio. The company is also pursuing backward integration by manufacturing connectors, terminals, switches and sensors internally, which could reduce import dependence and support margins. Management expects the EBITDA margin of the acquired Multilink business to move towards Dhoot Transmission's overall margin, with integration expected by the end of Q3 or early Q4 FY27.
Dhoot Transmission entered FY27 with strong financial performance, with revenue from operations rising 49.7% year over year to ₹1,446.4 crore in Q1FY27. As reported by NDTV Profit, EBITDA increased 29% to ₹218.4 crore with a margin of 15.1%, while net profit rose 37.8% to ₹132.7 crore, helped by a 34% decline in finance costs. The company is targeting 25% to 30% revenue growth in FY27 and expects margins to remain above 15%. Capacity additions are another key growth driver, with utilisation in the core wiring harness business increasing to 74% in FY26 from 64% in FY25, and new manufacturing units expected to increase total wiring harness capacity by 15% to 20% during the current financial year. At 73x earnings, the company trades at a higher multiple than Samvardhana Motherson at 38x, Uno Minda at 61x and Sona BLW at 65x, making its earnings growth trajectory a key factor for stock performance. The earnings trajectory will depend on how quickly EV volumes, battery packs, non-wiring products and the acquired Multilink business scale within the overall revenue mix.