Container Corp. of India Ltd's (Concor) shares surged over 6% to a seven-week high of ₹492 following its June quarter (Q1FY27) business update that showed volume growth of 9% year-on-year, ahead of Street estimates. According to reports from Informist Media, the state-owned rail-based container logistics company demonstrated resilience despite trade headwinds, with export-import (Exim) cargo growing 10%, above management's guidance of 8% for FY27. The brokerage Nuvama Wealth Management had estimated a 6% decline in total handling volume, making Concor's actual performance a significant beat.
While trade with West Asia was impacted by conflict, higher volumes from other regions, including the US and Europe, more than offset these challenges. As reported by Informist Media, Exim cargo formed over three-fourths of Concor's total volumes at 1.4 million twenty-foot equivalent units (TEUs) in Q1FY27. However, domestic volume growth was slower at 6%, notably short of the 15% guidance, though management expects improvement as road freight rates have risen after diesel price hikes, potentially shifting cargo from road to rail. The company's export-import handling volumes rose nearly 10% year-on-year to 1.07 million TEUs, while domestic throughput rose over 6% to 335,739 TEUs, both exceeding Nuvama's estimates.
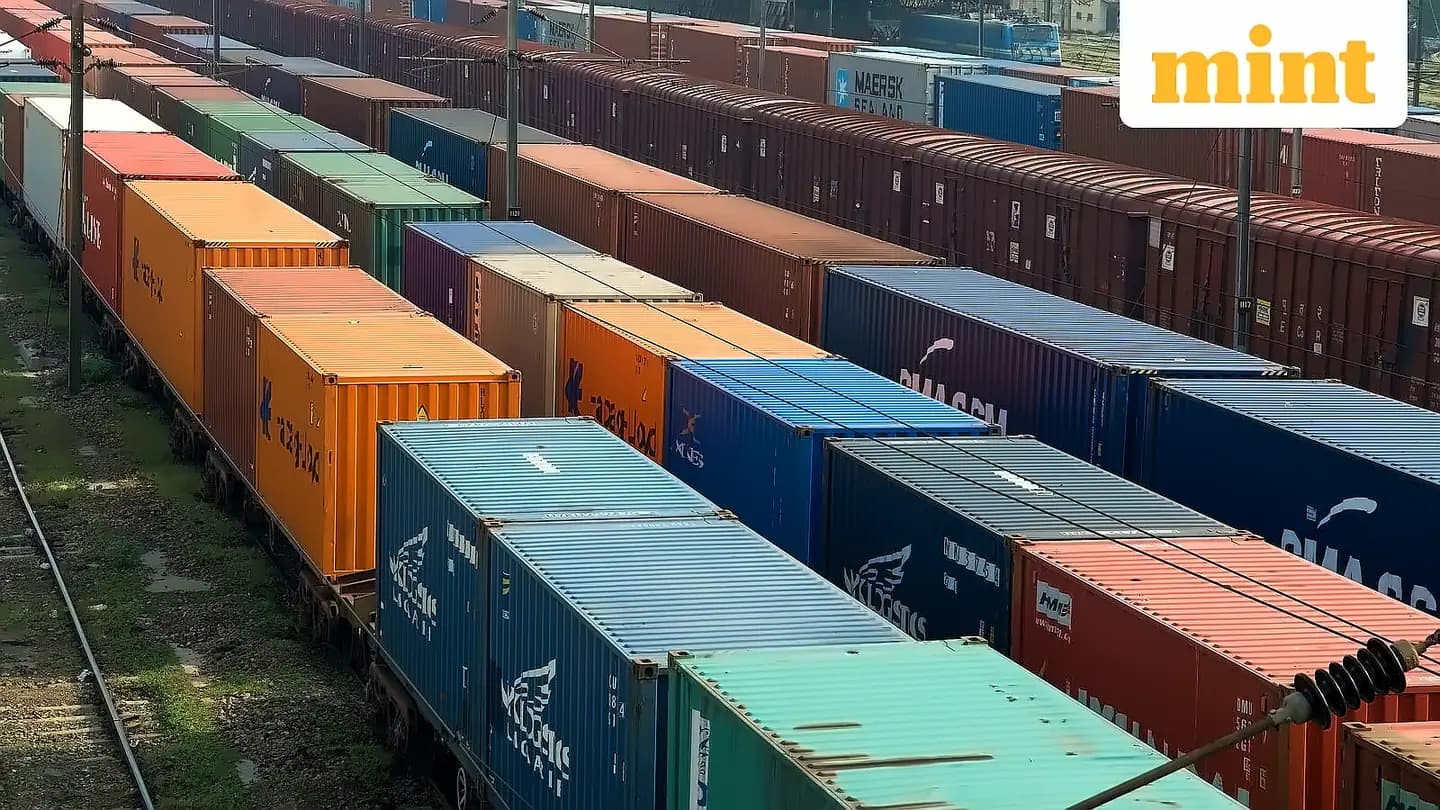
According to Informist Media, the growth in volume implied strong market share gains for the company, with Nuvama projecting a 200-250 basis points market share gain for the June quarter. The brokerage expects Container Corp. to see a two-four percentage point gain on its export-import handling volumes in the medium term as it has started operations across the Jawaharlal Nehru Port Authority to the Western Dedicated Freight Corridor. Given Concor's dominant market share of ~60% at JNPA in FY26 and JNPA contributing over 33% of CCRI's total EXIM volume, the DFC connection will provide a significant boost to the company's volume trajectory from Q3 onwards.
Despite strong volume growth, Concor's recent financial performance has been subpar, with Ebitda falling 3% year-on-year in Q4FY26 to ₹420 crore, despite 6% volume growth, as reported by Stock Market News. The decline was attributed to lower realisations, highlighting the company's margin pressure despite operational improvements. Nuvama highlighted that the company's management indicated it would revisit the guidance after monitoring demand trends over the next quarter, with the recently announced mega deals having a negligible revenue contribution in FY27.
All five brokerage reports on the company available with Informist have a 'buy' rating on the stock with an average target price of ₹572, implying significant upside potential. The WDFC commissioning is expected to significantly enhance Concor's growth prospects, with the rail line connecting Dadri to JNPT improving connectivity to north India's business hub. The DFC is projected to increase the share of cargo coming to JNPT through rail from 15% in FY26 to 18-19% in FY27 and 30-35% in three years, as reported by Stock Market News. This infrastructure development, combined with the uptick expected from WDFC's JNPT linkage, may help Concor deliver stronger Exim growth in FY27 versus its guidance.