Bajaj Consumer Care delivered exceptional financial results in Q2 FY27, with consolidated net profit rising 67% year-on-year to ₹70.2 crore from ₹42.3 crore in the corresponding quarter last year. According to The Economic Times, revenue from operations increased 25.4% to ₹332.8 crore in the quarter ended September from ₹265.3 crore a year earlier. The company's earnings before interest, tax, depreciation and amortisation (Ebitda) rose 71% to ₹83.3 crore from ₹48.7 crore, demonstrating robust operational performance across all business segments. For the first half of FY27, profit after tax jumped 74.8% to ₹140.9 crore from ₹80.6 crore in H1FY26, while revenue rose 25.2% to ₹674.3 crore from ₹538.6 crore. As per Moneycontrol, Q2FY27 revenue of ₹3,328 million was in line with estimates of ₹3,310 million, driven by double-digit unit volume growth in Almond Drops Hair Oil (ADHO).
The company achieved significant margin improvement with Ebitda margin expanding to 24.7% from 18.1% in the corresponding quarter last year, reflecting an improvement of 660 basis points. As reported by The Economic Times, this substantial margin expansion indicates enhanced operational efficiency and cost management across the company's portfolio. According to Moneycontrol, EBITDA margin expanded 670 basis points YoY to 24.7%, primarily aided by lower A&SP spends at 12.5% of sales versus 14.7% in Q2FY26. The strong profitability growth was supported by revenue growth and improved operating profitability across domestic and international markets.
Bajaj Consumer Care's domestic business continued to deliver robust growth with revenue rising more than 30% in both Q2 FY27 and the first half of the financial year. According to The Economic Times, Price Point Packs continued to outperform the overall portfolio and remained a key growth driver, with the company introducing a new integrated campaign with revised positioning towards the end of the quarter. General Trade sustained its momentum, delivering mid-twenties YoY growth in Q2FY27, with rural markets edging ahead of urban markets during the quarter, both recording robust and closely matched growth. Organised Trade delivered high-twenties growth in Q2FY27, building on the previous quarter's momentum and growing ahead of General Trade. E-commerce and Modern Trade continued to report broad-based growth across customers and sub-channels, with quick commerce remaining the fastest-growing channel.
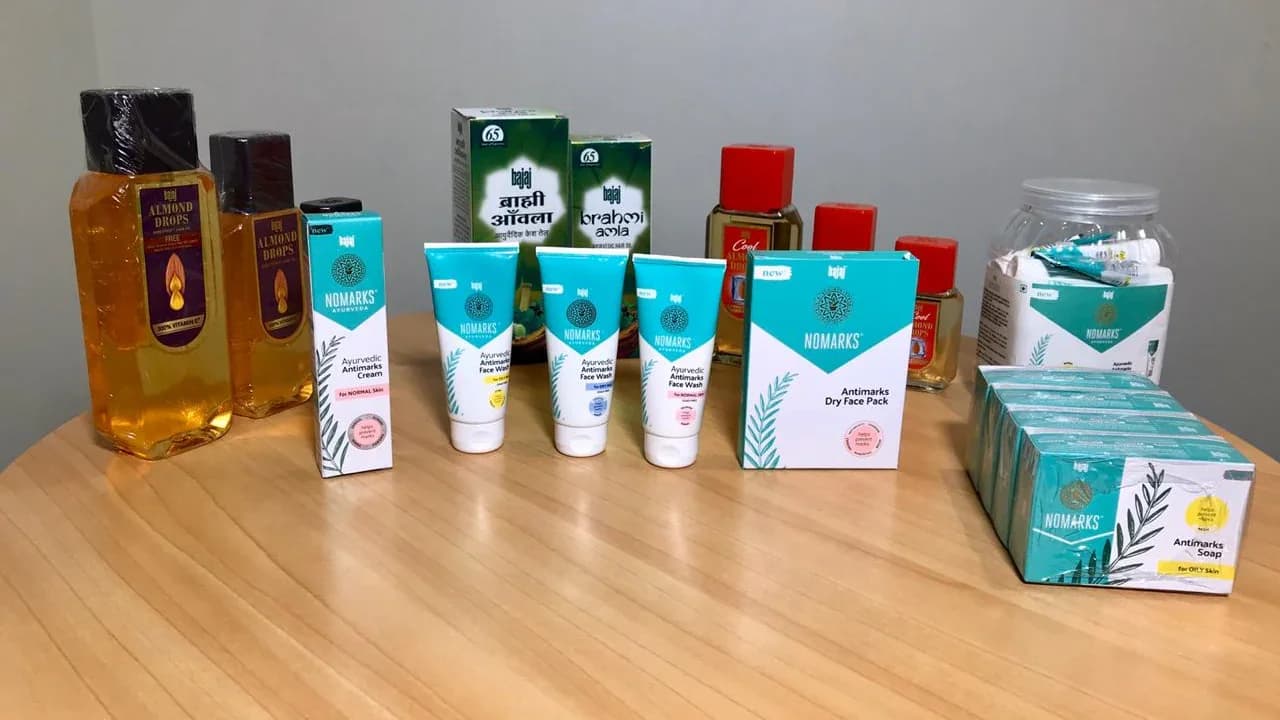
The company's Growth Portfolio sustained its strong momentum, continuing to scale up while improving profitability. As reported by The Economic Times, the coconut portfolio remained the key growth engine, supported by healthy consumer and trade traction, with volume growth significantly ahead of revenue growth amid deflation in coconut prices. The company is continuing to refine its portfolio through the revamp of select brands and introduction of new products, which are being piloted in select markets and channels. Almond Drops Hair Oil (ADHO) domestic business continued its robust momentum, delivering revenue growth of more than 30% in Q2 FY27 and in H1 FY27, supported by strong double-digit unit volume growth. ADHO's Liquid Under Pump (LUP) segment, representing approximately 20% of the portfolio, continued to drive strong growth with the company expanding distribution reach. According to Moneycontrol, the company maintains a constructive view supported by healthy growth momentum in ADHO and non-ADHO portfolios.
The company faced significant commodity cost pressures during Q2 FY27, with elevated raw material prices impacting margins across key products. According to the latest regulatory filing, light liquid paraffin (LLP) prices continued to be high due to the ongoing West Asia conflict and higher global freight costs. Refined mustard oil (RMO) prices were also elevated, in line with price hikes in other edible oils as the Middle East conflict disrupted oilseed supply chains. Copra prices rose in Q2 in anticipation of the impact of El Niño in Q3, with a broader rise in the edible oil basket pushing rates higher. To mitigate these challenges, Choice Institutional Equities reports that BAJAJCON plans to implement another round of price hike in Q3FY27, amounting to ~5% at the consumer price level, comprising a 2-3% price increase and the remainder through grammage reduction. The company has also shifted to a short and lean raw material procurement strategy and plans to further rationalise non-media spends to protect EBITDA margins.
ICICI Securities has maintained its BUY rating on Bajaj Consumer Care with a target price of ₹760, implying an upside of 46% from the current market price of ₹520. As per the latest report dated October 15, 2026, the target price is based on DCF methodology with an implied P/E of 29.4x Sep-28E EPS and PEG of 2.2. The brokerage's positive outlook is supported by double-digit volume growth, margin expansion and wider distribution. Management has maintained its high teen revenue growth outlook for FY27 and reiterated its long-term EBITDA margin guidance in the low-to-mid-20% range. According to Moneycontrol, we broadly maintain our estimates for FY27/28 and model revenue/EBITDA/PAT CAGR of 16%/33%/33% over FY26-28E, respectively. Despite raw material price volatility remaining at elevated levels, the company's cost-saving initiatives and operating leverage helped EBITDA margins exceed expectations.