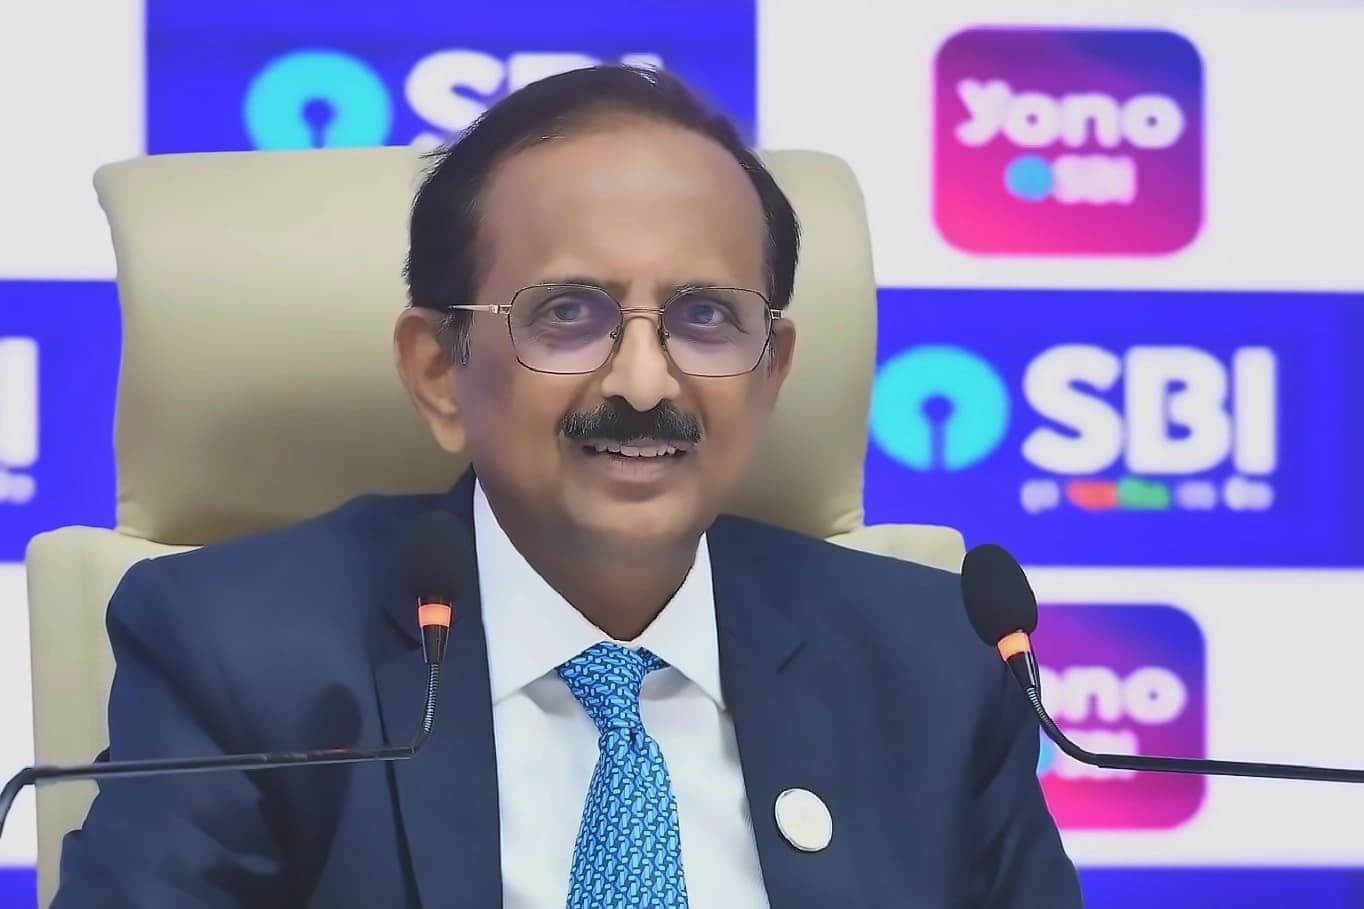
State Bank of India Chairman C S Setty announced on Thursday that deposit rates are unlikely to increase for the next 2-3 months due to excess liquidity in the banking system. Speaking in an interaction with The Hindu BusinessLine, Setty stated that the shift to tightening rates by the central bank will help banks expand their net interest margins (NIMs) for up to three quarters. He told reporters that "I believe that next two-three months, there may not be any rate action on the deposits because we have sufficient liquidity in the system." He acknowledged that if credit growth continues at elevated levels, some banks may need to raise deposit rates to fund advances, but emphasized that the current liquidity situation supports rate stability. Bankers expect this liquidity situation to change by the end of December, with Alok Singh, head of treasury at CSB Bank, noting that "there is little scope for deposit rates and non repo linked lending rates to move now."
SBI's largest lender will maintain its loan book expansion at 14-15% rate, as reported by The Economic Times. Setty explained that the bank believes credit growth should be 2-3% above nominal GDP, with nominal GDP at 12% supporting the sustained 14-15% growth rate. He dismissed concerns about imprudent lending practices, stating that the nearly $133 billion deposit raise from the diaspora will be absorbed within 2-3 quarters through RBI's liquidity management measures. Setty noted that while there is no ideal credit growth rate, "at least in SBI, we believe that you have to be 2-3 per cent more than the nominal GDP." He clarified that the current growth rates of 18-19% are on a low base and will eventually moderate to sustainable levels aligned with economic growth.
Setty addressed concerns about the central bank's directive for banks to be prudent in deploying FCNR(B) funds, stating that these concerns are "somewhat overplayed for two reasons." First, he explained that the liquidity arising from FCNR(B) deposits will probably be available for only two to three quarters. Second, the RBI is taking measures to absorb this excess liquidity, combined with demand for credit growth, will ensure "neither exuberance nor imprudence in lending." He emphasized that the FCNR(B) deposits will be available for only two to three quarters, after which the RBI's liquidity absorption measures will ensure proper deployment of funds. Setty also acknowledged the need to ensure that depositors receive positive real returns as inflation rises, stating that "depositors need to be compensated with some level of positive real interest rate in such a scenario."
According to PTI, Setty confirmed that the RBI's rate hike of Wednesday, combined with SBI's house view of 0.50% more, will positively impact net interest margins for the next 2-3 quarters. Over 50% of loans in the banking system are tied to external benchmark-based lending rates that get repriced according to RBI's repo rate actions. Setty refrained from providing specific NIM levels citing the silent period before earnings announcement, stating that "whatever happens, I think this benefit (on NIMs) is available for 2-3 quarters." The RBI's rate hike was described as an adjustment to market rates that had already moved up, with bankers expecting liquidity to return to neutral or small deficit by end of December as the large surplus will diminish. Setty noted that while there is no ideal credit growth rate, "at least in SBI, we believe that you have to be 2-3 per cent more than the nominal GDP."
Latest economic projections suggest that headline inflation will remain above 5.5% YoY for three consecutive quarters starting in Q3 FY27, significantly above the RBI's medium-term target of 4% YoY. As per UBS Chief India Economist Tanvee Gupta Jain, "We expect a cumulative 50-75 bps rate hike cycle, with another 25bps hike likely in the December policy." Namrata Mittal, Chief Economist at SBI Funds Management, expects another cumulative 75 bps of hikes through the cycle, potentially taking the repo rate to 6.0%, though she highlights that the global environment remains highly fluid. RBI Governor Malhotra observed that "headline CPI inflation is expected to average almost 5.8% in the next three quarters and core inflation projected at 4.4% this financial year," making recalibration of policy rates imperative. Setty confirmed that the overall banking industry is expected to remain positive on the NIM front over the next two to three quarters.