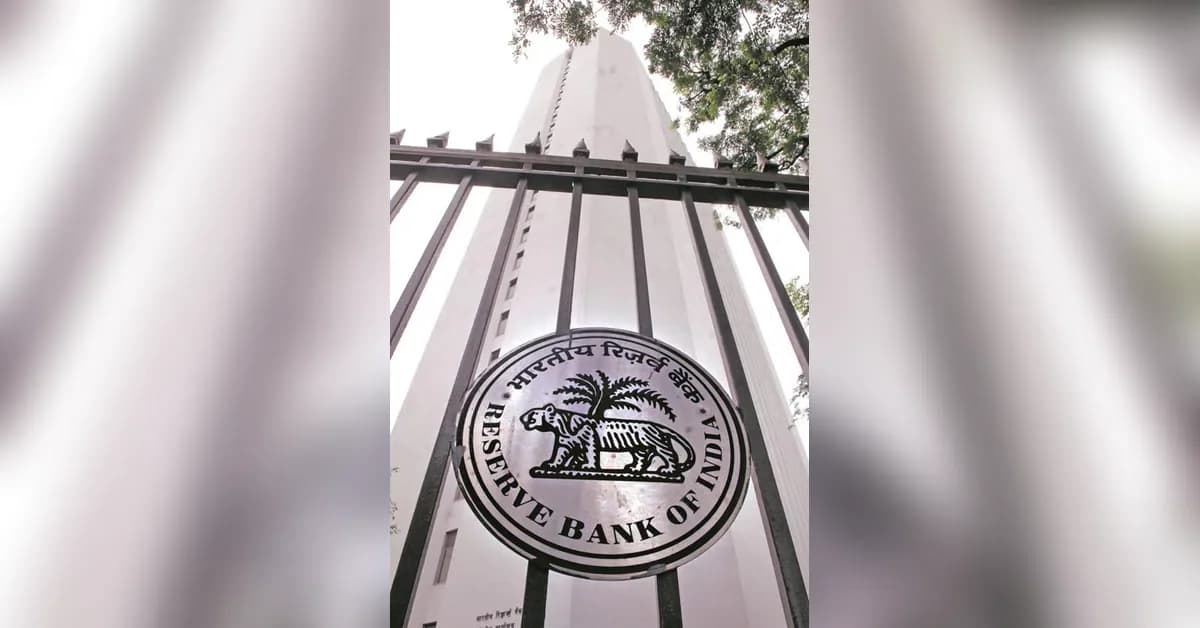
The Reserve Bank of India (RBI) issued a Master Direction on Expected Credit Loss (ECL) provisioning on April 27, marking the end of a three-decade rule-based provisioning system. According to reports from Business Standard, this regulatory shift represents a fundamental change in how banks approach loan loss management and risk assessment. The new framework will shift the focus from recognising bad loans to predicting them, making risk management a key differentiator for banks in the competitive landscape. As per Swaminathan J, Deputy Governor, RBI, the next phase of banking resilience will be less about addressing known balance sheet stress and more about managing complexity and uncertainty, with shocks arising from pandemics, geopolitical tensions, supply chain disruptions, and cyber incidents.
Under the new framework, banks must now provision before they incur a loss rather than after loans become non-performing. As reported by Business Standard, this requires banks to forecast future losses from loan health, economic stress scenarios and recovery assumptions. This represents a significant departure from the previous system where banks provisioned in fixed proportions after loans remained unpaid for a certain period. The ECL regime will scrutinise both the analytics and the judgmental overlay every quarter, creating new earnings impacts for financial institutions. According to Swaminathan's recent observations, risk has a habit of building quietly in good times and introducing itself loudly when conditions change, emphasizing the importance of building resilience before it is tested.
The ECL regime will shift the focus from recognising bad loans to predicting them, making risk management a key differentiator for banks. According to Business Standard, this regulatory change will likely result in earnings impacts as the regulator scrutinises both the analytics and the judgmental overlay every quarter. The new system requires banks to develop more sophisticated risk assessment models and forecasting capabilities. As per BCG's principal, data science, new bad loan provision measures will tell banks apart under ECL regime, highlighting the competitive advantage that effective risk management will provide in the new regulatory environment. According to Swaminathan, strong banks require capital and technology, but they also require judgment, governance, accountability and institutions that learn, making resilience about building capacity to respond to future shocks.
The new provisioning methodology will differentiate banks based on their risk management capabilities and forecasting accuracy. As reported by Business Standard, this regulatory change represents a significant shift from the previous rule-based approach to a more predictive and analytical framework for loan loss provisioning. The new system requires banks to develop more sophisticated risk assessment models and forecasting capabilities to meet the enhanced regulatory requirements. According to Swaminathan, banking resilience is not a fixed achievement but a continuing institutional project, built through discipline across the balance sheet and beyond, transparent recognition of stress, balance sheet strengthening, calibrated and adaptive regulation, and responsible conduct within banks. The Deputy Governor emphasized that resilience must be built before it is tested, with buffers, governance and risk discipline strengthened during strong growth periods when risk appetite naturally rises.