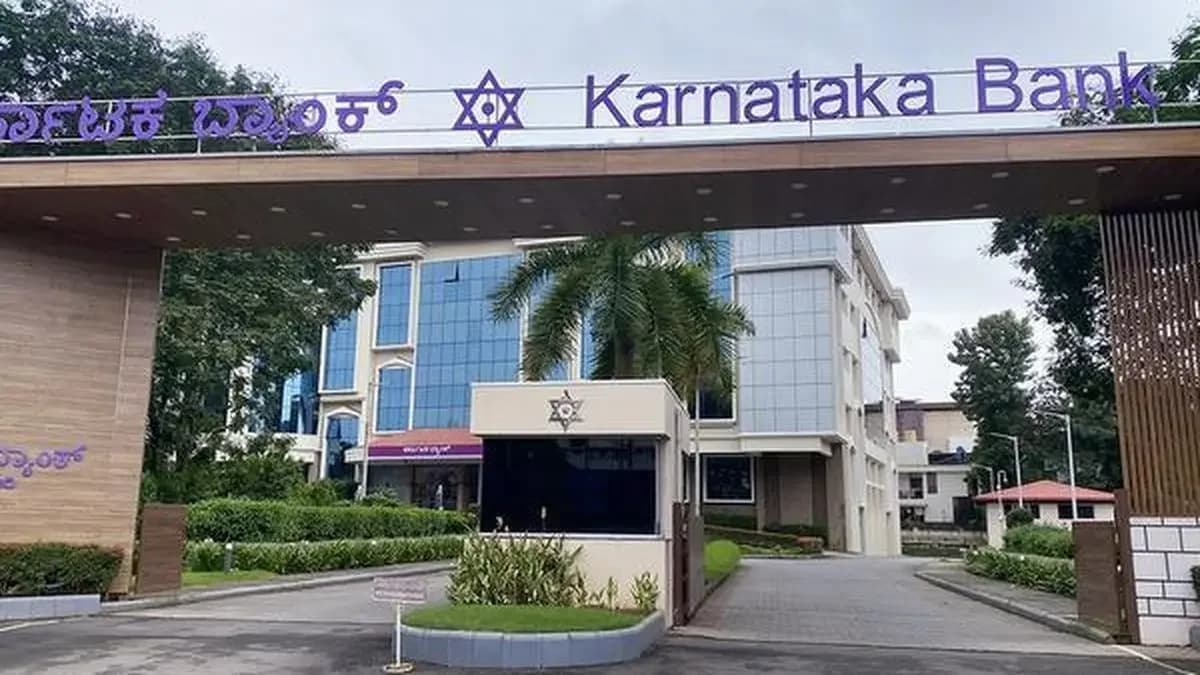
Karnataka Bank has successfully integrated with the Employees' Provident Fund Organization (EPFO) to enable seamless digital payment of provident fund contributions for EPFO members and establishments. According to a media statement, the integration became operational on June 1, 2026, marking a significant milestone in the bank's digital transformation journey. The integration allows customers to make EPF payments through the EPFO portal by selecting Karnataka Bank's internet banking facility at the EPFO payment page, ensuring faster processing, real-time validation, and instant transaction confirmation for all users. This strategic move is particularly impactful for Karnataka Bank's regional SME stronghold in South India, as the bank serves 13 million+ customers across India with 93% of total transactions already digital.
The integration offers real-time validation, instant confirmation, and reduces manual intervention, significantly enhancing the overall customer experience. The magnitude of operational change is substantial, with the integration reducing transaction turnaround time (TAT) by approximately 40% for corporate accounts. This efficiency improvement matters because it increases 'sticky' float in corporate accounts and reduces operational overhead for the bank's back-end reconciliation. The integration strengthens the bank's 'KBL-NxT' initiative to migrate traditional banking to high-efficiency digital channels, providing significant value propositions for Small and Medium Enterprises (SMEs) managing payroll and statutory dues. Customers can now make Provident Fund payments directly through Karnataka Bank's internet banking portal without switching platforms, reducing manual errors and ensuring real-time transaction confirmation.
This integration represents a defensive and offensive play to protect the bank's corporate deposit base while driving digital transaction growth. The move is critical for a mid-sized private lender like Karnataka Bank to serve as a primary clearing bank for statutory dues like EPFO, which is essential for maintaining low-cost deposits (CASA). The integration boosts the bank's fee-based income potential through transaction processing and improves the bank's operational efficiency ratio, which stood at 48% in the previous fiscal, potentially leading to better Return on Assets (ROA) in the long term. Digital expansion and institutional integration are likely to improve the bank's CASA stickiness, with the bank targeting a 35% CASA ratio goal. The bank recently reported a record annual net profit of ₹1,306 crore for FY24, reflecting a 10% YoY growth, with the stock trading at a P/B ratio of ~0.7x.
Raghavendra S Bhat, Managing Director and CEO of Karnataka Bank, emphasized the strategic importance of this digital initiative. According to the statement, Bhat stated that the integration marks another significant step in the bank's digital transformation journey, enabling employers and establishments to make EPF payments seamlessly, securely, and efficiently. The bank remains focused on leveraging technology to enhance customer convenience and deliver superior digital banking experiences. This move mirrors similar digital strides by larger peers like ICICI and HDFC Bank, but is particularly impactful for Karnataka Bank's regional SME stronghold in South India, where the bank has partnered with various fintech firms to enhance its digital lending capabilities under the 'KBL-NxT' banner.
The bank's commitment to leveraging technology to enhance customer convenience and deliver superior digital banking experiences was highlighted in the announcement. This initiative represents Karnataka Bank's continued focus on technology-driven solutions that improve operational efficiency and customer satisfaction in the provident fund payment sector. The integration is part of the broader trend of banks evolving into integrated financial services hubs rather than just credit providers. The timing is notable as digital payments in India's regulatory space continue to witness a 25% CAGR. While it initially enhances customer experience, it primarily aids in maintaining Current Account balances, with the bank aiming to drive higher digital volume, which has already crossed the 90% threshold of total transactions. The bank faces competitive pressure from larger private banks offering similar or bundled services, but this integration provides a defensive position in the competitive landscape.