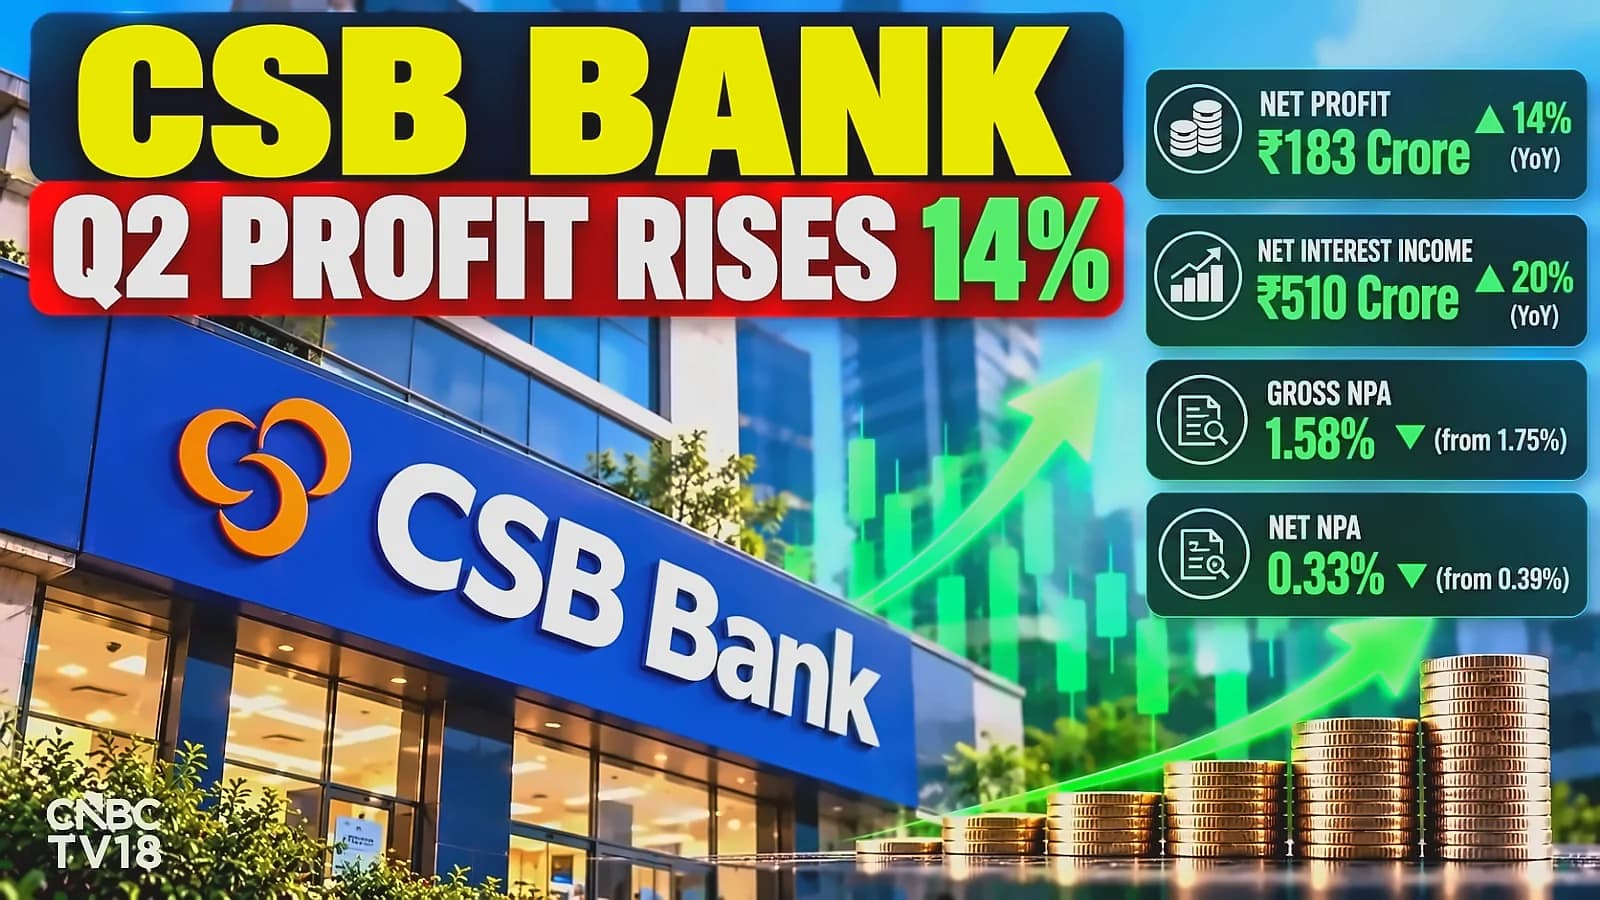
CSB Bank delivered robust financial results for the September quarter, with net profit rising 14% year-on-year to ₹183 crore from ₹160 crore in the corresponding quarter last year. According to recent reports, the bank's net interest income increased 20.4% year-on-year to ₹509.93 crore from ₹423.56 crore in the year-ago period, with Net Interest Margin (NIM) remaining stable at 3.81%. The bank's earnings exceeded the consensus estimate of ₹170 crore, signaling robust operational performance driven by strong interest income and controlled credit costs during the quarter. Interest earned rose to ₹1,339 crore in Q2FY27 from ₹1,109 crore in Q2FY26, a 21% YoY increase, primarily supported by higher interest on advances which climbed to ₹1,115 crore from ₹914 crore. However, other income declined to ₹274 crore from ₹349 crore year-on-year, impacting total income growth slightly.
The bank's asset quality showed significant improvement during the quarter. As reported by CNBC TV18, gross non-performing assets (NPAs) declined to 1.58% as of September 30, 2026, from 1.81% in the previous quarter and 1.81% a year earlier. Net NPAs fell to 0.33% from 0.52% sequentially and 0.52% year-on-year. Managing Director and CEO Pralay Mondal noted that the net NPA ratio was at its lowest in 11 quarters, while the gross NPA ratio of 1.58% was the lowest since the first quarter of FY26. Provisions declined significantly by 52.7% to ₹30 crore from ₹63.65 crore in the previous quarter, with provisions dropping to ₹30 crore during the September quarter compared to ₹63.7 crore year-on-year. The simultaneous decline in both gross and net NPAs alongside higher profitability indicates effective recovery mechanisms and reduced credit costs.
CSB Bank demonstrated strong growth across key business segments during the quarter, with advances growing 22.1% to ₹42,383 crore in Q2FY27 as against ₹34,712 crore in the same quarter last fiscal. According to The Hindu BusinessLine, total deposits rose 18.25% to ₹46,889 crore as of September 30, while net advances increased 22% to ₹41,852 crore. The growth in advances was supported by a 44% year-on-year increase in the wholesale portfolio and 36% growth in gold loans. The bank's gold loan portfolio stood at ₹22,303 crore, up 36% from ₹16,456 crore a year earlier. However, the CASA ratio declined to 18.96% in Q2FY27 from 21.17% in Q2FY26, indicating a shift towards term deposits which now constitute 78.31% of the deposit mix.
The bank's operational performance showed mixed results during the quarter. As reported by CNBC TV18, net operating income rose 11% quarter-on-quarter to ₹783 crore, while operating profit increased 10% sequentially to ₹276 crore. The cost-to-income ratio stood at 64.80%, compared with 64.55% in the June quarter and 63.86% a year earlier. The cost-to-assets ratio stood at 3.59% in Q2 FY27 compared to 4.11% in Q2 FY26 and 3.31% in Q1 FY27. A key divergence is visible in the funding structure: while advances grew 22% YoY, deposits grew only 18%, leading to an increase in the Gross CD Ratio to 90.39% from 87.54% in Q2FY26. The capital adequacy ratio stood at 19.55% as of September 30, 2026, compared with 20.99% a year earlier. Return on assets stood at 1.29%, compared with 1.33% in the year-ago quarter.
Looking ahead, CSB Bank's management expressed confidence in sustaining growth momentum. As reported by The Hindu BusinessLine, MD and CEO Pralay Mondal stated that the bank remains focused on sustaining this momentum and plans to accelerate growth across key business segments in the second half of FY27. Mondal emphasized that the bank is moving steadily towards its SBS2030 aspiration of becoming a mid-sized bank. The bank's strategic focus on maintaining asset quality improvements while expanding business segments positions it well for achieving its long-term growth objectives. The combination of strong operational performance, controlled credit costs, and strategic business expansion demonstrates the bank's commitment to sustainable growth while maintaining financial stability.